Mexico Macro Daily(Beta Mode)
Mexico Yields Rise as Peso Weakens
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| IPC Bolsa | 63,536.96 | +0.25% |
| USD/MXN | 17.44 | +1.28% |
| EUR/MXN | 19.89 | +0.79% |
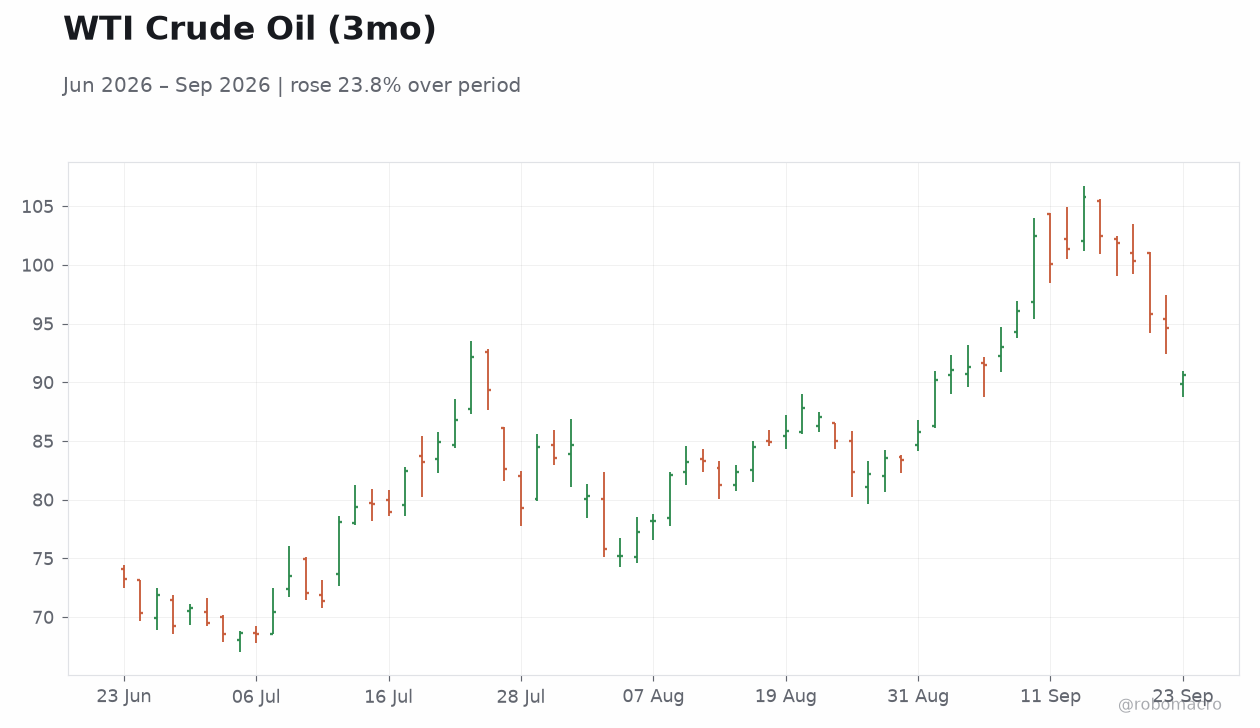
| WTI Crude | 90.60 | -4.22% |
| Silver | 65.68 | -0.38% |
| Gold | 4,351.40 | -0.57% |
| Brent Crude | 96.28 | -2.99% |
| Bitcoin | 85,458.03 | -0.83% |
| Mexico 5Y Govt Yield | 9.00% | +35 bp |
| Mexico 10Y Govt Yield | 9.35% | +19 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
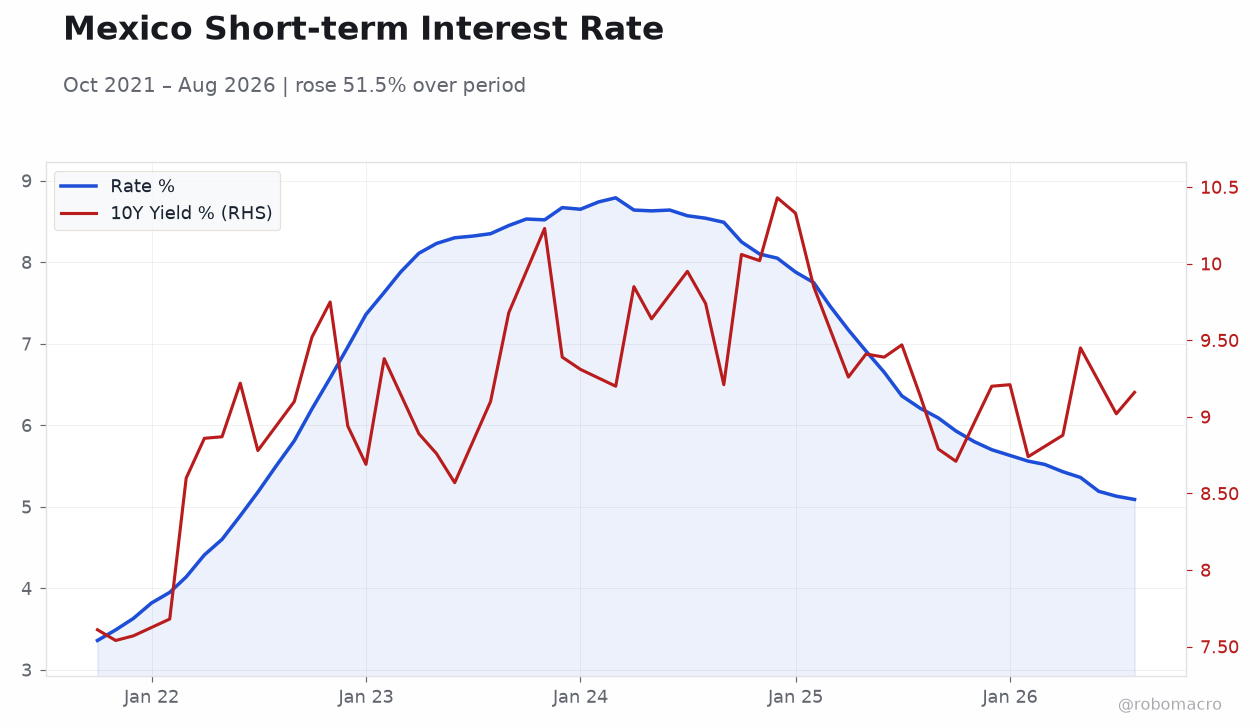
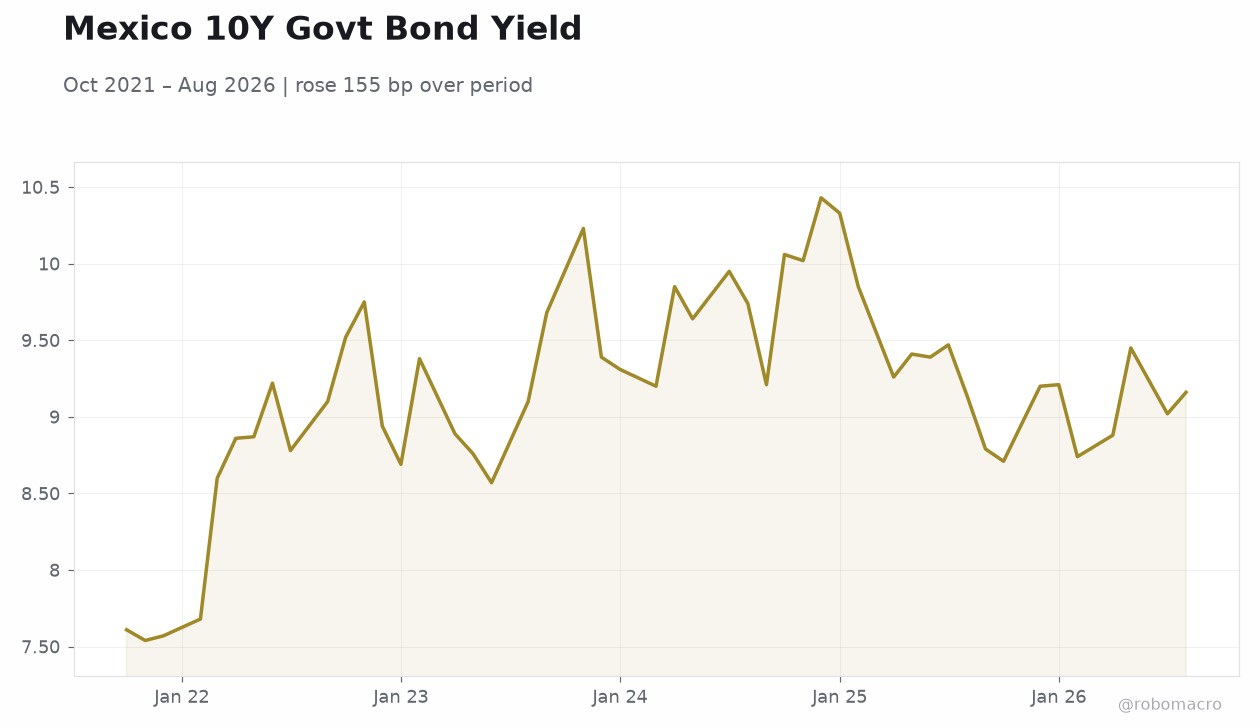 Mexico 10Y Govt Bond Yield | Type: macro_line | Yield %: 9.16 (2026-08-01) | Range: 7.54–10.43 | Trend(5pt): 7.61,8.94,9.85,9.39,9.16
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- IPC Bolsa edges up 0.25% to 63,536.96 while USD/MXN rises 1.28% to 17.44
- Mexico 5Y yield climbs 35 bp to 9.00% and 10Y yield adds 19 bp to 9.35%
- No domestic data releases leave markets focused on external oil and risk drivers
Yesterday's Recap
Mexican markets recorded limited movement on 22 September with no scheduled economic releases. The IPC Bolsa advanced 0.25 percent to close at 63,536.96 while USD/MXN climbed 1.28 percent to 17.44 and EUR/MXN gained 0.79 percent to 19.89. WTI crude fell 4.22 percent to 90.60 and Brent crude declined 2.99 percent to 96.28, weighing on sentiment.
Mexico 5Y government yields rose 35 basis points to 9.00 percent and 10Y yields increased 19 basis points to 9.35 percent, reflecting modest repricing of near-term policy expectations. Hurricane Polo intensified to 165 mph winds 215 miles south of Zihuatanejo, though direct landfall remains unlikely. NEXT10 Inc.
activated its first gold-mining operation at Panuco with an initial 507,000-dollar investment aimed at raising output through 2027.
The Day Ahead
No Mexican data prints or Banxico events are scheduled for 23 September. Attention will therefore turn to external factors including U.S. data releases, global oil-price movements and broader risk sentiment.
The peso’s recent depreciation and the sharp rise in short-end yields suggest markets remain sensitive to any shift in external financing conditions. Coastal disruption risks from Hurricane Polo could affect local supply chains even without direct landfall. Participants will monitor any follow-through commentary from Banxico officials on the 6.50 percent policy rate and the 3.26 percent August CPI reading.
Other Economic Notes
The absence of fresh inflation or activity data leaves the current Banxico stance unchanged. Gold-sector investment at Panuco signals continued foreign interest in Mexican mining assets despite softer precious-metal prices. Hurricane Polo’s rapid strengthening under El Niño conditions highlights seasonal weather risks to coastal infrastructure and tourism.
Broader nearshoring momentum and USMCA trade flows remain the dominant structural themes for medium-term growth, though no new policy updates emerged yesterday.