Mexico Macro Daily(Beta Mode)
Banxico Set to Hold as Peso Weakens
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| IPC Bolsa | 64,276.72 | +1.16% |
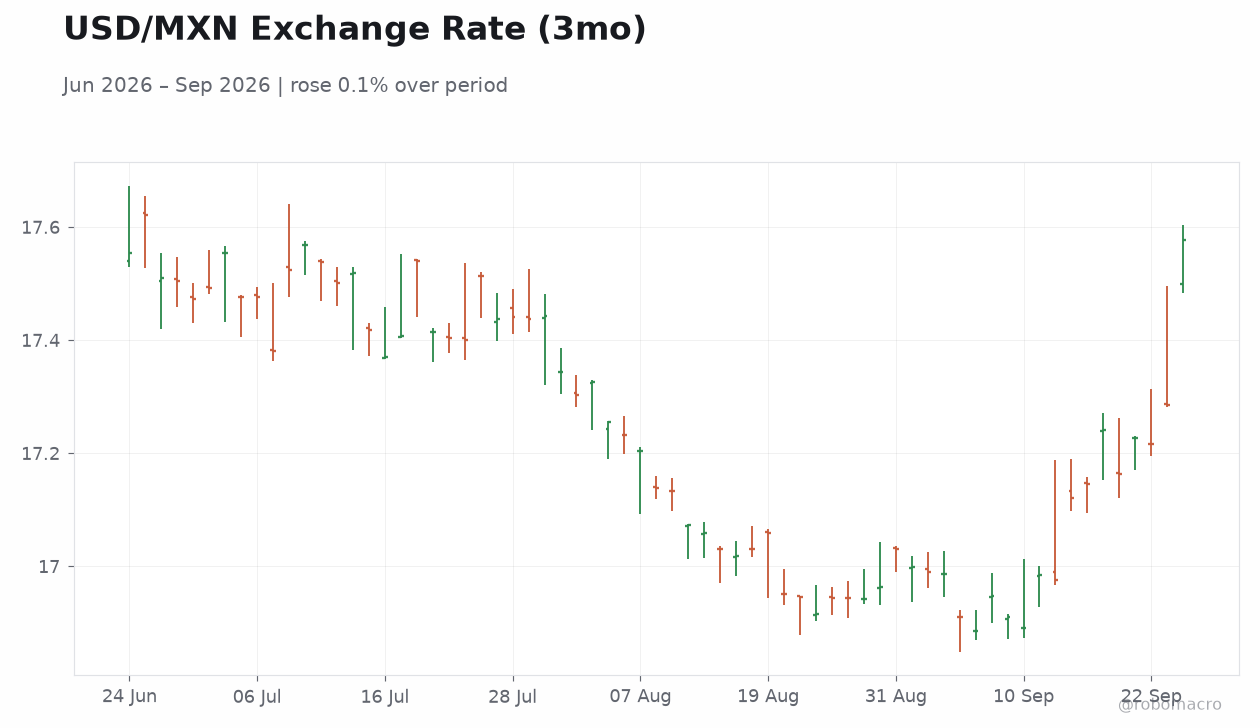
| USD/MXN | 17.57 | +1.66% |
| EUR/MXN | 19.98 | +0.91% |
| WTI Crude | 93.73 | +1.70% |
| Silver | 63.92 | -0.73% |
| Gold | 4,295.10 | -0.54% |
| Brent Crude | 105.06 | +1.92% |
| Bitcoin | 83,395.69 | -1.17% |
| Mexico 5Y Govt Yield | 9.00% | +35 bp |
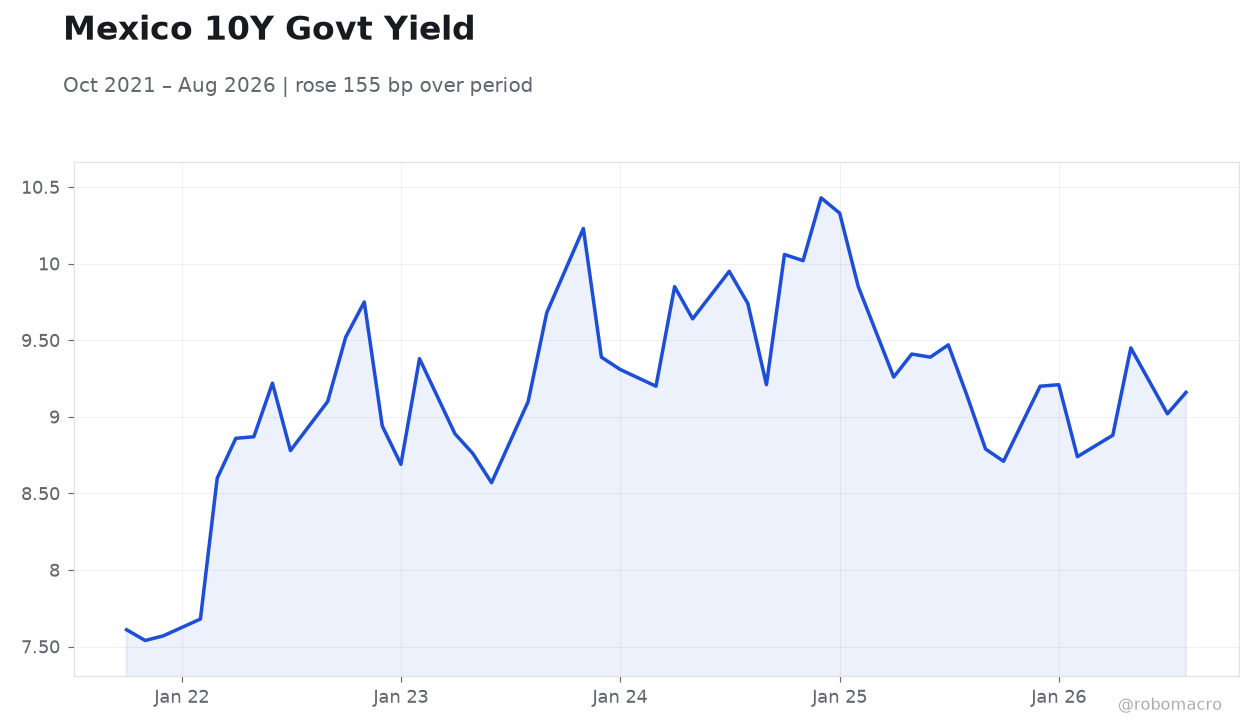
| Mexico 10Y Govt Yield | 9.35% | +19 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
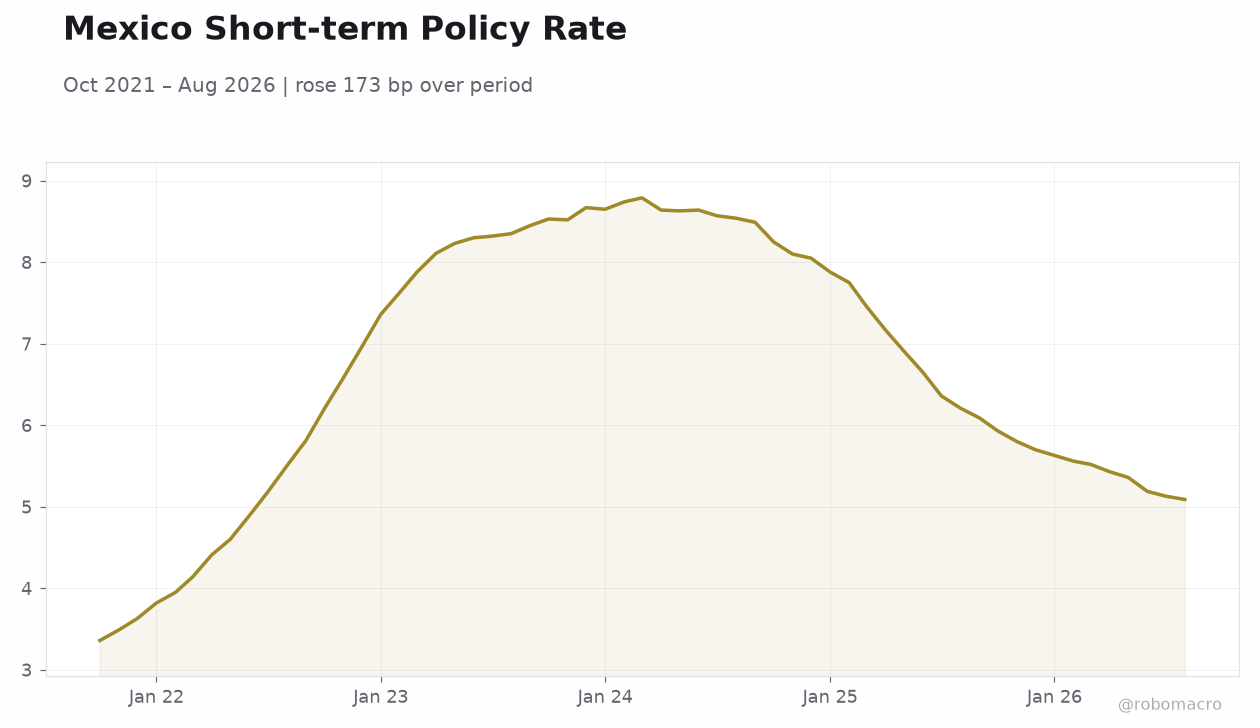 Mexico Short-term Policy Rate | Type: macro_line | Policy Rate %: 5.09 (2026-08-01) | Range: 3.36–8.79 | Trend(6pt): 3.36,6.96,8.74,7.17,5.19,5.09
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- IPC Bolsa rises 1.16% to 64,276.72 while USD/MXN jumps 1.66% to 17.57
- Mexico 5Y yield climbs 35 bp to 9.00% and 10Y yield adds 19 bp to 9.35%
- Banxico set to hold policy rate at 6.50% amid mixed inflation signals
Yesterday's Recap
Mexican markets closed mixed on September 23 with no domestic data releases. The IPC Bolsa advanced 1.16% to 64,276.72 while WTI crude gained 1.70% to 93.73 and Brent crude rose 1.92% to 105.06. The peso weakened sharply, lifting USD/MXN 1.66% to 17.57 and EUR/MXN 0.91% to 19.98.
Mexican government bond yields moved higher across the curve, with the 5-year yield surging 35 bp to 9.00% and the 10-year yield increasing 19 bp to 9.35%. Gold and silver declined while Bitcoin fell 1.17% to 83,395.69. No Banxico statements or speeches occurred during the session.
Hurricane Polo, though downgraded, remains a powerful Pacific storm fueled by El Niño-related warm waters and continues to affect Mexico’s coastline.
The Day Ahead
The economic calendar remains empty on September 24 with zero scheduled releases. Traders will monitor any follow-up comments from Banxico officials on the policy outlook. Hurricane Polo, though downgraded, continues to track off Mexico’s Pacific coast and may affect sentiment toward energy and agriculture.
Market focus stays on peso volatility and carry-trade flows given the narrowing rate differential with the Fed. No minutes or inflation prints are due before the next policy meeting. NEXT10, Inc.
activated its first gold-mining operation at Panuco with an initial $507,000 investment and plans further capital deployment.
Other Economic Notes
Prime Minister Modi is accelerating trade talks with Mexico alongside a planned Canada visit, underscoring Mexico’s role in diversified supply chains. El Niño-driven warm waters continue to fuel Pacific storms, adding seasonal risk to coastal infrastructure and output. Nearshoring momentum persists but faces headwinds from higher local yields and peso depreciation.
The peso’s reversal reduces the appeal of carry trades, pressuring local assets even as oil prices climb and support Mexico’s fiscal position via Pemex revenues.