Mexico Macro Daily(Beta Mode)
Mexico Trade Miss Weakens Peso
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| IPC Bolsa | 63,828.60 | -0.60% |
| USD/MXN | 18.32 | +1.35% |
| EUR/MXN | 20.58 | +0.51% |
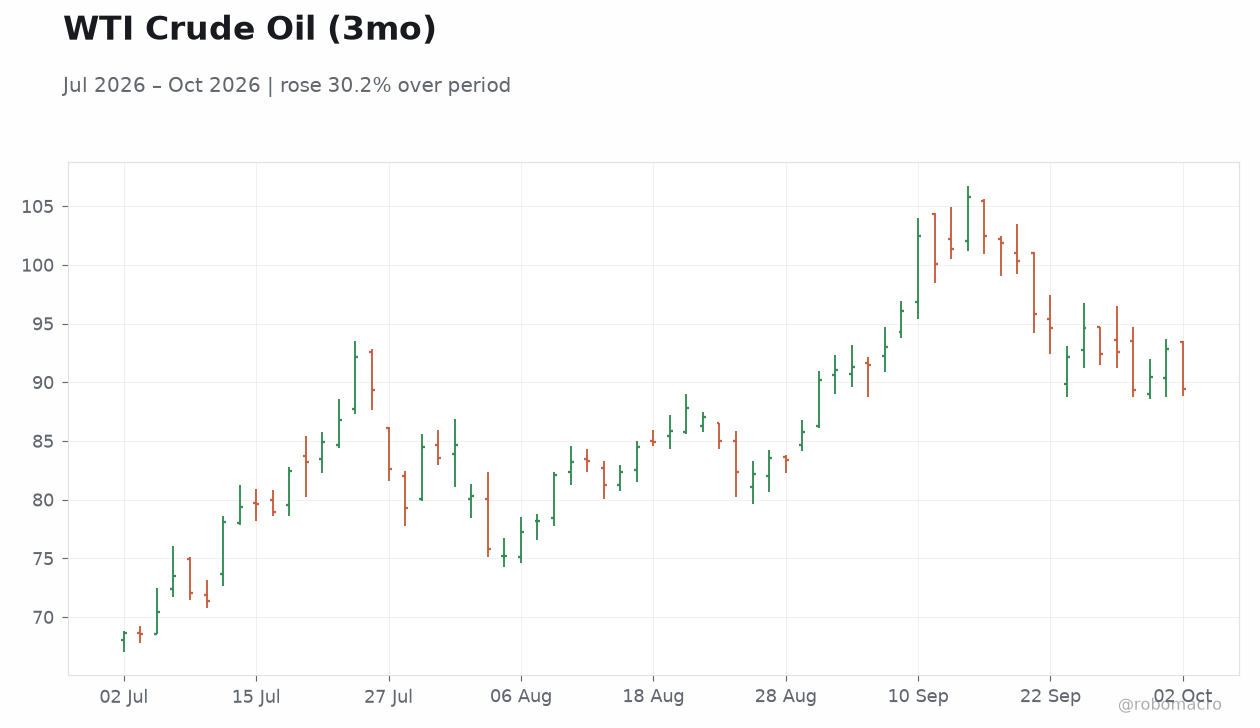
| WTI Crude | 89.44 | -3.69% |
| Silver | 61.37 | +1.06% |
| Gold | 4,208.50 | +0.15% |
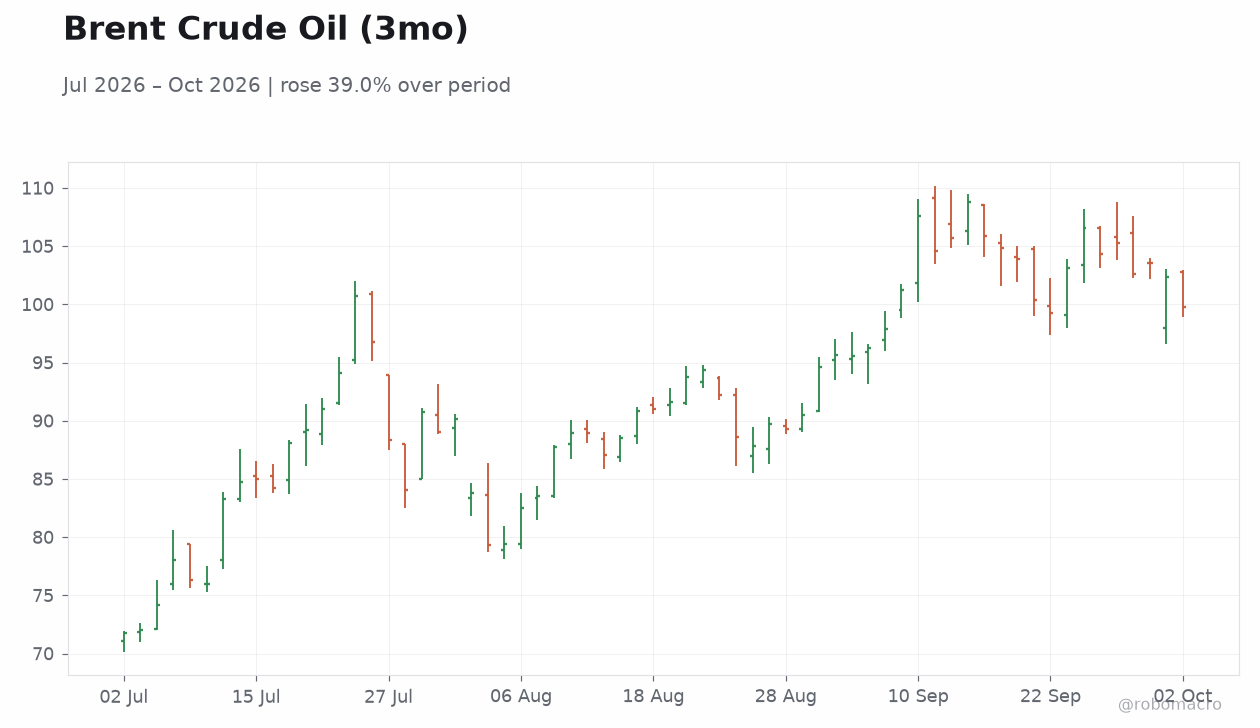
| Brent Crude | 99.77 | -2.48% |
| Bitcoin | 86,410.98 | +1.84% |
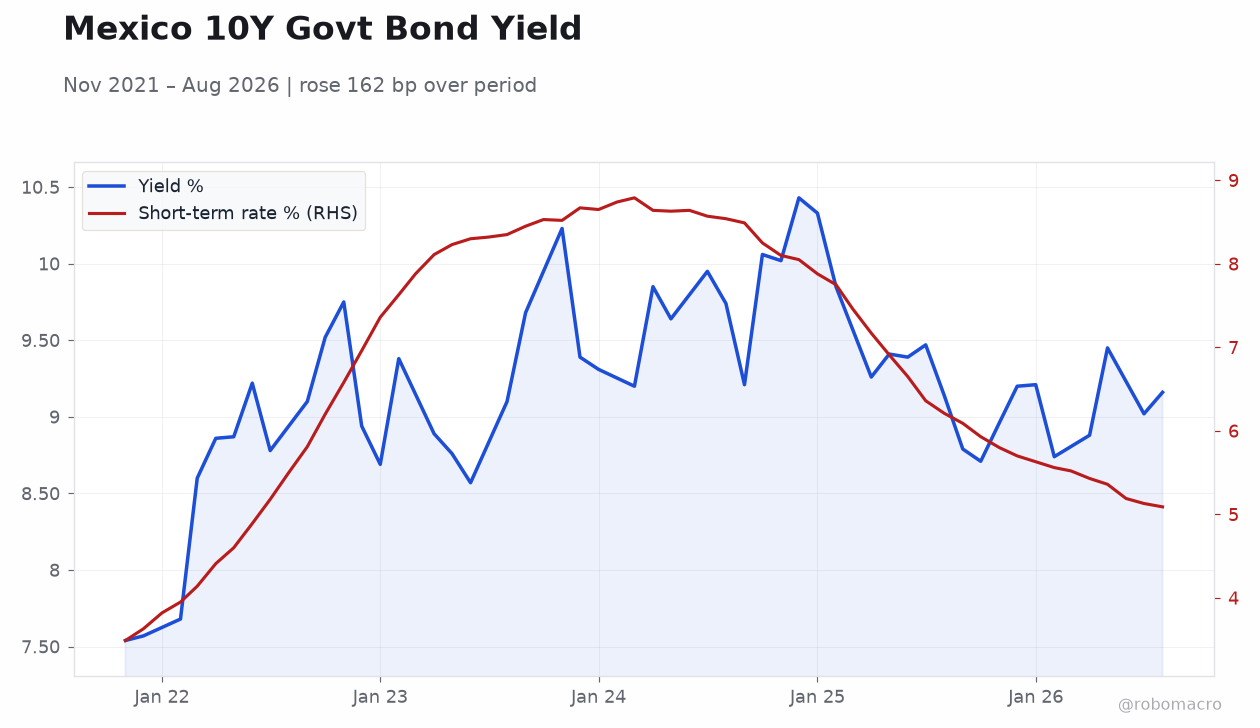
| Mexico 10Y Govt Yield | 9.35% | +19 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| Trade Balance | -848m | 1,400m | 605m |
| Business Confidence Index | 48.10 | - | 48 |
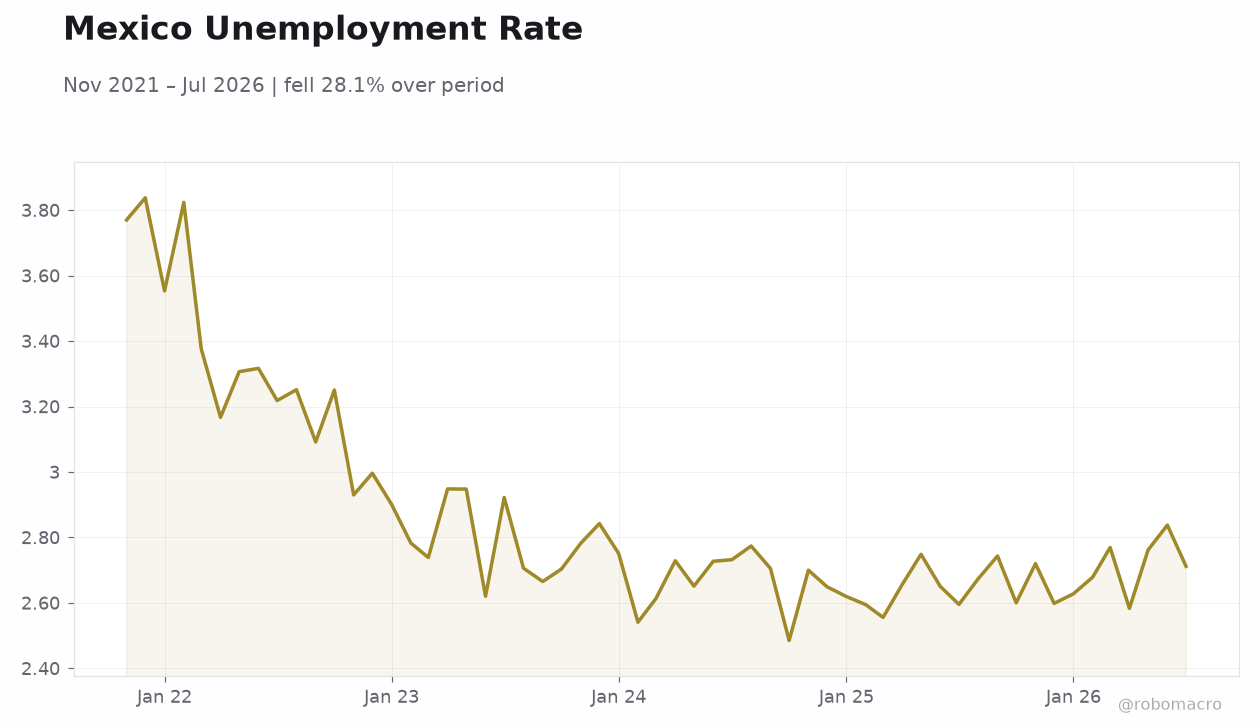 Mexico Unemployment Rate | Type: macro_line | Unemployment rate %: 2.712 (2026-07-01) | Range: 2.485–3.838 | Trend(5pt): 3.77,2.901,2.614,2.748,2.712
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- Mexico trade balance printed +605 million USD, below 1.4 billion consensus.
- Business confidence index fell to 48.0 from 48.1.
- USD/MXN rose 1.35% to 18.32 while 10-year yield climbed 19 bp to 9.35%.
Yesterday's Recap
Mexico’s trade balance swung to a 605 million USD surplus, improving from the prior 848 million deficit yet falling short of the 1.4 billion consensus. The Business Confidence Index eased one-tenth to 48.0, signaling stable but subdued sentiment among firms. The IPC Bolsa closed 0.60% lower at 63,828.60 as investors digested the mixed external accounts print.
USD/MXN jumped 1.35% to 18.32, while EUR/MXN advanced 0.51% to 20.58 amid broader dollar strength. The Mexico 10-year government yield rose 19 basis points to 9.35%, reflecting higher term premia. WTI crude fell 3.69% to 89.44, pressuring energy-related revenues.
No Banxico officials spoke, leaving markets to focus on the peso’s reaction to the data shortfall.
The Day Ahead
No Mexican economic releases are scheduled for October 2, leaving markets without fresh domestic catalysts. Attention will center on peso flows and any USMCA-related headlines from Washington. Traders will monitor oil price rebounds given Mexico’s fiscal reliance on energy exports.
Global risk sentiment, particularly US nonfarm payrolls due later, could influence USD/MXN volatility. The absence of Banxico commentary keeps policy expectations anchored to the September 29 decision. Participants will watch 10-year yields for further signs of term-premium expansion.
Other Economic Notes
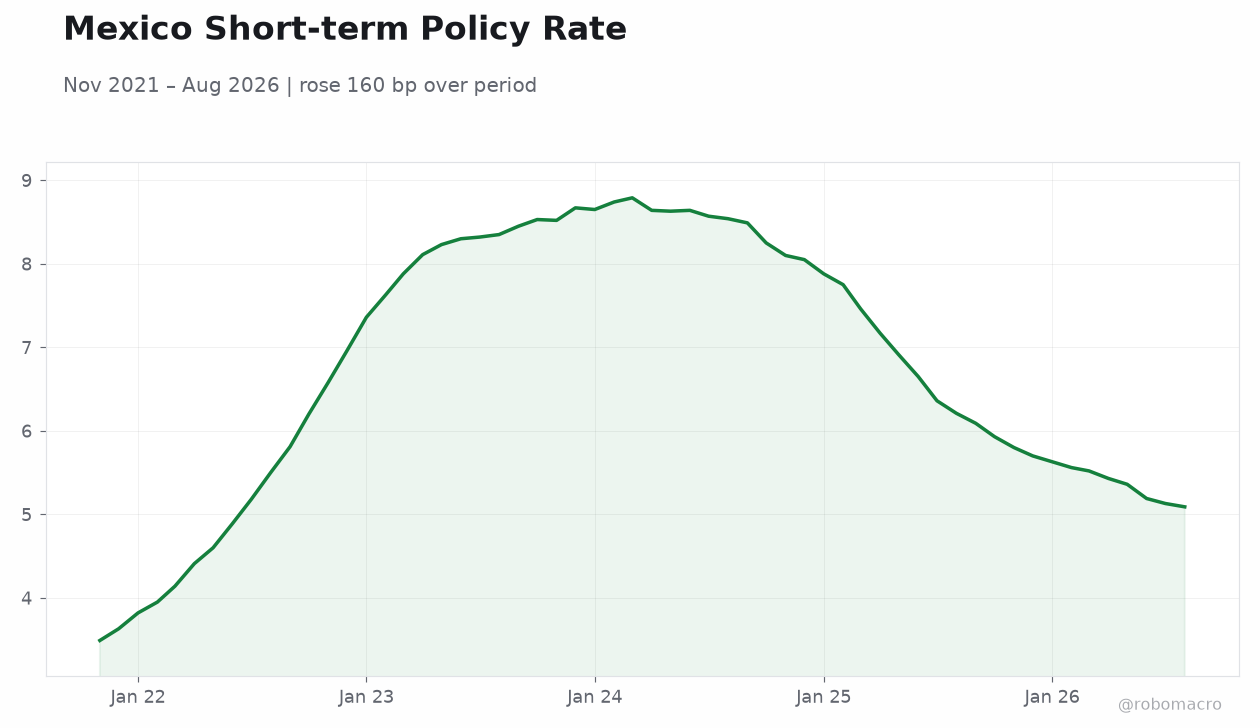
Mexico’s August CPI at 3.26% remains within Banxico’s tolerance band, supporting the current 6.50% policy rate. Nearshoring momentum continues to underpin manufacturing investment despite softer business confidence. USMCA trade flows remain the dominant external driver, with the latest surplus narrowing highlighting vulnerability to global demand shifts.
Remittance inflows and foreign direct investment in northern states provide structural peso support even as short-term data disappointed. Energy price weakness adds downside risk to fiscal accounts ahead of the 2027 budget cycle.