RoboMacro ResearchAlso todaySee the FX Daily

Mexico Macro Daily(Beta Mode)

October 20, 2026 robomacro.com

Peso Slips as Oil Volatility Tests Banxico

IPC Bolsa69,010.67+0.12%
USD/MXN18.50+0.32%
EUR/MXN20.75+0.23%
WTI Crude100.78-2.78%

Market Snapshot

AssetLevelChange
IPC Bolsa69,010.67+0.12%
USD/MXN18.50+0.32%
EUR/MXN20.75+0.23%
WTI Crude100.78-2.78%
Silver57.27+0.52%
Gold4,139.20-0.50%
Brent Crude111.43+1.72%
Bitcoin81,422.53-0.53%
Mexico 10Y Govt Yield--

Prior Economic Events

Data Prior Cons Actual
No events available
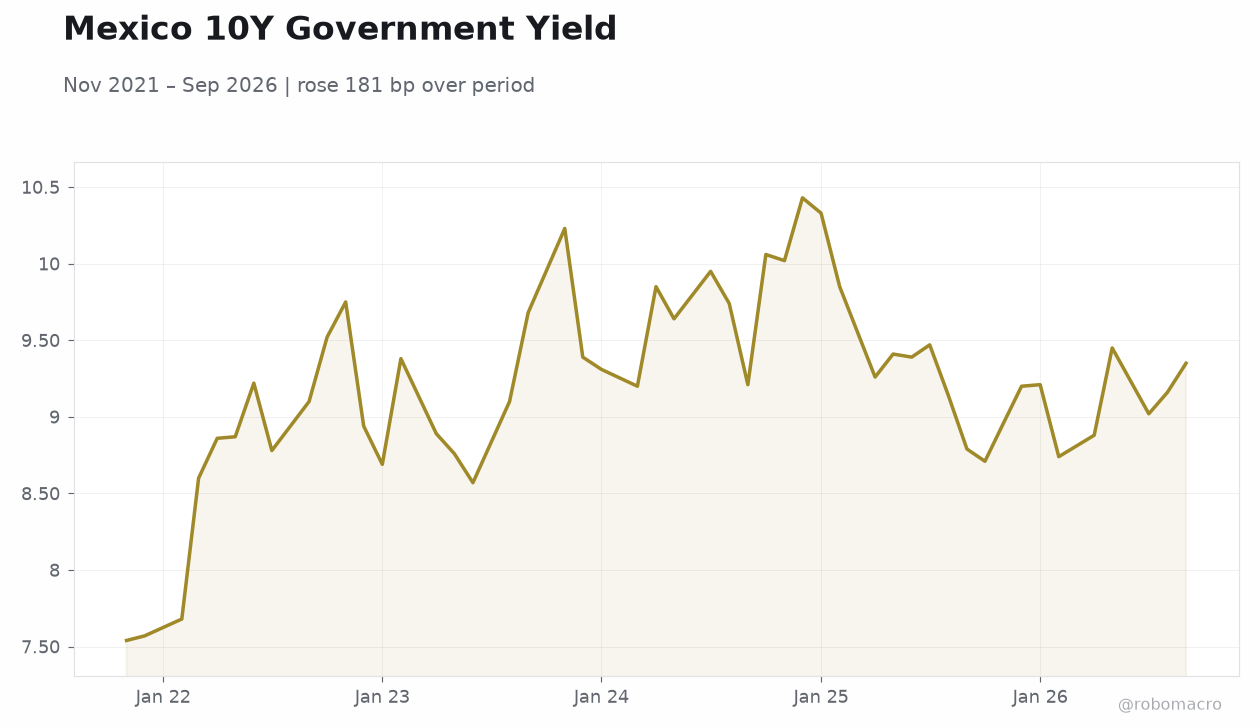
Mexico 10Y Government YieldMexico 10Y Government Yield | Type: macro_line | 10Y Yield %: 9.35 (2026-09-01) | Range: 7.54–10.43 | Trend(5pt): 7.54,8.69,9.64,9.47,9.35

Today's Economic Events

Data Prior Cons Time
No events available
  • USD/MXN pushed to 18.50 (+0.32%) as oil-market volatility and a softer gold tape weighed on risk appetite for Mexican assets.
  • IPC Bolsa edged up 0.12% to 69,010.67, outperforming broader LatAm peers despite the peso's slide.
  • Banxico's 6.50% policy rate and 3.45% CPI keep the real-rate buffer intact, but the committee's forward guidance remains the key swing factor for carry positioning.

Yesterday's Recap

Mexico's trading session on October 19 was defined by a firmer dollar and a mixed commodity tape, with USD/MXN closing at 18.50 after a 0.32% daily advance that kept the pair pinned near recent ranges. The IPC Bolsa managed a modest 0.12% gain to 69,010.67, suggesting domestic equity flows remain resilient even as currency volatility picks up. EUR/MXN rose 0.23% to 20.75, tracking broad euro strength rather than Mexico-specific drivers.

Crude markets diverged sharply: WTI fell 2.78% to 100.78 while Brent rose 1.72% to 111.43, a spread widening that complicates the fiscal and export revenue outlook for Pemex and the sovereign budget. Precious metals were mixed, with gold down 0.50% to 4,139.20 and silver up 0.52% to 57.27. Bitcoin slipped 0.53% to 81,422.53, offering little directional signal for EM risk sentiment.

No scheduled Mexican data releases printed during the session, leaving price action driven by external flows and positioning.

The Day Ahead

The October 20 calendar is light on scheduled Mexican releases, so markets will lean on external catalysts and Banxico communication for direction. Traders will watch the peso's reaction to crude spreads, particularly whether WTI's weakness bleeds into broader risk-off sentiment that typically pressures EM currencies. Domestic fixed-income desks will monitor the 10-year government yield for any spillover from US Treasury moves, though no official print is scheduled.

Equity flows into the IPC will be tested by whether the index can hold above the 69,000 handle amid currency softness. With no tier-one data on deck, positioning ahead of the next inflation and activity prints becomes the dominant theme. Any Banxico speaker commentary will be parsed for shifts in the easing bias.

Other Economic Notes

Mexico's macro backdrop remains anchored by a 6.50% policy rate that preserves one of the highest real-rate buffers in LatAm against 3.45% CPI, a configuration that continues to support carry demand for the peso. ↓ p.2
Page 1

Mexico Macro Daily(Beta Mode)

October 20, 2026 robomacro.com
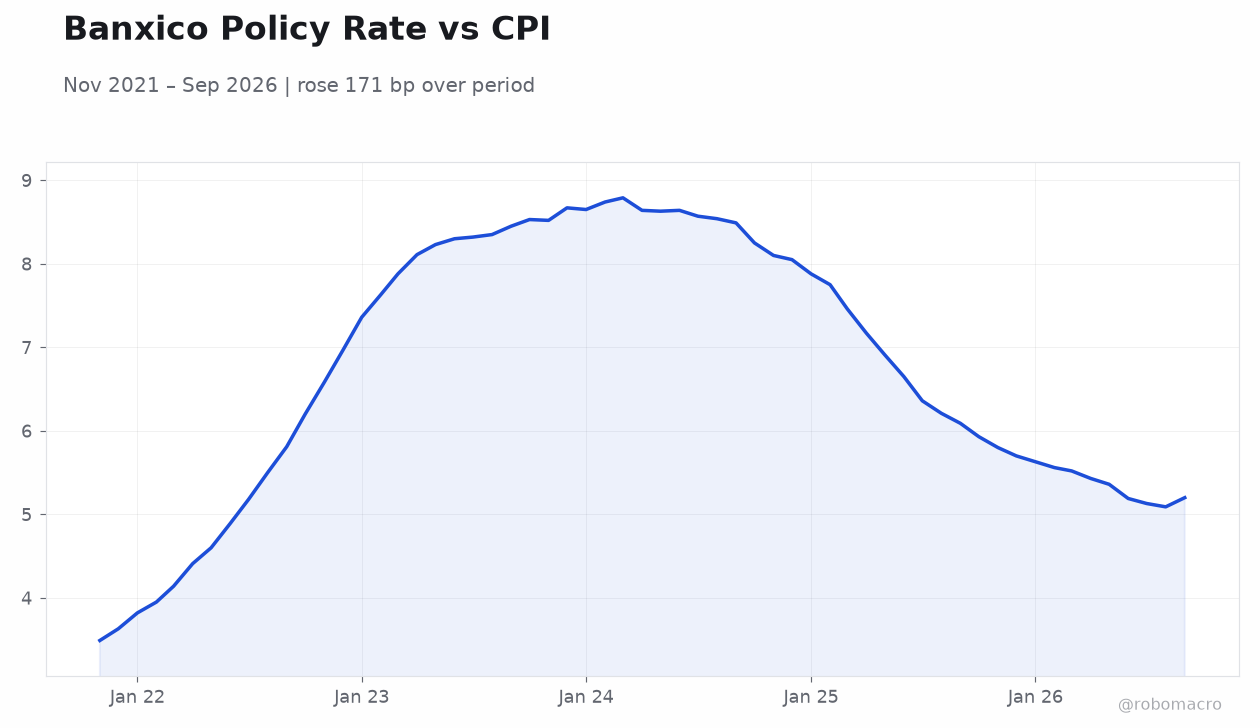
Banxico Policy Rate vs CPI Banxico Policy Rate vs CPI | Type: macro_line | Policy Rate %: 5.2 (2026-09-01) | Range: 3.49–8.79 | Trend(6pt): 3.49,7.36,8.79,6.91,5.13,5.2
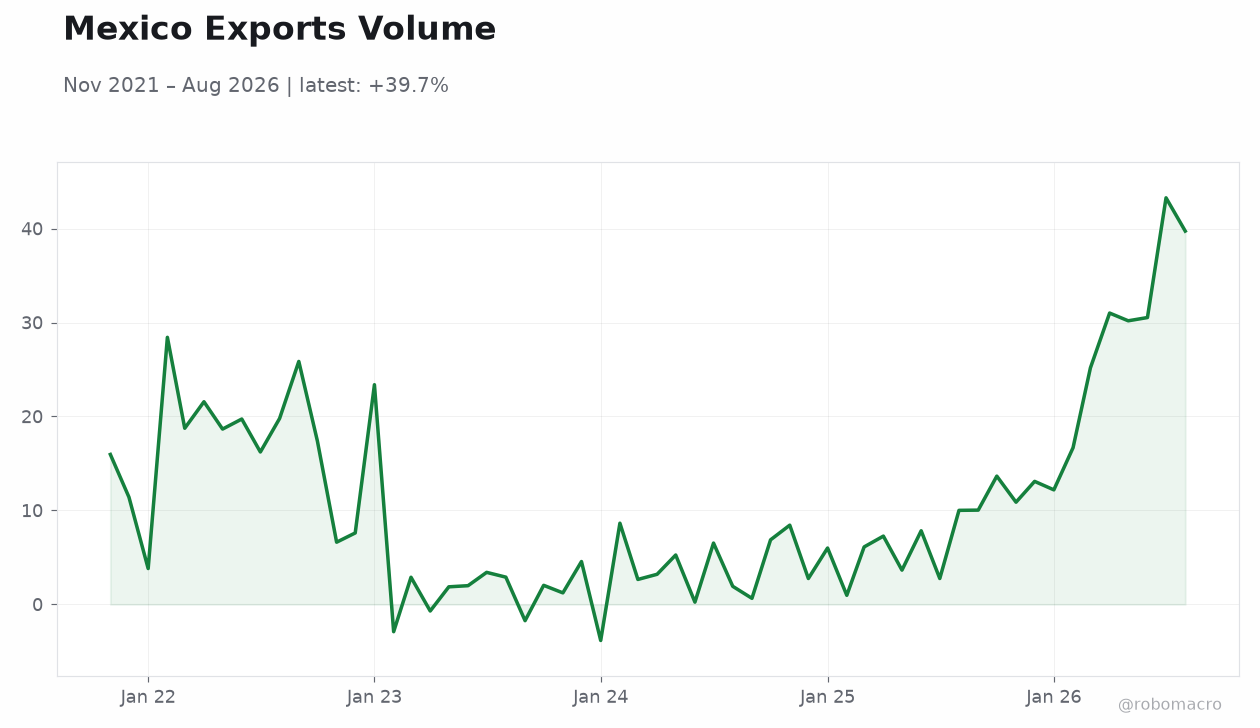
Mexico Exports Volume Mexico Exports Volume | Type: macro_line | Exports: 39.73 (2026-08-01) | Range: -3.843–43.27 | Trend(6pt): 15.96,23.38,2.654,3.644,43.27,39.73
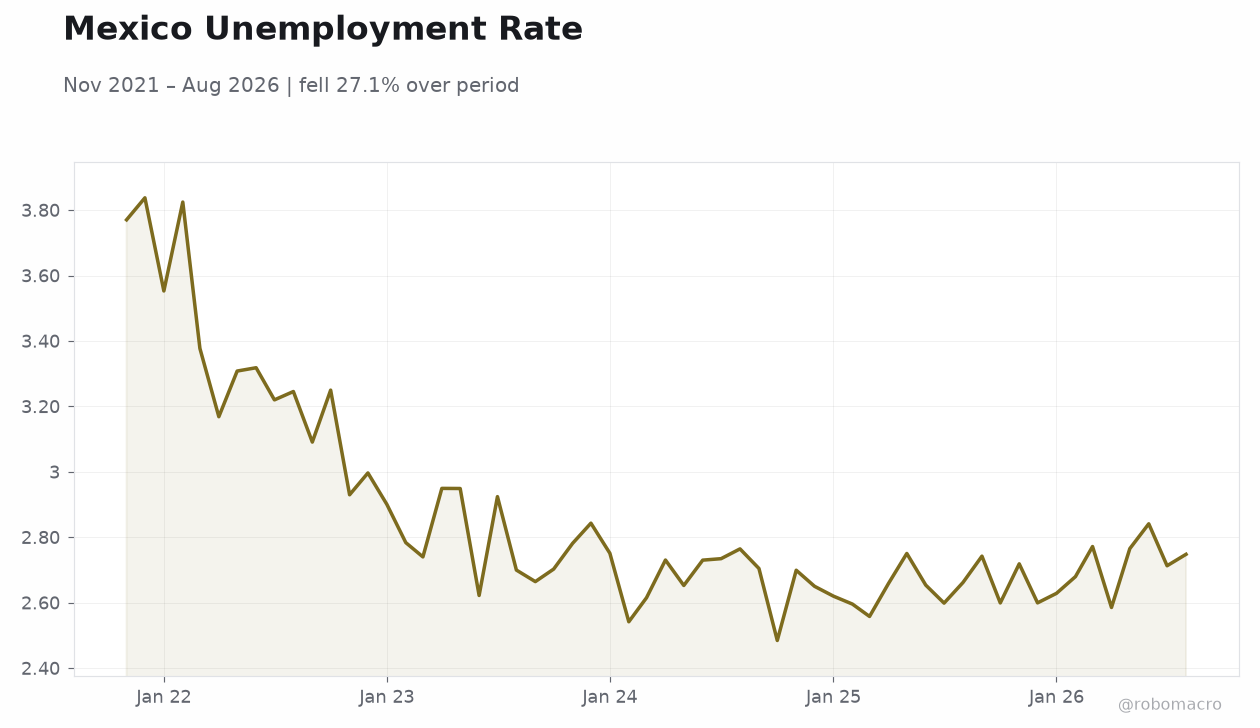
Mexico Unemployment Rate Mexico Unemployment Rate | Type: macro_line | Unemployment %: 2.748 (2026-08-01) | Range: 2.485–3.837 | Trend(6pt): 3.77,2.901,2.615,2.75,2.713,2.748
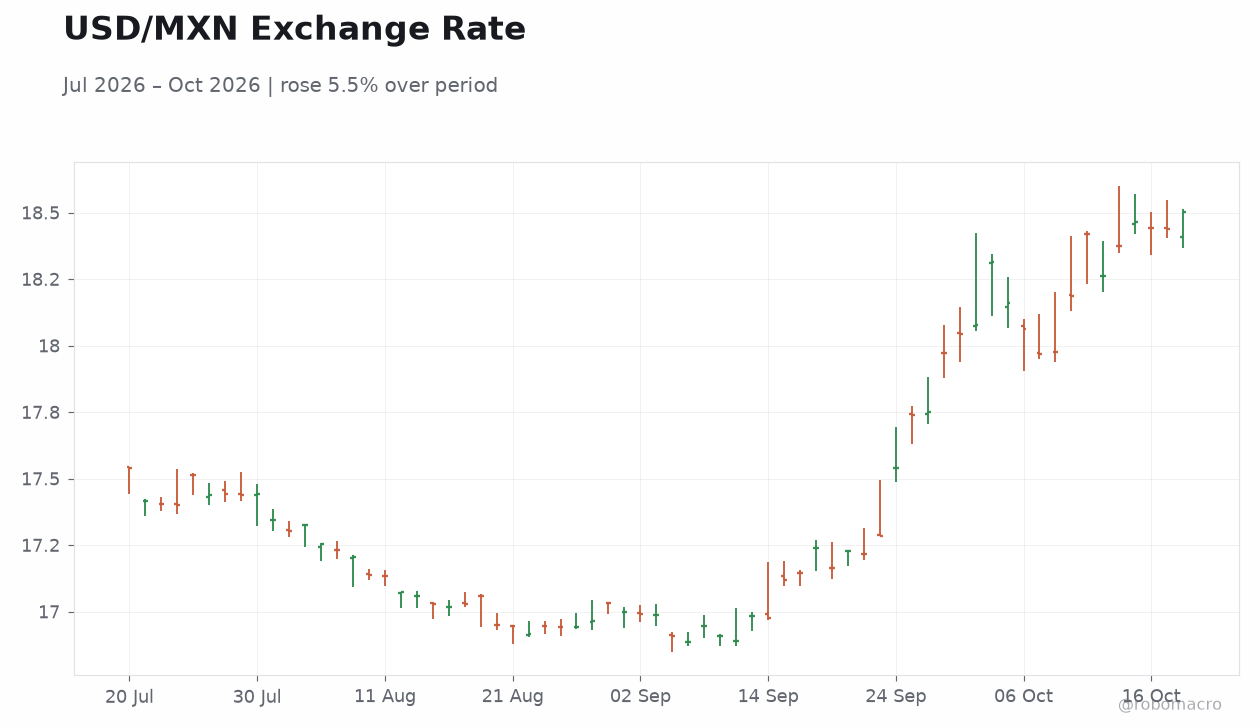
USD/MXN Exchange Rate USD/MXN Exchange Rate | Type: market_hloc | USD/MXN: 18.5 (2026-10-20) | Range: 16.89–18.5 | Trend(6pt): 17.54,17.13,16.99,17.54,18.44,18.5

Other Economic Notes (continued)

Nearshoring flows remain the structural story, with railcar lessor Infinity Transportation's $2.9bn sale to Ares highlighting continued cross-border logistics investment tied to US-Mexico supply chains. Hurricane Trudy's approach to the Pacific coast introduces a short-term weather risk to agricultural output and port activity, though the storm weakened to a tropical storm before landfall. The divergence between WTI and Brent complicates the fiscal math, since Mexican crude export pricing tends to track heavier sour grades rather than either benchmark cleanly.

USMCA trade flows remain the dominant medium-term variable for manufacturing and FDI.

Global Macro News

Global markets are contending with a Wall Street selloff that has revived debate over whether the Fed will hold rates rather than continue easing, a shift that would tighten external financial conditions for Mexico. China's trade surplus nearing $1 trillion on surging exports signals continued competitive pressure on Mexican manufacturing in US markets, a key USMCA flashpoint. Brazil's economy is expected to slow next year on high interest rates and lower spending, a regional reminder that restrictive policy is biting across LatAm.

The IMF has flagged that the Bank of Japan may need to raise rates faster, adding to global duration volatility that can transmit into Mexican bond markets. Australia's RBA is navigating extreme rates toward a potential recession, reinforcing the theme of over-tightening risk globally. ↓ p.3

Sponsored by Arbitrage Search
Page 2

Mexico Macro Daily(Beta Mode)

October 20, 2026 robomacro.com

Continuation

Global Macro News (continued)

Vietnam's central bank is lowering rates to support growth while managing deposit-rate competition, illustrating Asia's easing bias. Greece's deadly floods and Hurricane Trudy underscore rising climate-related supply shocks affecting commodity and insurance channels relevant to Mexico.

Banxico Watch

Banxico's 6.50% policy rate, confirmed as of October 13, reflects a committee that has moved deliberately while keeping the real rate firmly positive against 3.45% CPI. The forward guidance embedded in recent communications emphasizes data dependence and caution about easing too quickly, particularly with the peso sensitive to external risk sentiment. Markets should read the current stance as a carry-supportive configuration: with the rate well above inflation, the peso retains a yield advantage that cushions episodes like the current 0.32% daily depreciation.

The committee has not signaled an imminent acceleration of cuts, and without a published vote split, the guidance language itself is the primary signal to monitor. Any shift toward a more dovish tone would compress the real-rate buffer and likely weaken the peso toward the upper end of its range. Conversely, a reaffirmation of patience would reinforce the 18.50 area as a near-term anchor.

Inflation targeting credibility remains intact, but the interplay between easing bias and currency stability is the central tension for fixed-income and FX positioning.

Sponsored by Arbitrage Search
Page 3