RoboMacro ResearchAlso todaySee the FX Daily

Mexico Macro Daily(Beta Mode)

October 26, 2026 robomacro.com

Peso Firms as 10-Year Yield Eases 10bp

IPC Bolsa69,879.62-0.01%
USD/MXN18.68-0.23%
EUR/MXN21.01+0.04%
WTI Crude101.24-1.97%

Market Snapshot

AssetLevelChange
IPC Bolsa69,879.62-0.01%
USD/MXN18.68-0.23%
EUR/MXN21.01+0.04%
WTI Crude101.24-1.97%
Silver54.12+0.75%
Gold4,032.20+0.61%
Brent Crude110.08-5.69%
Bitcoin80,200.44+0.22%
Mexico 10Y Govt Yield9.25%-10 bp

Prior Economic Events

Data Prior Cons Actual
No events available
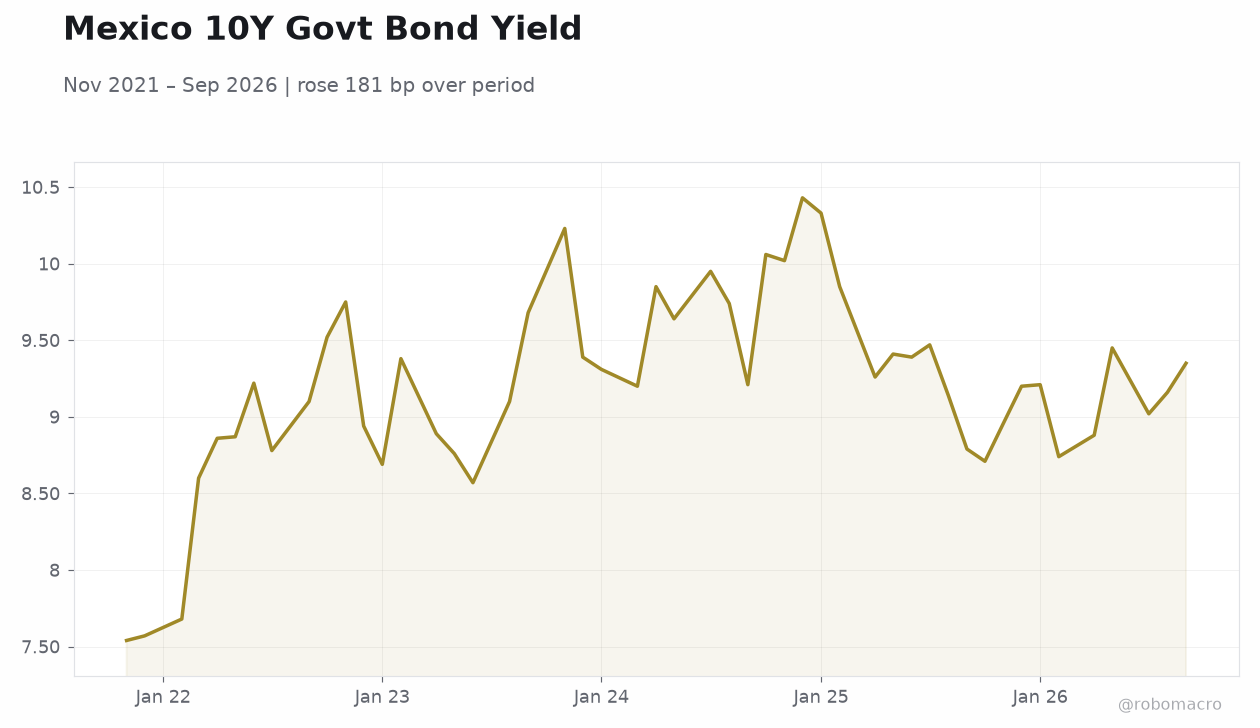
Mexico 10Y Govt Bond YieldMexico 10Y Govt Bond Yield | Type: macro_line | Percent: 9.35 (2026-09-01) | Range: 7.54–10.43 | Trend(5pt): 7.54,8.69,9.64,9.47,9.35

Today's Economic Events

Data Prior Cons Time
Tuesday (2026-10-27)
Trade Balance605m-08:00
Friday (2026-10-30)
GDP Growth Quarter-over-Quarter Preliminary1.40-08:00
GDP Growth Year-over-Year Preliminary2.10-08:00
  • USD/MXN fell 0.23% to 18.68 while the 10-year government yield declined 10 bp to 9.25%.
  • IPC Bolsa closed essentially flat at 69,879.62 amid thin trading and no domestic data releases.
  • Markets await Mexico’s Trade Balance print tomorrow and preliminary GDP figures due Friday.

Yesterday's Recap

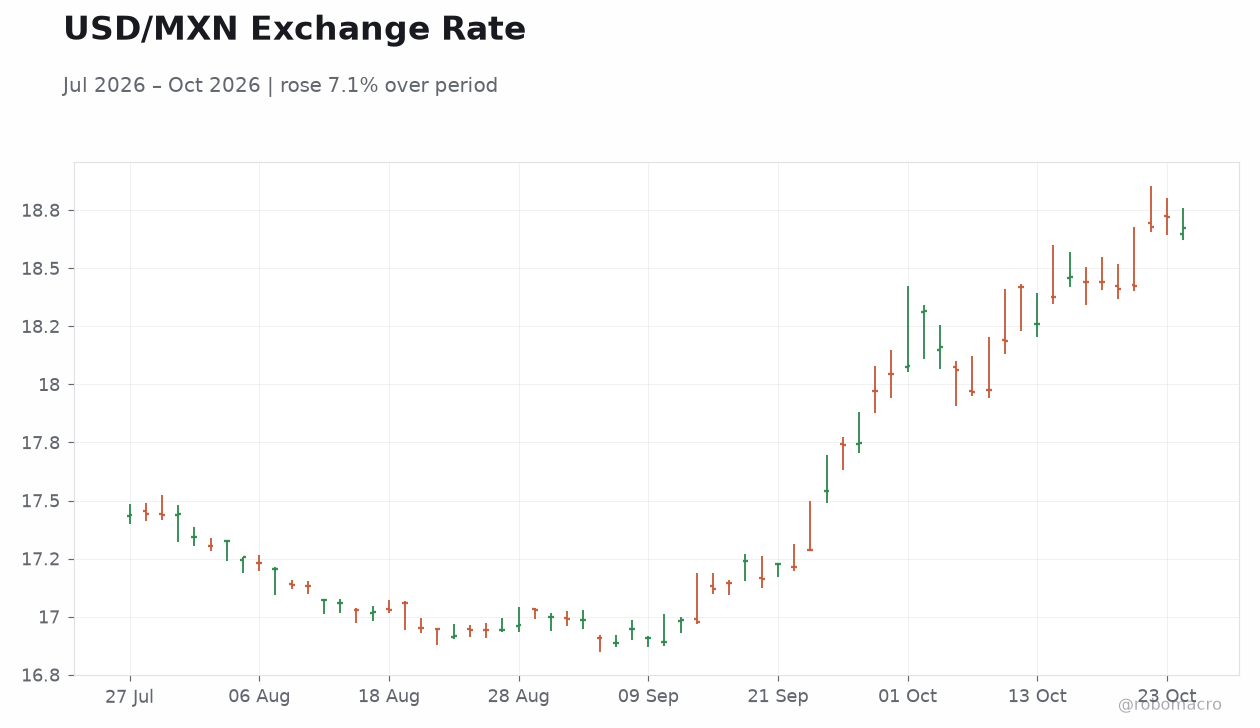
Mexican markets recorded modest moves on 25 October with no scheduled economic releases. The peso strengthened against the dollar as USD/MXN declined 0.23 percent to 18.68, supported by steady risk sentiment and lower U.S. Treasury yields.

The benchmark 10-year government bond yield eased 10 basis points to 9.25 percent, extending the recent decline in local rates. Equity markets showed little direction, with the IPC Bolsa index finishing virtually unchanged at 69,879.62. Brent crude prices dropped sharply, weighing on energy-related names, while gold and silver posted modest gains that offered limited support to mining stocks.

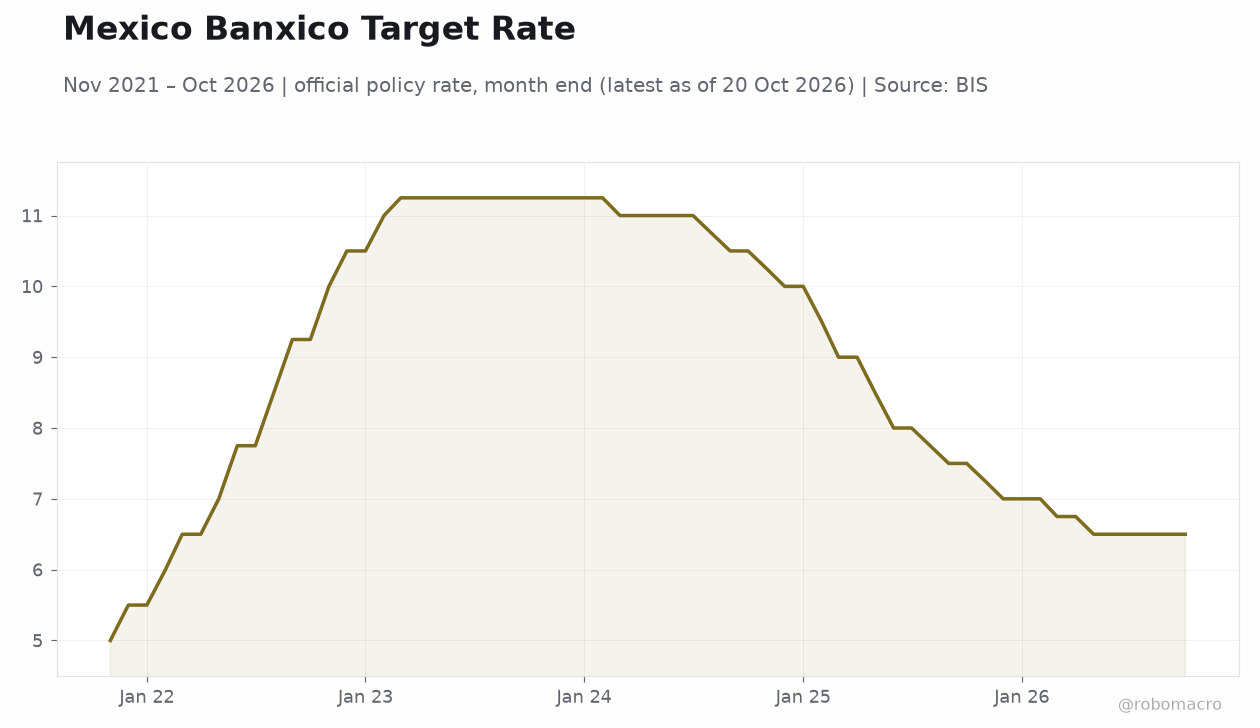
Overall volume remained light as participants positioned ahead of the week’s trade and growth data. The absence of fresh inflation or activity prints left Banxico’s 6.50 percent policy rate and the 3.45 percent September CPI print as the dominant reference points for pricing.

The Day Ahead

Attention turns to the Trade Balance release scheduled for 27 October at 8:00 a.m. ET, which will provide the first post-September reading on export momentum. Preliminary third-quarter GDP figures follow on 30 October, covering both quarter-over-quarter and year-over-year growth and offering an early gauge of domestic demand resilience.

No monetary-policy events or inflation prints are due this week, keeping the focus squarely on external trade flows. Analysts will watch whether the peso’s recent firmness persists into the data or reverses on any surprise widening of the trade gap. Broader market reaction will also hinge on concurrent U.S.

data and any fresh signals on U.S.-Mexico trade policy.

Other Economic Notes

Nearshoring investment continues to underpin Mexico’s medium-term growth outlook despite softer global manufacturing. Supply-chain shifts have sustained foreign direct investment in northern industrial states, supporting both exports and formal employment. USMCA compliance remains central to maintaining tariff-free access to the U.S.

↓ p.2
Page 1

Mexico Macro Daily(Beta Mode)

October 26, 2026 robomacro.com
Mexico Banxico Target Rate Mexico Banxico Target Rate | Nov 2021 – Oct 2026 | official policy rate, month end (latest as of 20 Oct 2026) | Source: BIS | Type: macro_line | Banxico target rate (%): 6.5 (2026-10-01) | Range: 5–11.25 | Trend(5pt): 5,11,11,7.75,6.5
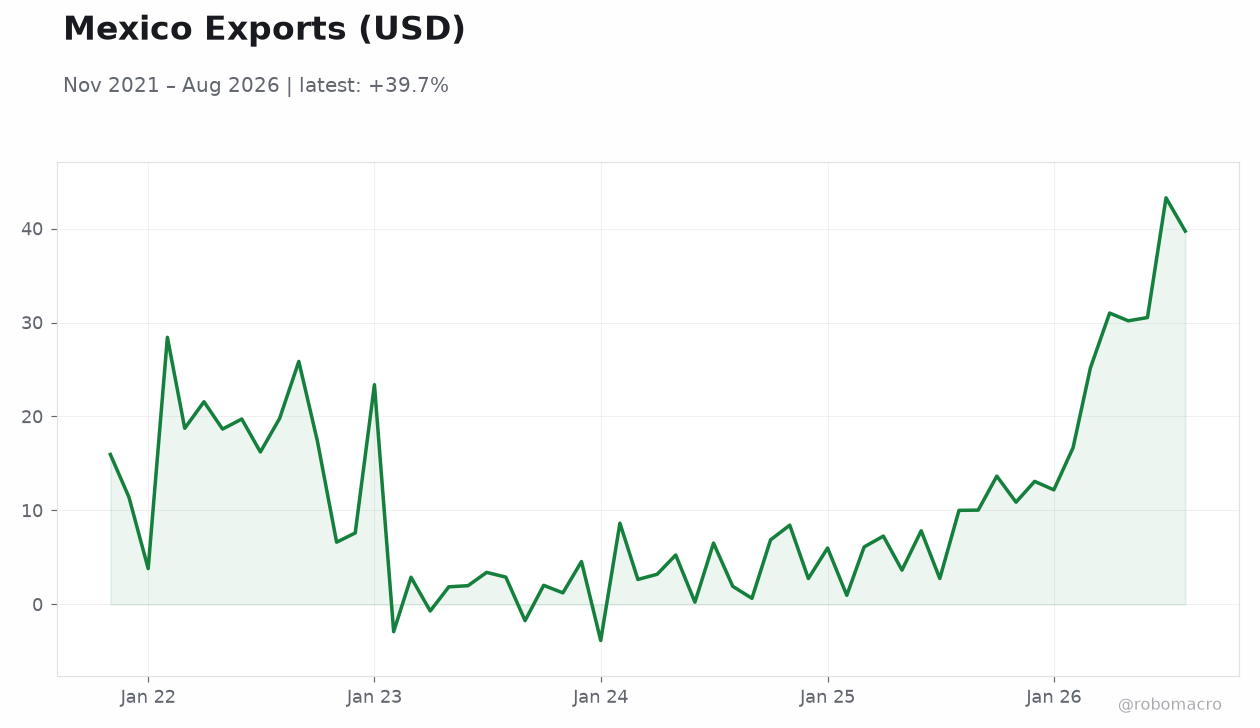
Mexico Exports (USD) Mexico Exports (USD) | Type: macro_line | USD Million: 39.73 (2026-08-01) | Range: -3.843–43.27 | Trend(6pt): 15.96,23.38,2.654,3.644,43.27,39.73
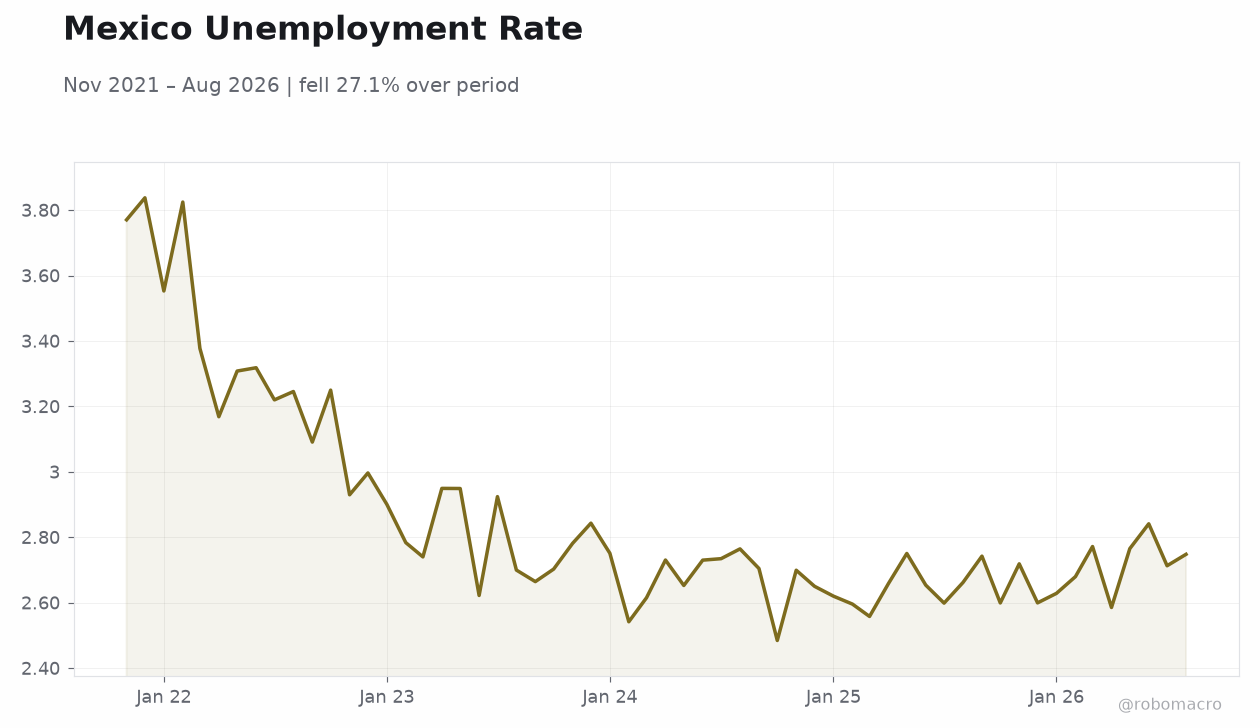
Mexico Unemployment Rate Mexico Unemployment Rate | Type: macro_line | Percent: 2.748 (2026-08-01) | Range: 2.485–3.837 | Trend(6pt): 3.77,2.901,2.615,2.75,2.713,2.748
USD/MXN Exchange Rate USD/MXN Exchange Rate | Type: market_hloc | MXN per USD: 18.67 (2026-10-26) | Range: 16.89–18.72 | Trend(6pt): 17.44,17.03,16.91,18.08,18.72,18.67

Other Economic Notes (continued)

market, with ongoing reviews of rules-of-origin requirements for autos and electronics. Domestic demand has held up better than expected, helped by remittance inflows and a still-positive output gap. Policymakers continue to balance these structural tailwinds against the need to keep inflation expectations anchored near the 3 percent target.

Global Macro News

Global risk sentiment stayed constructive, aiding emerging-market currencies including the peso. Discussions around potential U.S. tariff adjustments under the next administration have prompted Mexican officials to emphasize supply-chain integration and USMCA commitments.

Brazil’s post-election policy path and China’s trade data releases are being monitored for spillovers into commodity prices that affect Mexican exports. Central banks in advanced economies have signaled a slower pace of easing, keeping external financing conditions tighter than earlier in the year. Oil-price volatility, evident in the sharp drop in Brent, adds uncertainty to Mexico’s fiscal accounts and Pemex-related flows.

Regional peers such as the Colombian peso and Chilean peso moved in tandem with broader dollar weakness, limiting any outsized moves in USD/MXN.

Sponsored by Arbitrage Search
Page 2

Mexico Macro Daily(Beta Mode)

October 26, 2026 robomacro.com

Continuation

Banxico Watch

Banxico has maintained the policy rate at 6.50 percent since the October decision, citing the need for further evidence that inflation will converge sustainably to the 3 percent target. The latest available CPI reading of 3.45 percent year-over-year shows core pressures have moderated but remain above the midpoint of the tolerance band. Recent communications have stressed data dependence and avoided signaling an imminent cut, with board members highlighting risks from wage dynamics and external demand.

Minutes from the prior meeting underscored a cautious approach, noting that premature easing could unanchor expectations amid still-elevated service prices. Markets now price a first cut no earlier than the first quarter of 2027, consistent with the bank’s forward guidance that policy will remain restrictive until inflation shows clearer deceleration. Any surprise in tomorrow’s trade data or Friday’s GDP print could shift the timing of the first move, but the committee has signaled it will prioritize the inflation path over growth concerns.

Sponsored by Arbitrage Search
Page 3