Mexico Macro Daily(Beta Mode)
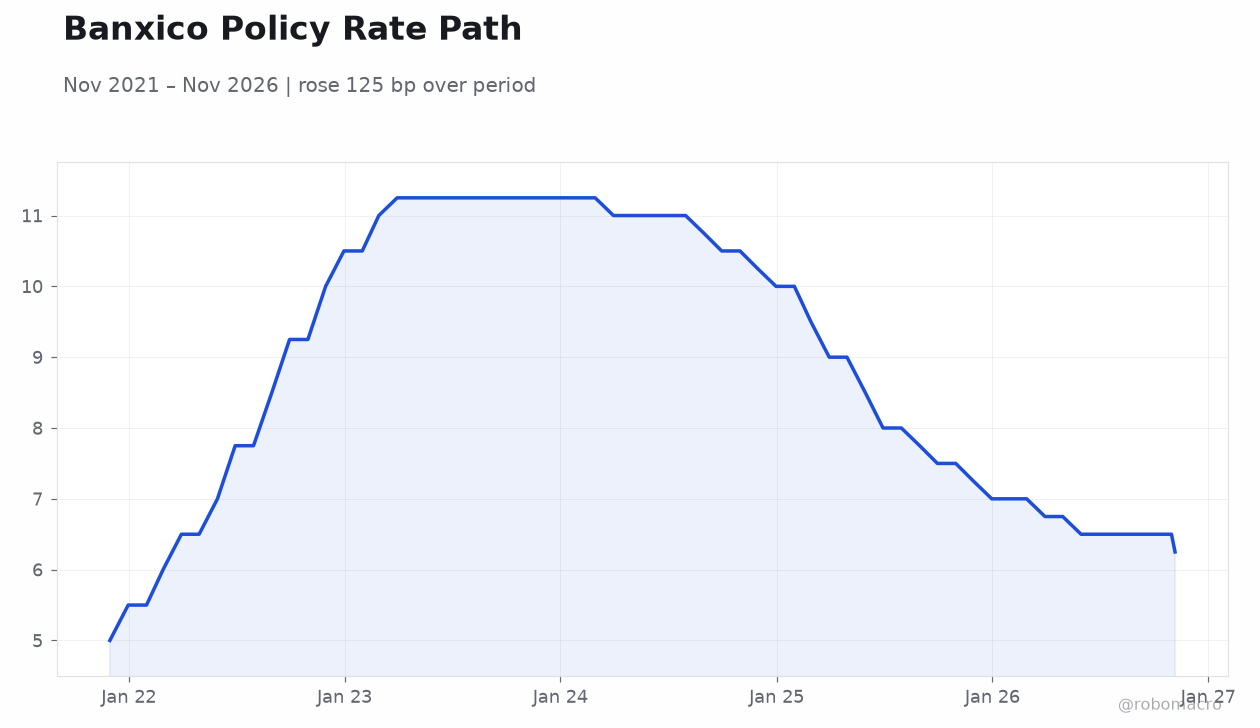
Banxico Cuts to 6.25% as Confidence Stalls
Market Snapshot
| Asset | Level | Change |
|---|---|---|
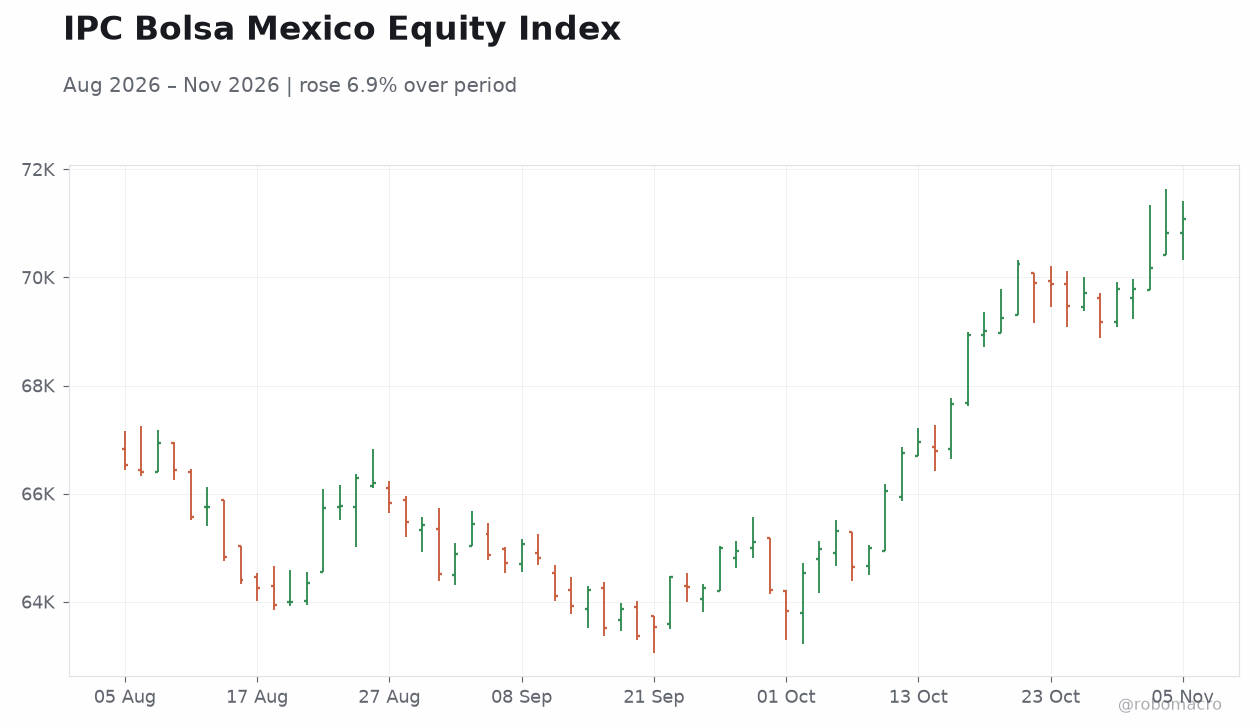
| IPC Bolsa | 71,087.56 | +0.38% |
| USD/MXN | 18.71 | +0.54% |
| EUR/MXN | 20.91 | +0.01% |
| WTI Crude | 90.98 | +0.51% |
| Silver | 52.13 | -0.20% |
| Gold | 4,077.10 | -0.88% |
| Brent Crude | 98.78 | +0.50% |
| Bitcoin | 75,950.16 | +0.01% |
| Mexico 10Y Govt Yield | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
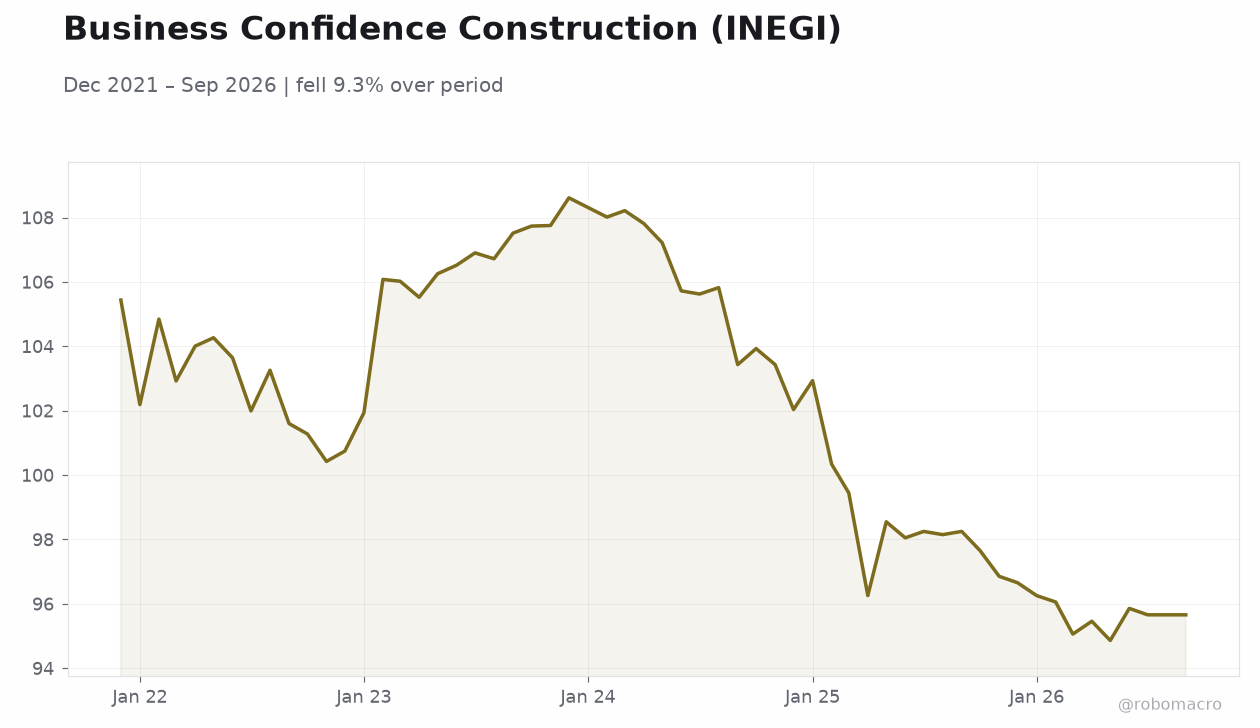
| Business Confidence Index | 48.10 | - | 48.40 |
| Consumer Confidence Index | 45.10 | - | 45 |
| Central Bank Interest Rate Decision | 6.50 | 6.50 | 6.25 |
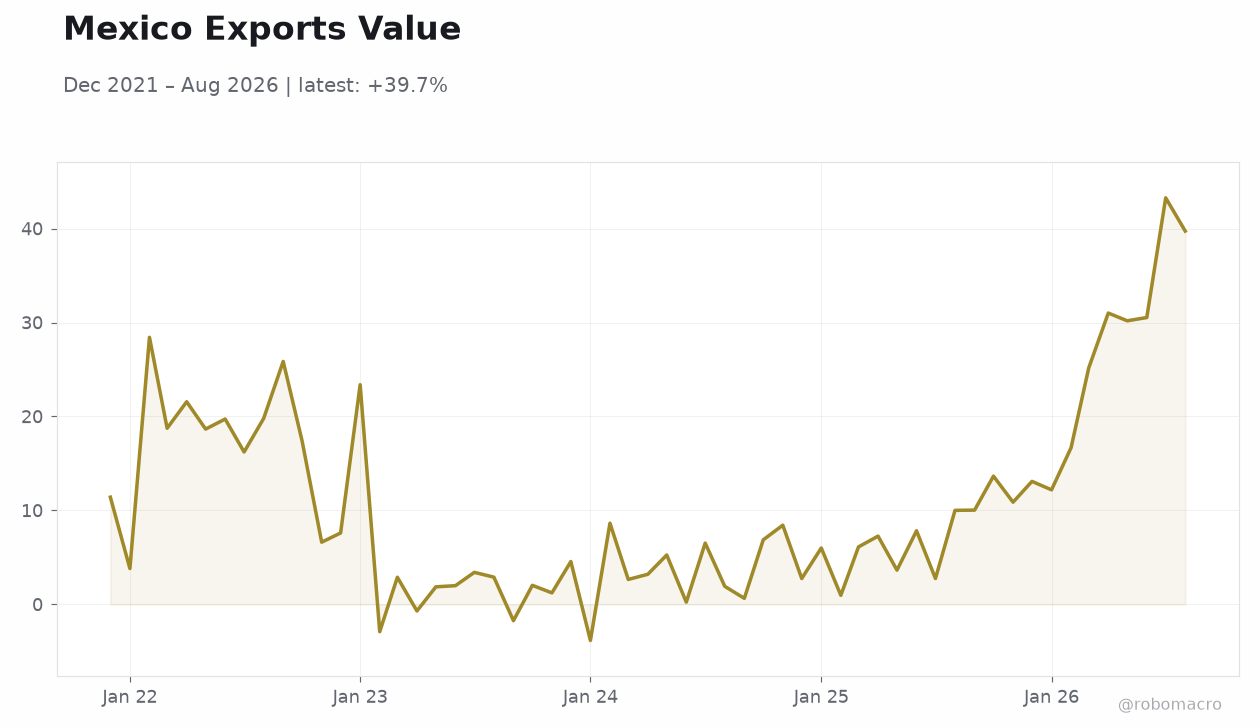 Mexico Exports Value | Type: macro_line | Exports (USD): 39.73 (2026-08-01) | Range: -3.843–43.27 | Trend(5pt): 11.41,-2.909,3.203,7.832,39.73
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- Banxico lowered its policy rate to 6.25% from 6.5% on November 5, a cut not anticipated by consensus
- Consumer confidence slipped to 45.0 from 45.1 while business confidence edged up to 48.4 from 48.1
- USD/MXN rose 0.54% to 18.71 as the peso absorbed the surprise easing; IPC Bolsa gained 0.38%
Yesterday's Recap
Banxico delivered a surprise 25bp cut on November 5, taking the policy rate to 6.25% against consensus expectations of a hold at 6.5%. The move came alongside a soft consumer confidence print of 45.0, down marginally from 45.1, signaling households remain cautious. Business confidence ticked up to 48.4 from 48.1, though it remains below the 50 threshold separating optimism from pessimism.
Markets reacted with the peso weakening 0.54% to 18.71 per dollar, while the IPC Bolsa rose 0.38% to 71,087.56 as lower rates supported equity valuations. The 10-year government yield was not reported in the latest data set. The combination of easing monetary policy into softening sentiment suggests Banxico is prioritizing growth support over inflation vigilance.
The Day Ahead
No Mexican economic releases are scheduled for November 6, leaving markets to digest the prior session's surprise rate cut. Attention turns to peso dynamics, with USD/MXN likely to test the 18.75-18.80 range as carry-trade positioning adjusts to a lower policy rate. Local rates markets will reprice the front end of the curve following the unexpected easing.
Investors will also monitor commentary from Banxico officials for clarity on the pace of further cuts. With no domestic catalysts, external drivers—particularly US data and risk sentiment—will dominate the peso's direction.
Other Economic Notes
The surprise cut signals Banxico's growing comfort with the disinflation trajectory, with CPI at 3.45% year-on-year as of September 30, comfortably within the central bank's target range. Business confidence at 48.4 remains in contractionary territory, reflecting persistent uncertainty around investment conditions and nearshoring execution. The divergence between business optimism and consumer caution underscores uneven recovery dynamics.
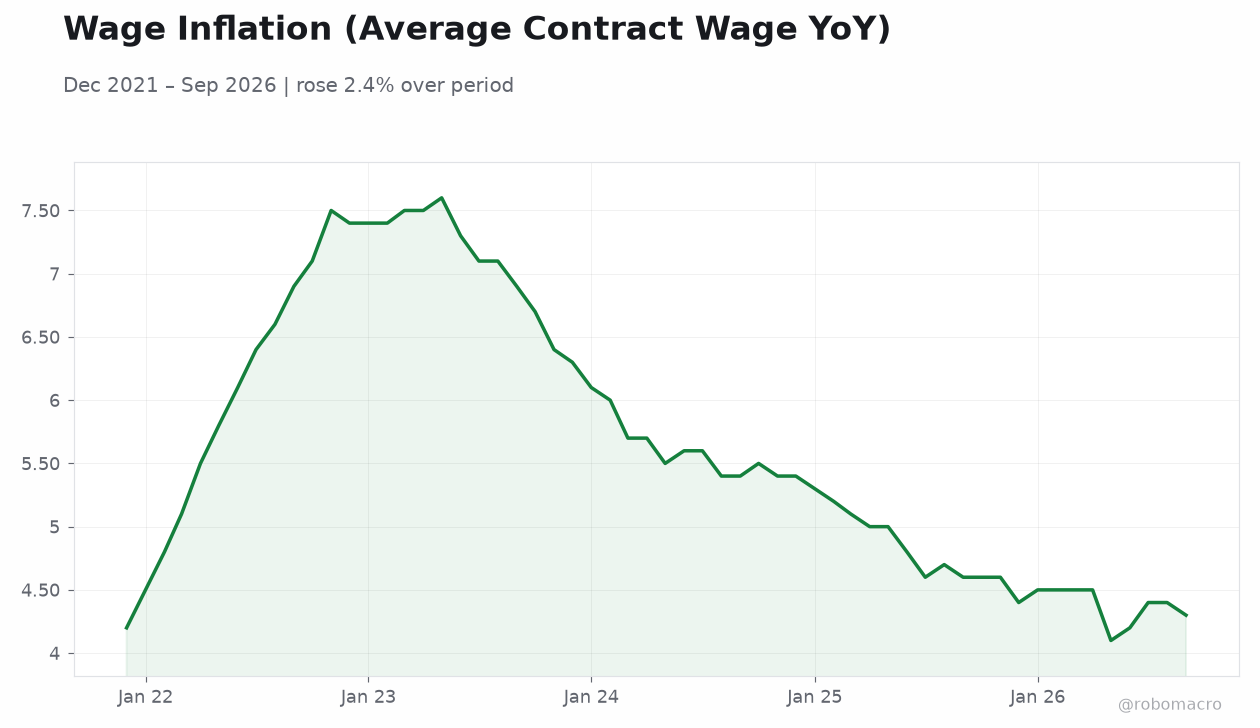
Mexico's manufacturing sector continues to benefit from US-Mexico trade integration under USMCA, though policy uncertainty north of the border bears watching. The health-sector wage dispute, with an 8% deal imposed on IMSS workers, adds a fiscal cost consideration for the government's spending trajectory.