RoboMacro ResearchAlso todaySee the Commodities Daily

Mexico Macro Daily(Beta Mode)

November 10, 2026 robomacro.com

Mexico Inflation Overshoots as Banxico Cut Stays in Play

0.65 Inflation Rate3.75 Inflation Rate
IPC Bolsa71,855.64+0.65%
USD/MXN18.49-0.77%
EUR/MXN20.75-0.12%
WTI Crude85.50-1.55%

Market Snapshot

AssetLevelChange
IPC Bolsa71,855.64+0.65%
USD/MXN18.49-0.77%
EUR/MXN20.75-0.12%
WTI Crude85.50-1.55%
Silver52.28-0.54%
Gold4,077.90-0.89%
Brent Crude90.71-2.01%
Bitcoin74,334.00-1.18%
Mexico 10Y Govt Yield--

Prior Economic Events

Data Prior Cons Actual
Inflation Rate Month-over-Month0.420.550.65
Inflation Rate Year-over-Year3.453.653.75
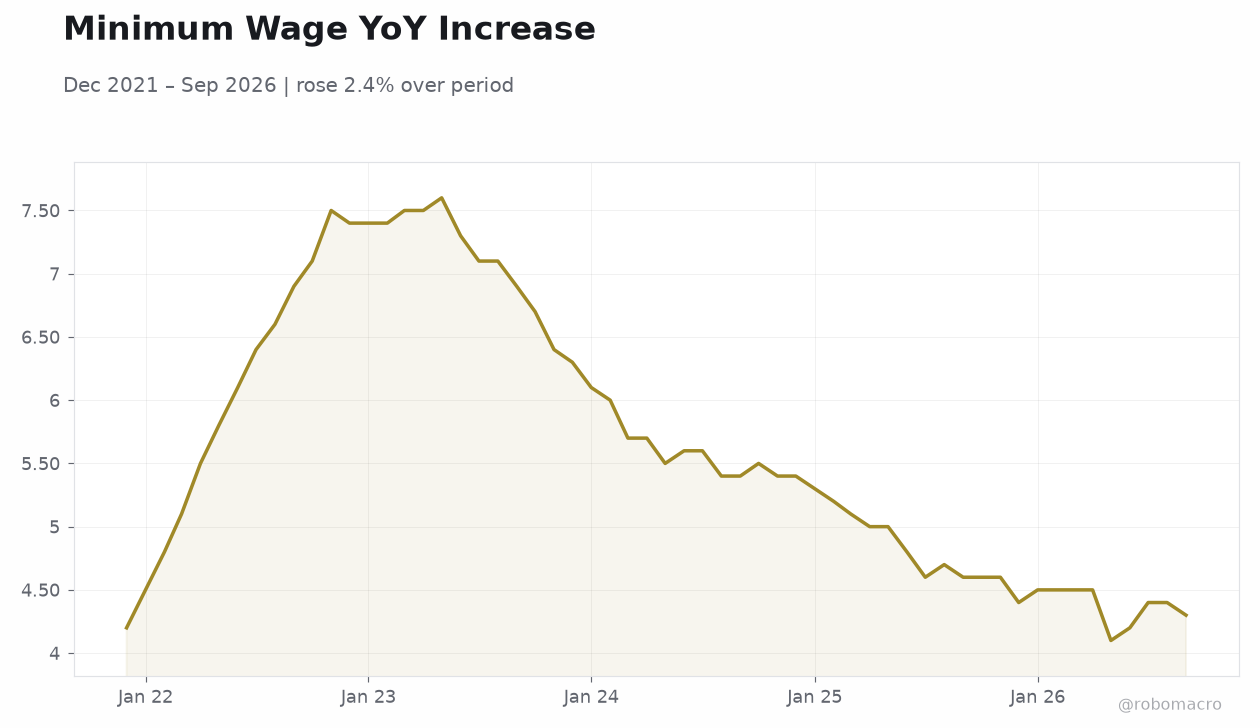
Minimum Wage YoY IncreaseMinimum Wage YoY Increase | Type: macro_line | Minimum Wage YoY Increase: 4.3 (2026-09-01) | Range: 4.1–7.6 | Trend(5pt): 4.2,7.4,5.7,4.8,4.3

Today's Economic Events

Data Prior Cons Time
No events available
  • Mexico November 9 CPI prints came in hot: +0.65% m/m and 3.75% y/y, both above consensus and prior readings
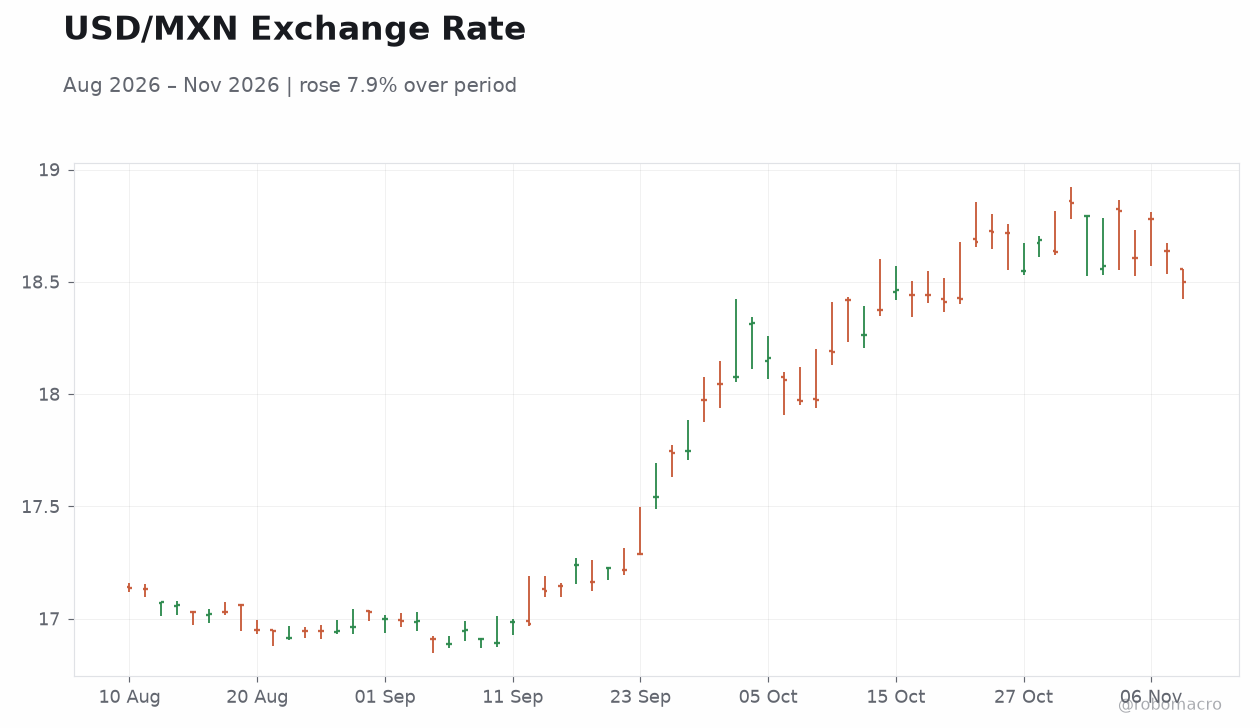
  • Peso firmed 0.77% to 18.49 despite the inflation overshoot, tracking broad USD softness
  • IPC Bolsa gained 0.65% to 71,855.64; Banxico's 6.25% policy rate remains the market's anchor ahead of the December 17 decision

Yesterday's Recap

Mexico's November 9 inflation releases delivered an unambiguous upside surprise. Month-over-month CPI printed at 0.65%, above the 0.55% consensus and the prior 0.42%, while year-over-year inflation accelerated to 3.75% versus a 3.65% consensus and 3.45% previously. The combination signals that price pressures are re-accelerating rather than merely stabilizing, and the y/y print now sits above the upper edge of Banxico's tolerance band.

Despite the hot inflation data, the peso strengthened 0.77% to 18.49 per dollar, a move consistent with broad USD softness rather than any Mexico-specific catalyst. The IPC Bolsa rose 0.65% to 71,855.64, suggesting equity investors are looking through the CPI overshoot toward the growth and rate trajectory. EUR/MXN slipped 0.12% to 20.75, confirming the peso's firming was dollar-driven rather than euro-specific.

The 10-year government yield was not quoted in the data feed, leaving the curve's reaction to the inflation print unconfirmed.

The Day Ahead

The Mexico calendar is empty for November 10, with no scheduled data releases and no events carried over from tomorrow. With no domestic prints to digest, the peso and IPC Bolsa will trade on external drivers — chiefly US dollar direction, oil prices, and global risk appetite. WTI's 1.55% decline to $85.50 and Brent's 2.01% drop to $90.71 are the most relevant cross-asset inputs for Mexican markets today, given the fiscal sensitivity to crude revenues.

Traders will also begin positioning ahead of the December 17 Banxico decision, with the November 9 CPI overshoot likely to sharpen the debate over whether the easing cycle can continue at its current pace. Absent fresh catalysts, expect range-bound trading in USD/MXN around the 18.50 handle.

Other Economic Notes

The November 9 inflation overshoot complicates the narrative that Mexico's disinflation path is secure. A 3.75% y/y print is materially above where consensus expected the trajectory to sit, and the 0.65% monthly figure points to sticky services and food components rather than a one-off. ↓ p.2
Page 1

Mexico Macro Daily(Beta Mode)

November 10, 2026 robomacro.com
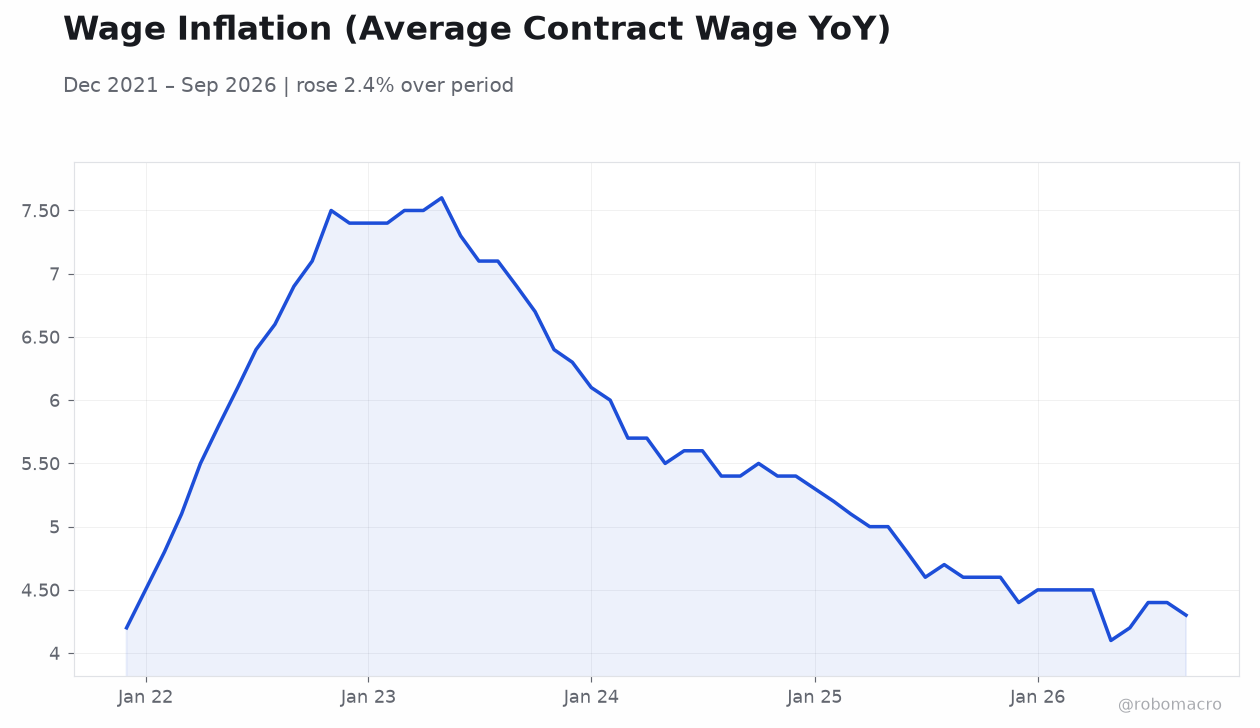
Wage Inflation (Average Contract Wage YoY) Wage Inflation (Average Contract Wage YoY) | Type: macro_line | Wage Inflation (Average Contract Wage YoY): 4.3 (2026-09-01) | Range: 4.1–7.6 | Trend(5pt): 4.2,7.4,5.7,4.8,4.3
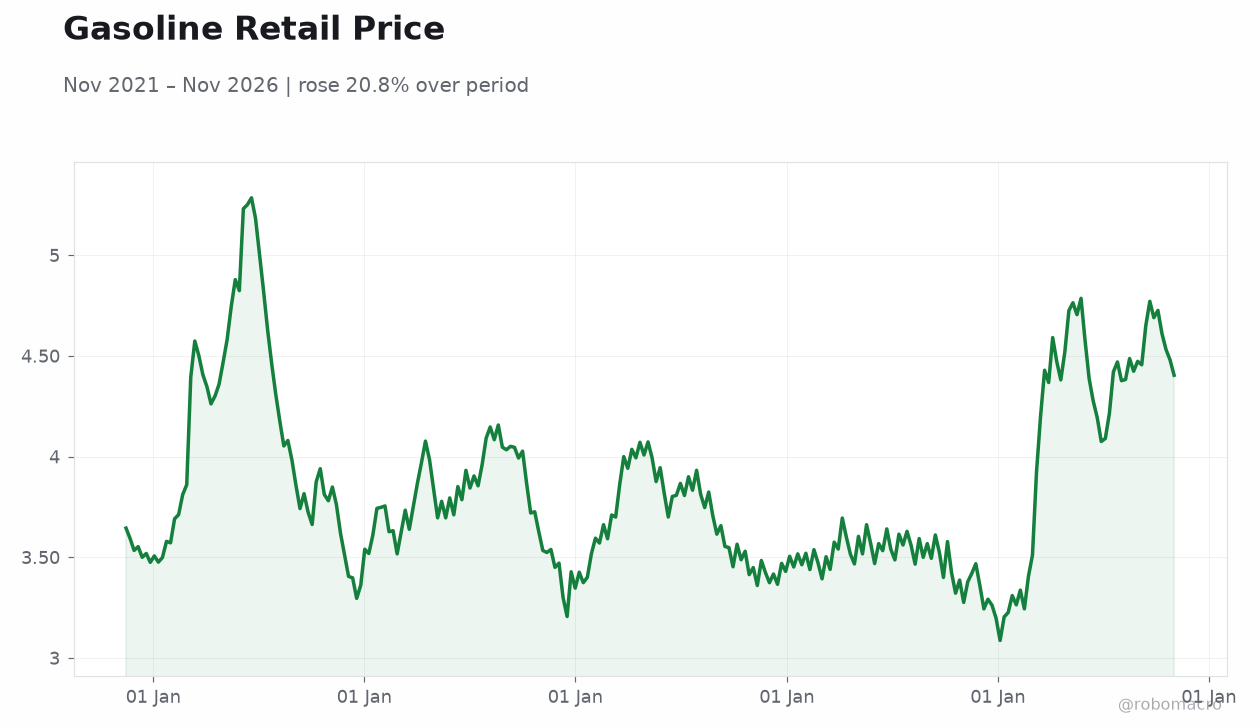
Gasoline Retail Price Gasoline Retail Price | Type: macro_line | Gasoline Retail Price: 4.404 (2026-11-02) | Range: 3.087–5.285 | Trend(5pt): 3.645,3.627,3.994,3.466,4.404
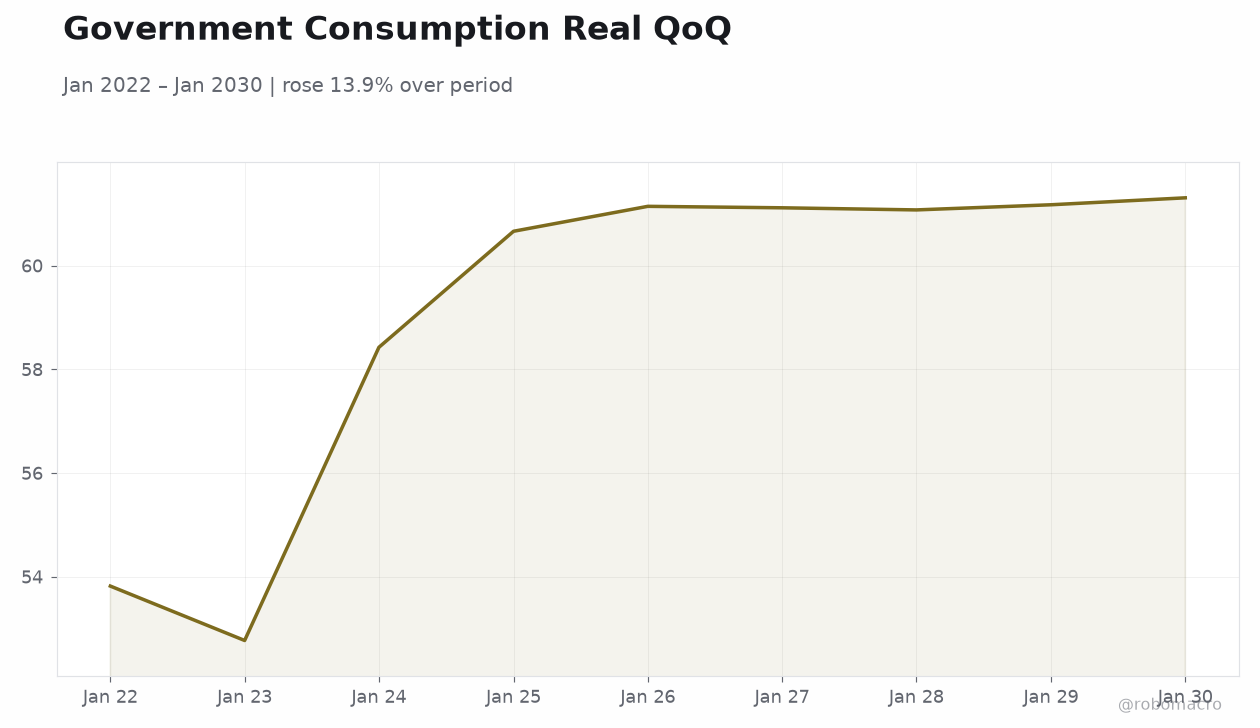
Government Consumption Real QoQ Government Consumption Real QoQ | Type: macro_line | Government Consumption Real QoQ: 61.31 (2030-01-01) | Range: 52.77–61.31 | Trend(5pt): 53.82,58.43,61.14,61.08,61.31
USD/MXN Exchange Rate USD/MXN Exchange Rate | Type: market_hloc | USD/MXN: 18.5 (2026-11-10) | Range: 16.89–18.85 | Trend(6pt): 17.14,17,17.29,18.46,18.78,18.5

Other Economic Notes (continued)

For the IPC Bolsa, the tension is between a slower easing path — which supports bank margins and peso assets — and the growth drag from a 6.25% policy rate that remains restrictive in real terms. Nearshoring flows remain the structural support for Mexican equities and the peso, but the immediate macro signal is that the disinflation story has hit a speed bump. The absence of a quoted 10-year yield leaves a gap in the market's read on term premium, though the peso's firm tone suggests investors are not yet pricing a hawkish pivot.

Global Macro News

China's trade surplus surged past $1 trillion in October, with exports continuing to climb despite economic gloom and global trade tensions — a dynamic that keeps US-Mexico trade policy in focus as Washington weighs tariff responses. China also extended its US trade truce by two months, reducing near-term tariff escalation risk but leaving the structural surplus unresolved. Crude sold off sharply, with WTI down 1.55% to $85.50 and Brent down 2.01% to $90.71, a headwind for Mexico's fiscal revenues though a tailwind for domestic fuel costs.

Gold fell 0.89% to $4,077.90 and silver slipped 0.54% to $52.28, signaling a modest risk-on tilt rather than a flight to safety. Bitcoin dropped 1.18% to $74,334, consistent with the broader cooling in speculative assets. In Europe, the race to succeed Lagarde at the ECB is underway, with two contenders emerging as the continent weighs who will steer interest rates — a reminder that global monetary policy leadership remains in flux.

Norway's households are saving at the strongest rate in three decades on higher rates, underscoring how restrictive policy is reshaping consumer behavior across developed markets.

Sponsored by Arbitrage Search
Page 2

Mexico Macro Daily(Beta Mode)

November 10, 2026 robomacro.com

Continuation

Banxico Watch

Banxico cut its policy rate by 25 basis points to 6.25% at the November 5 decision, effective November 6, continuing the easing cycle from 6.50%. The next scheduled decision is December 17, and the November 9 CPI overshoot — 3.75% y/y versus 3.65% consensus — lands squarely in the window between meetings, giving the committee a fresh data point that argues against accelerating the pace of cuts. The committee voted to cut at the November 5 meeting; the exact vote split was not disclosed in the available data.

With inflation now above the upper bound of the tolerance band, the December 17 decision becomes a genuine test of the easing bias: a hold would signal the committee is prioritizing credibility, while another 25bp cut would signal it views the overshoot as transitory. For markets, the 6.25% rate remains the anchor for peso carry and short-end pricing, and any shift in forward guidance on December 17 will be the dominant driver for USD/MXN into year-end.

Sponsored by Arbitrage Search
Page 3