Mexico Macro Daily(Beta Mode)
Mexico Inflation Overshoots as Banxico Cut Stays in Play
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| IPC Bolsa | 71,893.88 | +0.05% |
| USD/MXN | 18.61 | +0.42% |
| EUR/MXN | 20.72 | -0.35% |
| WTI Crude | 86.67 | +0.73% |
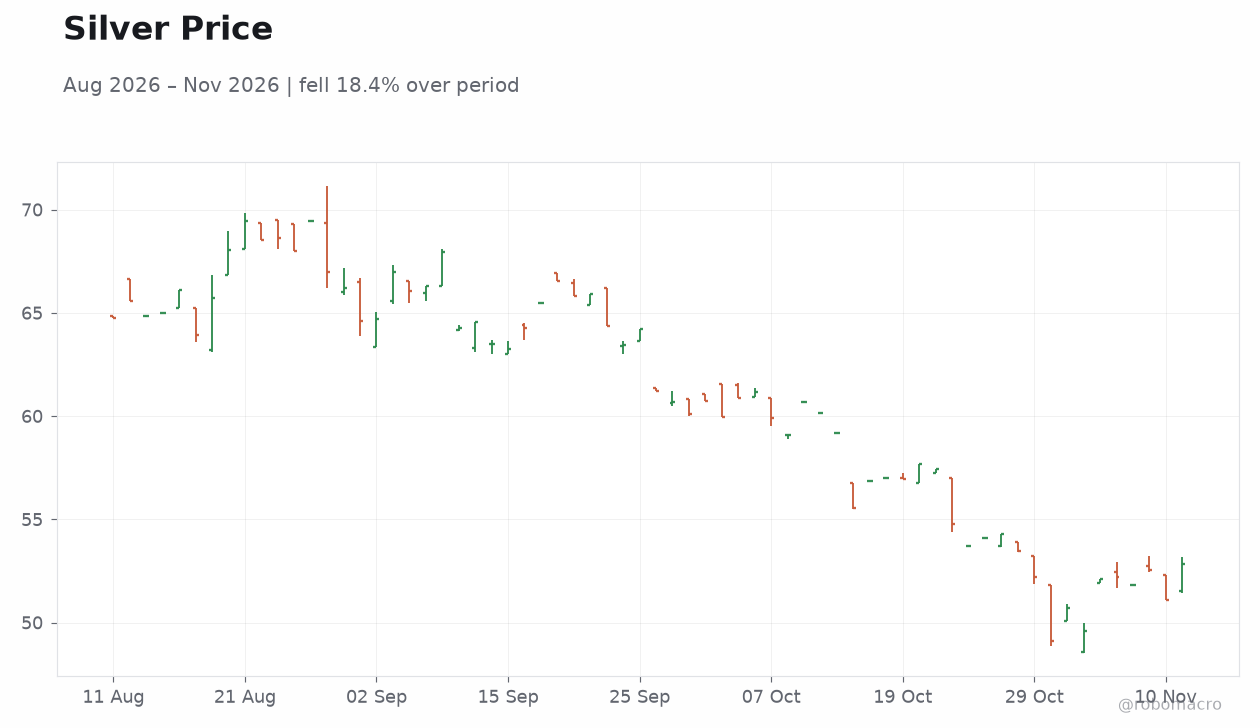
| Silver | 52.85 | +3.43% |
| Gold | 4,055.70 | +0.63% |
| Brent Crude | 92.73 | +1.36% |
| Bitcoin | 73,859.91 | +0.19% |
| Mexico 10Y Govt Yield | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| Inflation Rate Month-over-Month | 0.42 | 0.55 | 0.65 |
| Inflation Rate Year-over-Year | 3.45 | 3.65 | 3.75 |
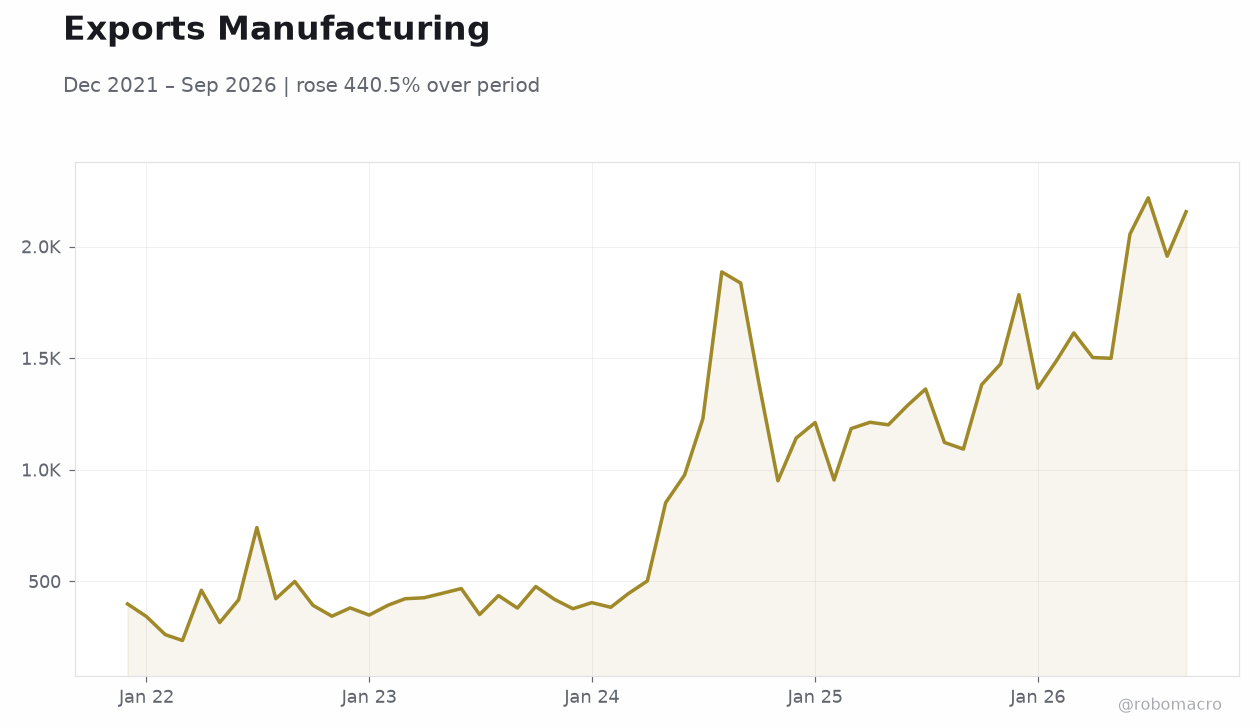 Exports Manufacturing | Type: macro_line | Exports Manufacturing: 2156 (2026-09-01) | Range: 235.2–2218 | Trend(6pt): 398.9,393.2,502,1287,1957,2156
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- October headline inflation printed at 3.75% y/y and 0.65% m/m, both above consensus, complicating Banxico's easing path after its November 5 cut to 6.25%.
- USD/MXN rose 0.42% to 18.61, a cross-currency move rather than a peso-specific shock; IPC Bolsa edged up 0.05% to 71,893.88.
- Precious metals and crude rallied (silver +3.43%, Brent +1.36%), while Ternium flagged weak enforcement of Mexico's steel import tariffs.
Yesterday's Recap
Mexico's October inflation data came in hotter than expected, with headline CPI at 3.75% y/y versus a 3.65% consensus and 0.65% m/m against a 0.55% forecast, both accelerating from the prior 3.45% y/y and 0.42% m/m readings. The overshoot lands squarely on a central bank that just delivered a 25bp cut to 6.25% on November 5, and it raises questions about the pace of further easing into the December 17 meeting. The peso weakened modestly, with USD/MXN up 0.42% to 18.61, a move the briefing characterizes as largely a cross-currency story rather than idiosyncratic peso stress.
EUR/MXN slipped 0.35% to 20.72, consistent with broader dollar firmness. Equities were essentially flat, with the IPC Bolsa adding 0.05% to 71,893.88. Commodities were the day's standout: silver jumped 3.43% to $52.85, gold rose 0.63% to $4,055.70, and Brent climbed 1.36% to $92.73 with WTI up 0.73% to $86.67.
Mexico 10-year government yields were not quoted in the market feed.
The Day Ahead
The Mexico calendar is empty for November 11, with no scheduled domestic data releases and nothing queued for November 12 either. That leaves the peso and local rates to trade off the inflation overshoot and external risk sentiment rather than fresh Mexican catalysts. With the next Banxico decision not until December 17, the market's focus shifts to parsing the November 5 statement and any subsequent communication for signals on the easing trajectory.
Absent domestic prints, expect USD/MXN to track broad dollar moves and commodity-linked flows, particularly with oil and precious metals showing momentum. Local equity direction will likely hinge on US session tone and steel-tariff headlines.
Other Economic Notes
Ternium's commentary that Mexican steel sales are rising as import tariffs push customers toward domestic metal, but that enforcement remains weak, is a useful read on the limits of Mexico's trade-protection push. It suggests tariff policy is redirecting demand at the margin without fully sealing the market, a theme worth monitoring for industrial margins and pricing power. ↓ p.2