Mexico Macro Daily(Beta Mode)
Inflation Overshoot Tests Banxico's Easing Path
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| IPC Bolsa | 72,006.05 | +0.16% |
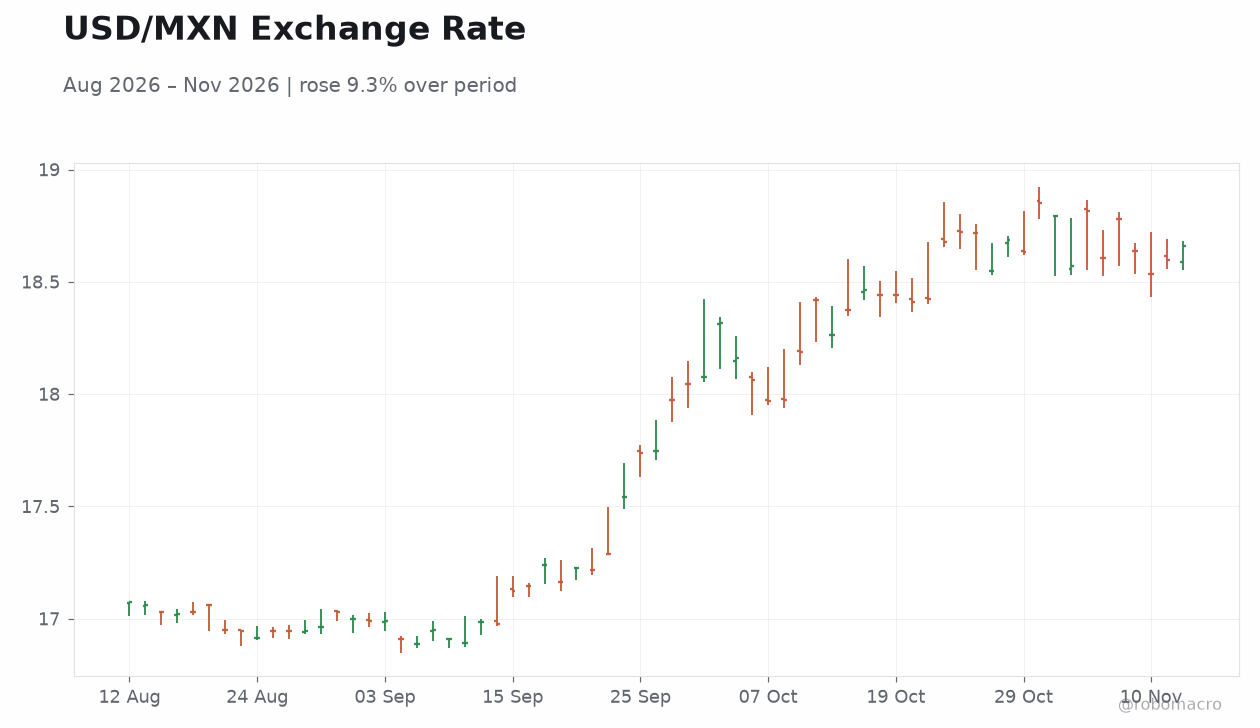
| USD/MXN | 18.67 | +0.36% |
| EUR/MXN | 20.69 | -0.46% |
| WTI Crude | 85.82 | -0.82% |
| Silver | 50.88 | -1.93% |
| Gold | 3,943.10 | -1.43% |
| Brent Crude | 92.17 | -0.64% |
| Bitcoin | 72,790.17 | -1.59% |
| Mexico 10Y Govt Yield | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| Inflation Rate Month-over-Month | 0.42 | 0.55 | 0.65 |
| Inflation Rate Year-over-Year | 3.45 | 3.65 | 3.75 |
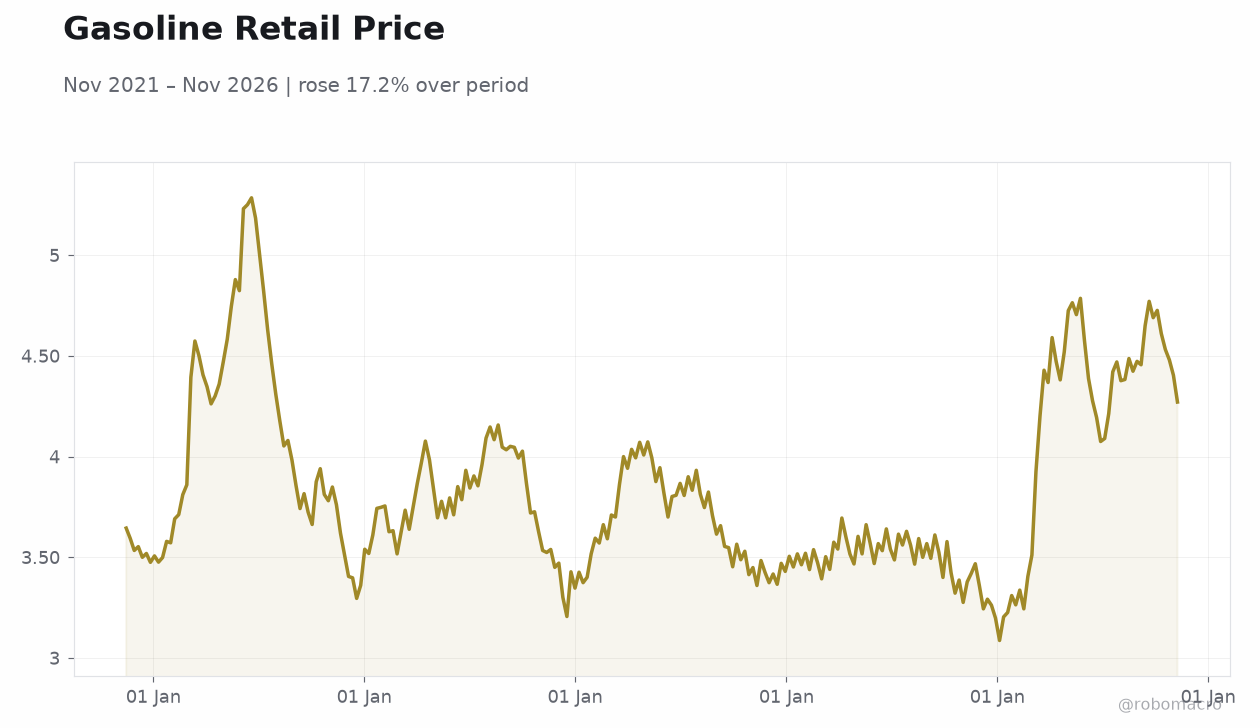 Gasoline Retail Price | Type: macro_line | Gasoline Retail Price: 4.271 (2026-11-09) | Range: 3.087–5.285 | Trend(5pt): 3.645,3.627,3.994,3.466,4.271
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- October CPI came in hot at 0.65% m/m and 3.75% y/y, both above consensus, complicating Banxico's post-cut messaging
- USD/MXN pushed to 18.67 (+0.36%) as the peso absorbed the inflation surprise and softer risk appetite
- IPC Bolsa edged up 0.16% to 72,006 despite the data miss, while oil and precious metals sold off
Yesterday's Recap
Mexico's October inflation prints landed above expectations, with month-over-month CPI at 0.65% versus a 0.55% consensus and year-over-year at 3.75% against a 3.65% forecast, both accelerating from the prior 0.42% and 3.45% readings. The overshoot keeps headline inflation above Banxico's 3% target and argues against rapid further easing after the November 5 cut. The peso weakened 0.36% to 18.67 per dollar, reflecting both the data surprise and a broader risk-off tone.
The IPC Bolsa managed a modest 0.16% gain to 72,006.05, showing domestic equities resilient despite the inflation miss. EUR/MXN slipped 0.46% to 20.69, with the euro softer against the peso than the dollar cross implied. Broader commodities were weak, with WTI down 0.82% to $85.82 and Brent off 0.64% to $92.17, while silver fell 1.93% and gold 1.43%, a move that typically signals firmer real yields and a less dovish rate outlook.
The Day Ahead
The calendar is empty for Mexico today and tomorrow, leaving markets to digest Monday's inflation surprise without fresh domestic data. With no scheduled releases, attention shifts to Banxico communication channels and the December 17 policy meeting, now the key event for rate direction. Traders will watch the peso for follow-through after the 18.67 print, particularly whether the inflation overshoot triggers sustained FX weakness.
Local rates markets will also parse whether the 3.75% headline shifts the implied path for the 6.25% policy rate. Absent domestic catalysts, Mexican assets will likely take their cue from US data and global risk sentiment.
Other Economic Notes
The inflation overshoot reinforces the tension between Banxico's easing bias and sticky price pressures, with services and core components likely driving the upside. Nearshoring flows remain a structural support for the peso and northern industrial corridors, though a stronger dollar complicates the investment calculus. US-Mexico trade relations under USMCA continue to anchor cross-border manufacturing, but political noise from Washington — including security and migration friction — bears watching.
Fiscal consolidation and Pemex's finances remain latent risks for sovereign spreads. ↓ p.2