Mexico Macro Daily(Beta Mode)
Peso Slides as Fed Tightening Bets Mount
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| IPC Bolsa | 69,154.17 | -1.75% |
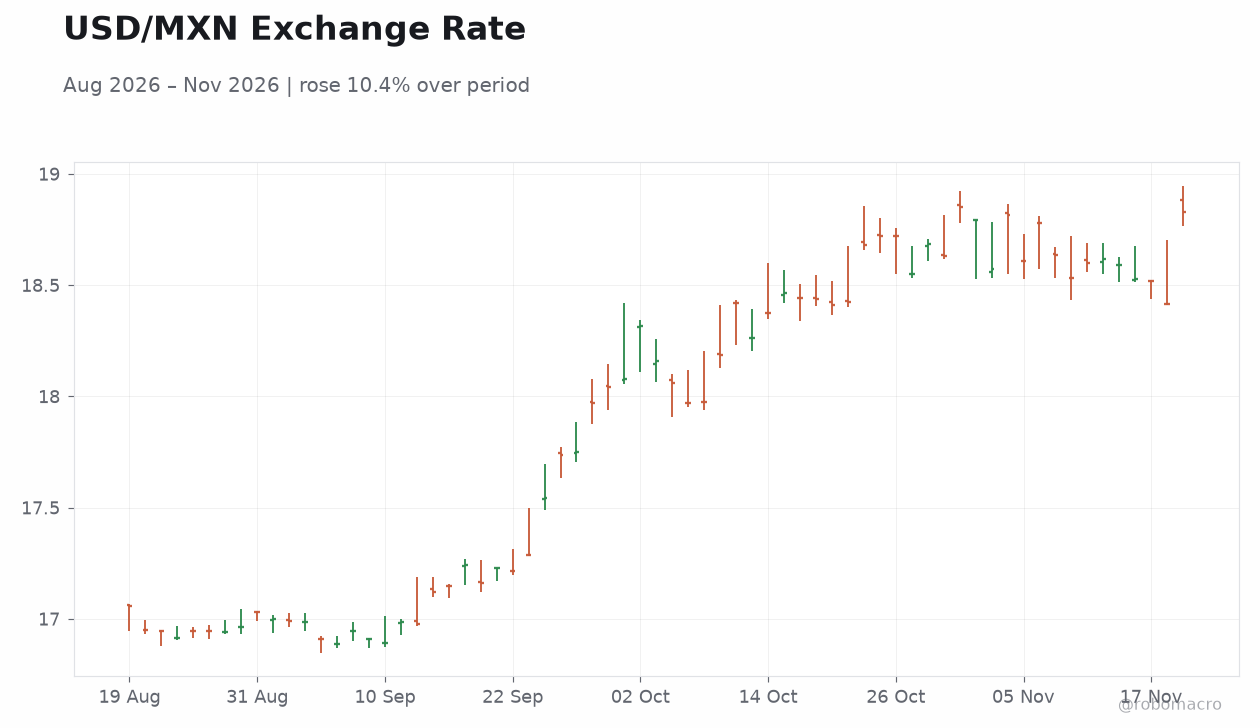
| USD/MXN | 18.82 | +2.18% |
| EUR/MXN | 20.69 | +2.21% |
| WTI Crude | 82.05 | -1.45% |
| Silver | 45.04 | +0.09% |
| Gold | 3,727.40 | -0.39% |
| Brent Crude | 88.99 | -3.22% |
| Bitcoin | 63,728.62 | +1.18% |
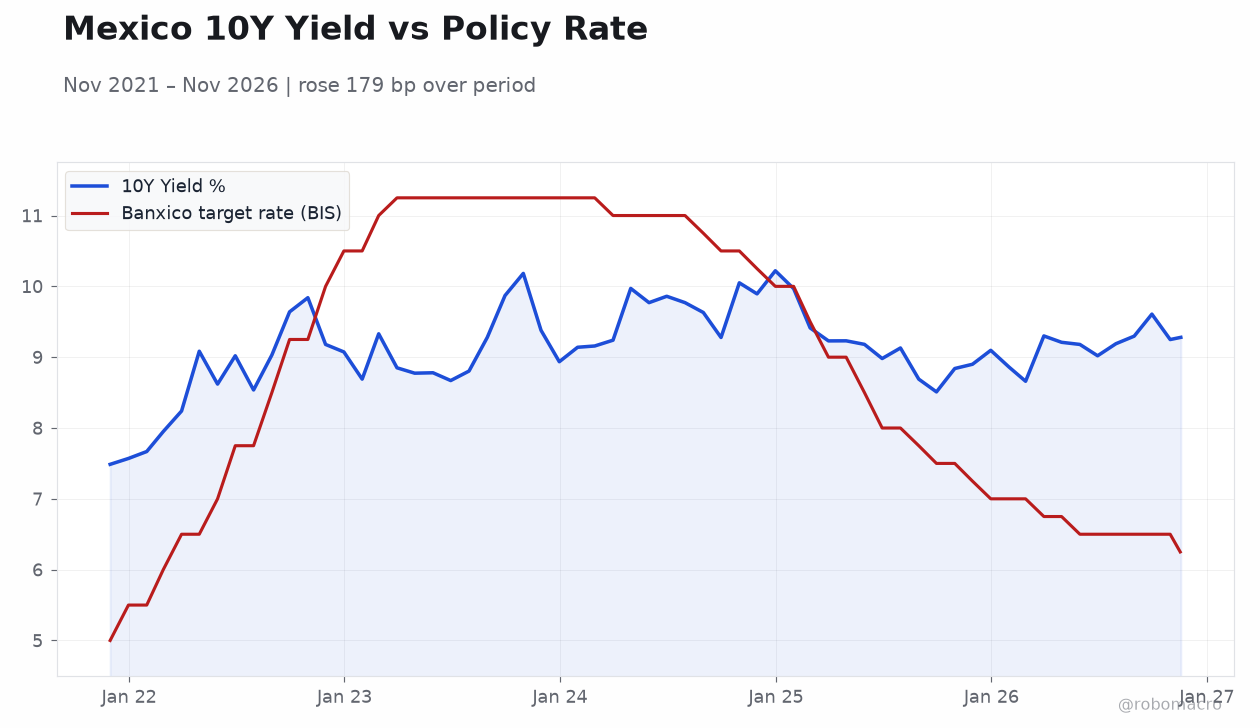
| Mexico 10Y Govt Yield | 9.28% | 0 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
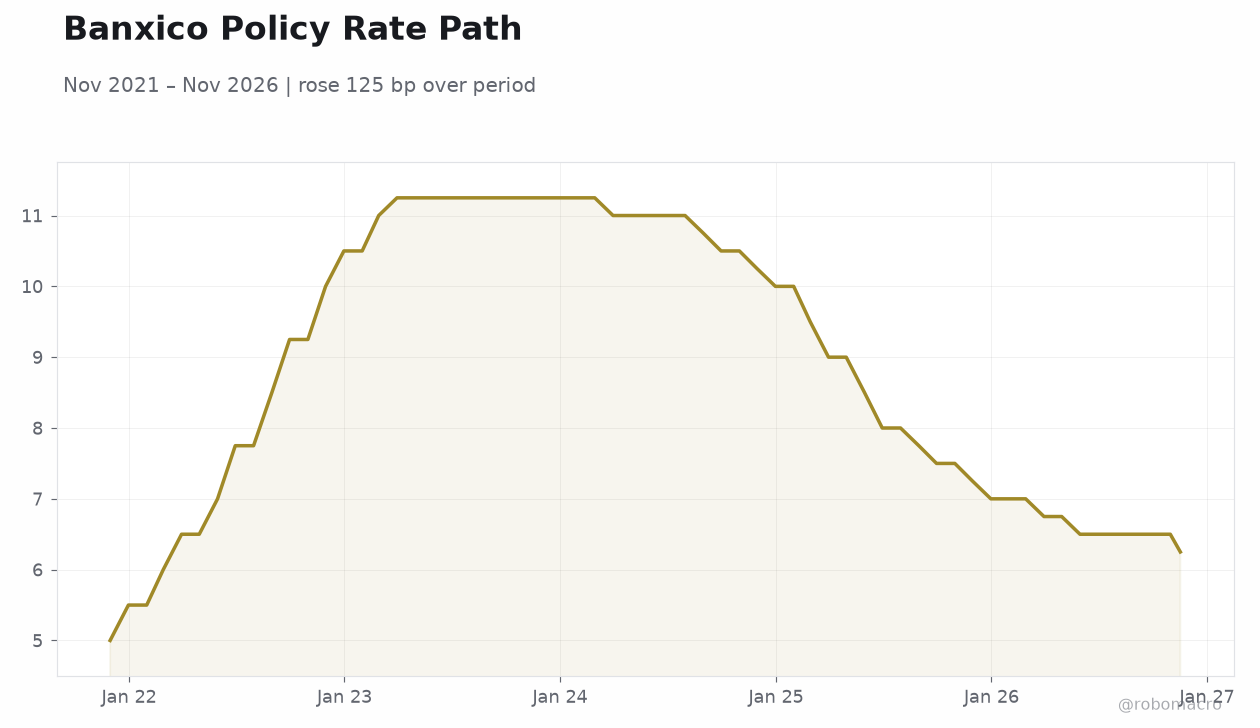 Banxico Policy Rate Path | Type: macro_line | Policy Rate %: 6.25 (2026-11-17) | Range: 5–11.25 | Trend(5pt): 5,11,11,7.75,6.25
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- USD/MXN jumps 2.18% to 18.82 as hawkish Fed minutes lift dollar broadly
- IPC Bolsa drops 1.75% to 69,154.17; 10-year Mbono yield steady at 9.28%
- Sheinbaum-Xi talks signal deeper Mexico-China cooperation amid USMCA review
Yesterday's Recap
Mexico's currency bore the brunt of a broad dollar rally Wednesday, with USD/MXN surging 2.18% to 18.82 and EUR/MXN climbing 2.21% to 20.69 as traders digested hawkish FOMC minutes. The IPC Bolsa fell 1.75% to 69,154.17, tracking weakness across Latin American equities, while Brazil's Ibovespa shed 1.34%. The Mexico 10-year government yield held flat at 9.28%, showing limited domestic duration stress despite the currency move.
WTI crude slipped 1.45% to $82.05 and Brent dropped 3.22% to $88.99, a modest negative for Pemex-linked fiscal revenues. Gold eased 0.39% to $3,727.40 while silver was essentially unchanged at $45.04. No scheduled Mexican data releases printed Wednesday, leaving external factors to drive price action.
The Day Ahead
The Mexican calendar is empty Thursday, so attention shifts entirely to external drivers and positioning ahead of month-end. Traders will watch US initial claims and any Fed speakers for confirmation of the December tightening bias embedded in Wednesday's minutes. Peso liquidity may thin as market participants square books following the sharp currency move.
Banxico's next policy decision is not until December 17, leaving a data-dependent vacuum in the near term. Any further dollar strength would keep USD/MXN testing the 19.00 handle, a level that could invite verbal intervention from Mexican officials.
Other Economic Notes
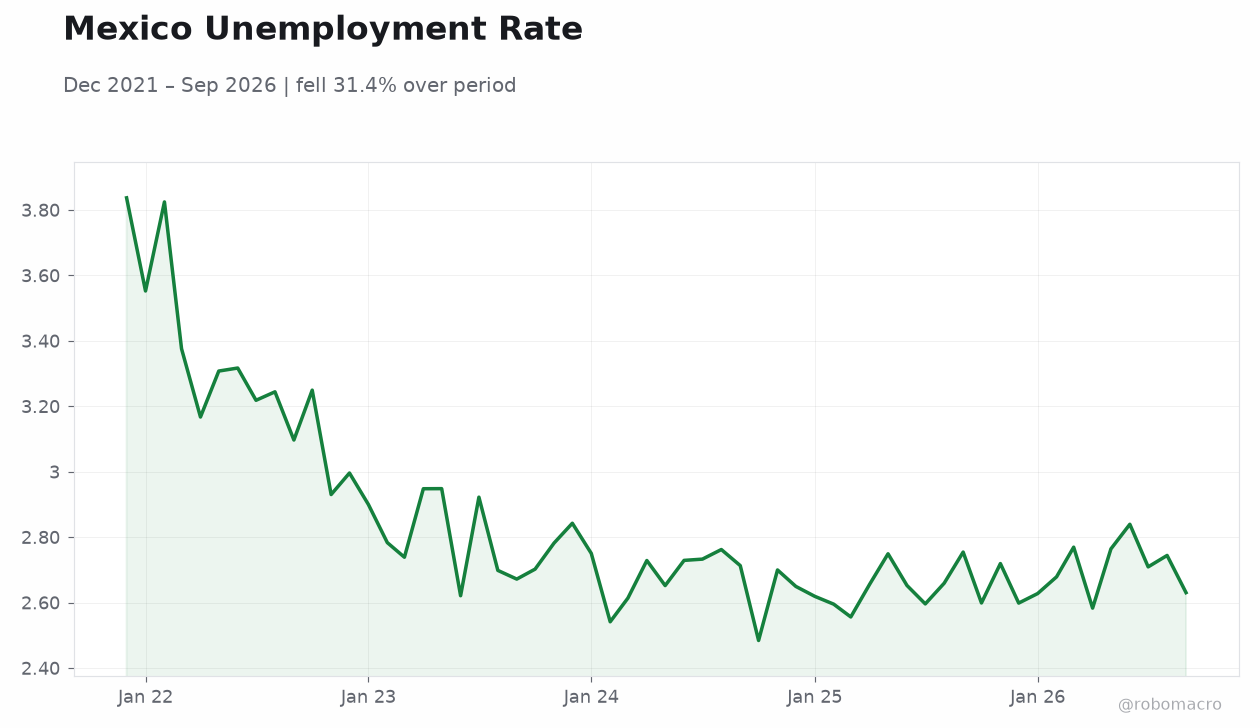
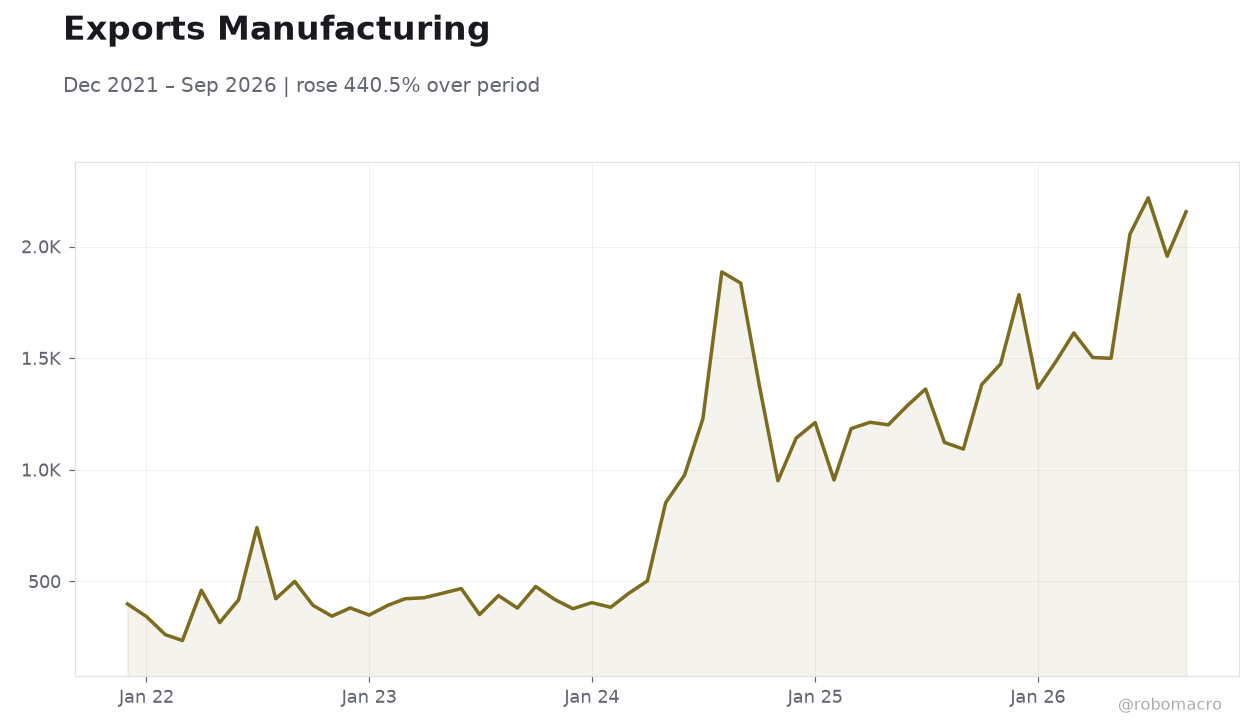
President Sheinbaum's meeting with Chinese President Xi Jinping points to deeper Mexico-China cooperation, a delicate balancing act as Washington scrutinizes Chinese investment in Mexican manufacturing under USMCA rules of origin. Nearshoring flows remain the structural anchor for Mexican industrial real estate and northern border manufacturing, though the strong peso earlier this year had begun to erode cost advantages. CPI at 3.45% year-on-year sits within Banxico's tolerance band, giving the central bank room to look through currency-driven price pressure.
Fiscal dynamics around Pemex remain a latent sovereign risk, with lower crude prices narrowing the state oil company's revenue base. Mexican cartel-run crystal meth labs appearing in the UK underscore deepening trade and security linkages beyond North America.