Nordics Macro Daily(Beta Mode)
Nordic Equities Rise Ahead of Rate Decisions
Market Snapshot
| Asset | Level | Change |
|---|---|---|
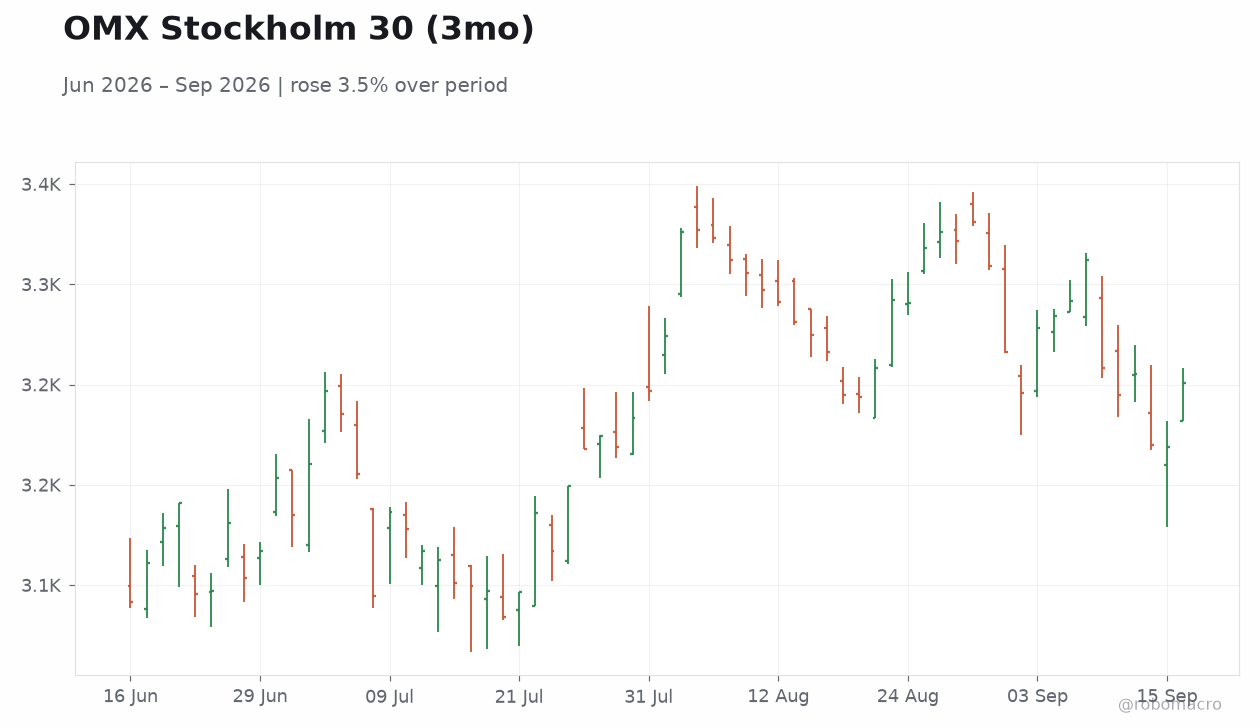
| OMX Stockholm 30 | 3,250.63 | +0.98% |
| Oslo Bors | 2,123.43 | +0.49% |
| OMX Copenhagen 25 | 1,851.33 | +0.08% |
| OMX Helsinki 25 | 6,499.26 | +0.84% |
| USD/SEK | 9.78 | +0.18% |
| USD/NOK | 9.42 | +0.81% |
| EUR/SEK | 11.28 | +0.02% |
| EUR/NOK | 10.81 | +0.18% |
| Brent Crude | 104.88 | -0.90% |
| Gold | 4,341.70 | -1.04% |
| Bitcoin | 76,312.94 | +0.93% |
| Sweden 10Y Govt Yield | 3.25% | +1 bp |
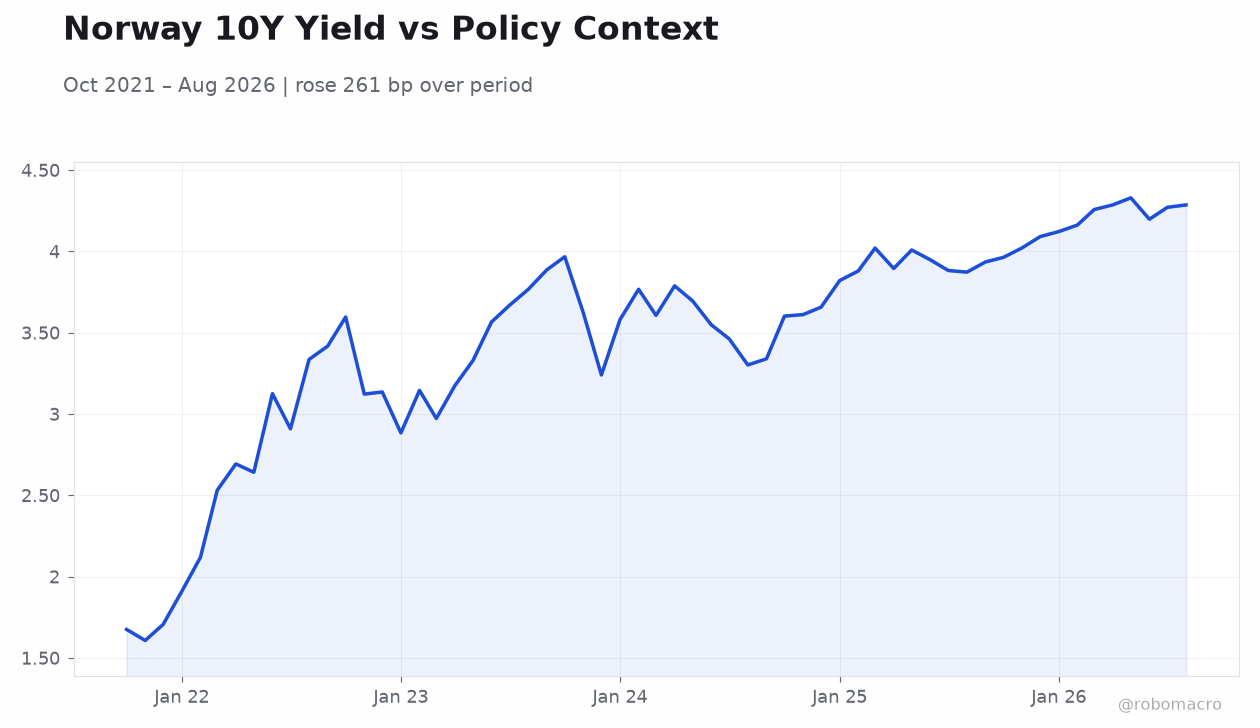
| Norway 10Y Govt Yield | 4.54% | -4 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
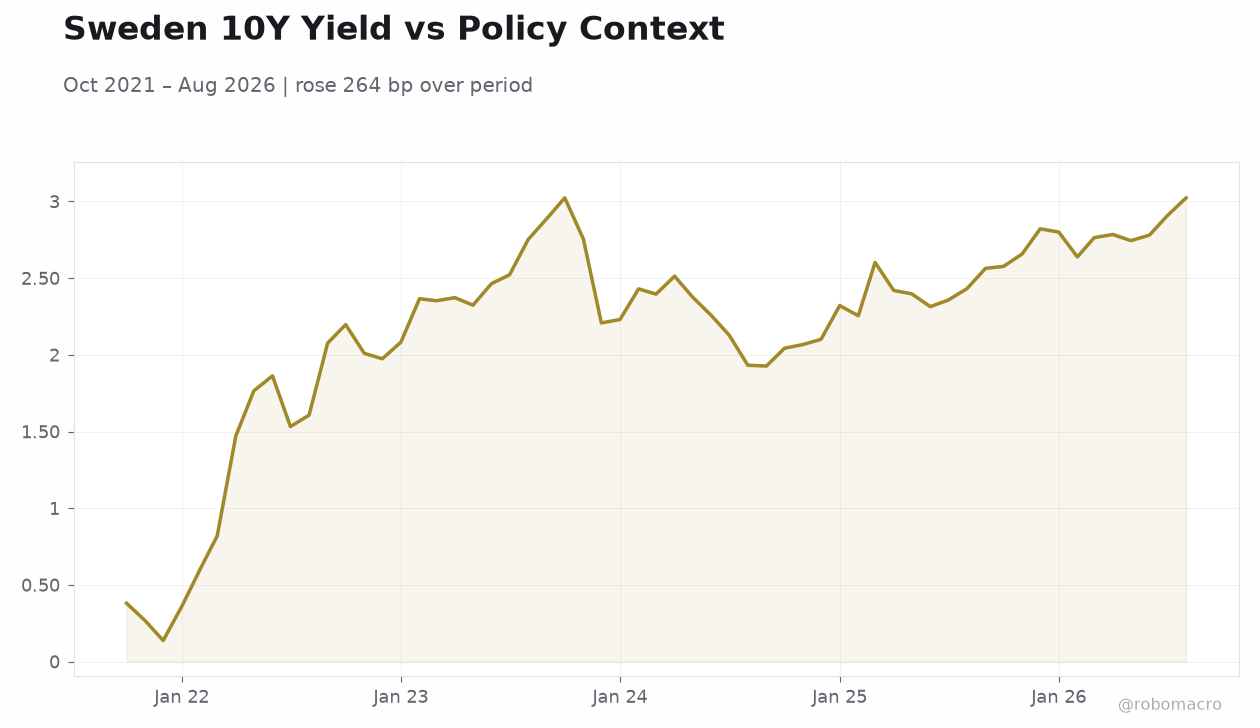 Sweden 10Y Yield vs Policy Context | Type: macro_line | Sweden 10Y (%): 3.023 (2026-08-01) | Range: 0.138–3.024 | Trend(6pt): 0.3806,1.974,2.43,2.42,2.781,3.023
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Riksbank Rate Decision | 1.75 | - | 03:30 |
| Norges Bank Interest Rate Decision | 4.25 | - | 04:00 |
- OMX Stockholm 30 gained 0.98% to 3,250.63 while Oslo Bors rose 0.49% to 2,123.43 on 16 September.
- Sweden 10-year yield edged up 1 bp to 3.25%; Norway 10-year yield fell 4 bp to 4.54%.
- Riksbank and Norges Bank both scheduled to announce policy on 24 September with no fresh data altering near-term views.
Yesterday's Recap
Equity markets closed higher across the Nordic region on 16 September. The OMX Stockholm 30 advanced 0.98% to 3,250.63 while the OMX Helsinki 25 rose 0.84% to 6,499.26. Oslo Bors added 0.49% to 2,123.43 and the OMX Copenhagen 25 gained 0.08% to 1,851.33.
USD/SEK climbed 0.18% to 9.78 and USD/NOK increased 0.81% to 9.42. EUR/SEK was virtually flat at 11.28 while EUR/NOK rose 0.18% to 10.81. Brent crude declined 0.90% to 104.88.
The Sweden 10-year yield rose 1 bp to 3.25% and the Norway 10-year yield eased 4 bp to 4.54%. No macroeconomic releases were published in Sweden, Norway, Denmark or Finland. The Riksbank Business Survey highlighted that demand strengthened after earlier summer concerns and that war-related cost increases remain manageable for firms.
The Day Ahead
Markets will focus on the Riksbank and Norges Bank rate decisions both scheduled for 24 September. The Riksbank is expected to assess the latest Business Survey showing improved demand and manageable cost pressures. Norges Bank will weigh inflation against growth while monitoring Brent crude at 104.88 and its impact on the krone.
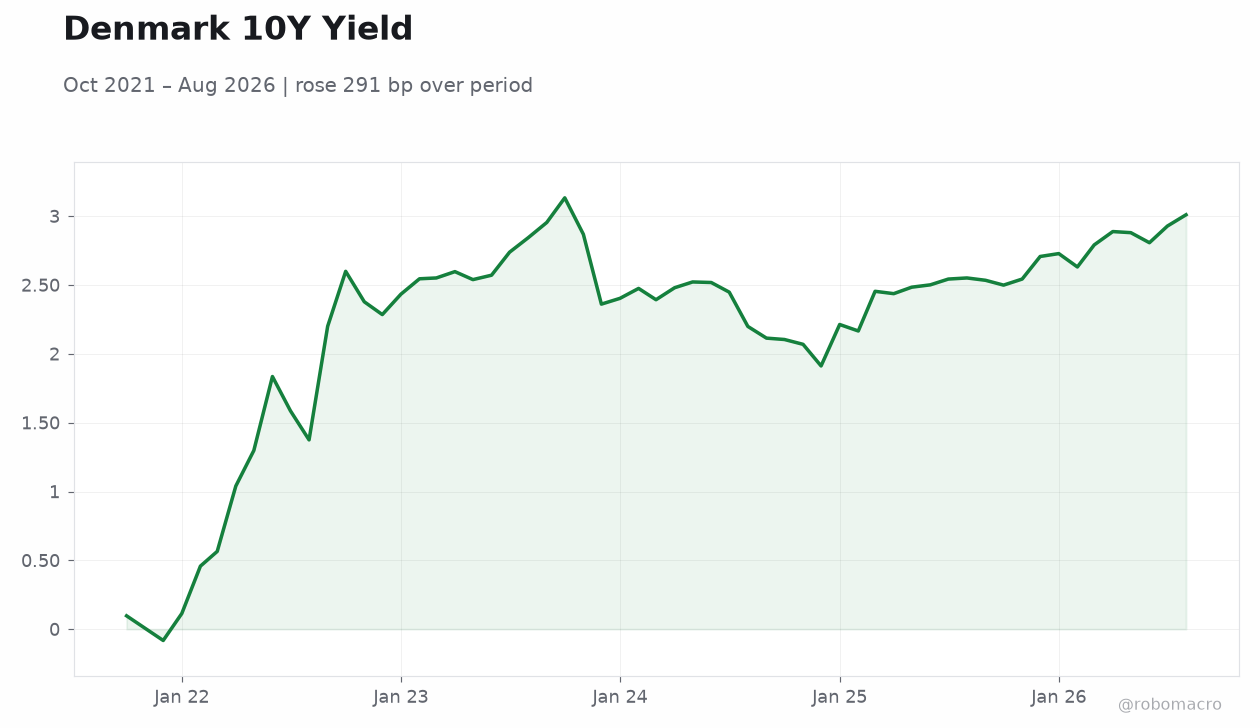
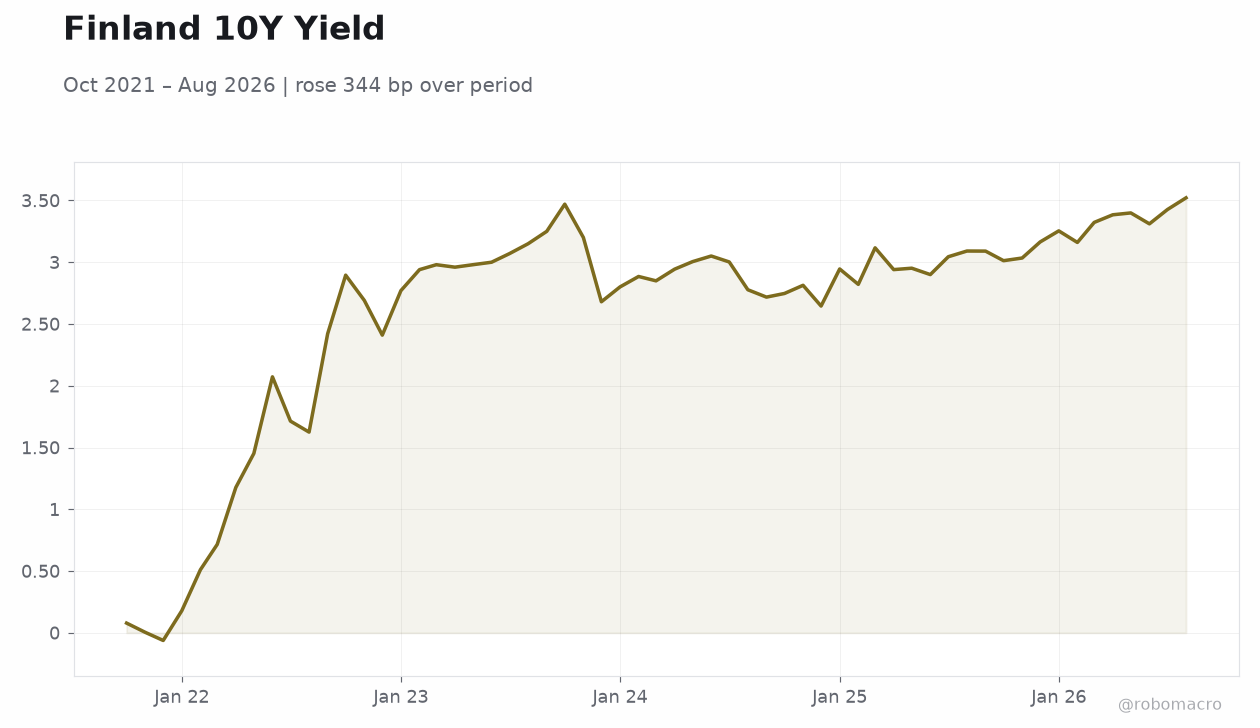
No data releases are listed for 17-18 September across the four countries. Analysts will also track any comments on the Swedish political outlook after SVT forecast a centre-left majority. Danish and Finnish markets remain quiet with attention on ECB signals that affect the EUR/DKK peg.
Sweden’s CPI YoY stands at 0.70% and Norway’s at 3.30%, providing the latest available inflation backdrop ahead of the meetings.
Other Economic Notes
The Riksbank Business Survey indicated demand strengthened after summer concerns and war-related costs are viewed as manageable. Sweden’s export-oriented manufacturing sector should benefit from this improvement. Norway’s fiscal outlook remains tied to Brent crude revenue despite the modest price decline recorded on 16 September.
Denmark’s peg to the euro continues to anchor Danmarks Nationalbank policy while Finland follows ECB rates directly. No new housing or trade data emerged to alter regional growth assessments. The Norway 10-year yield at 4.54% and Sweden 10-year yield at 3.25% reflect stable fixed-income conditions into the policy announcements.