Nordics Macro Daily(Beta Mode)
Swedish Left Wins, Nordic Equities Advance
Market Snapshot
| Asset | Level | Change |
|---|---|---|
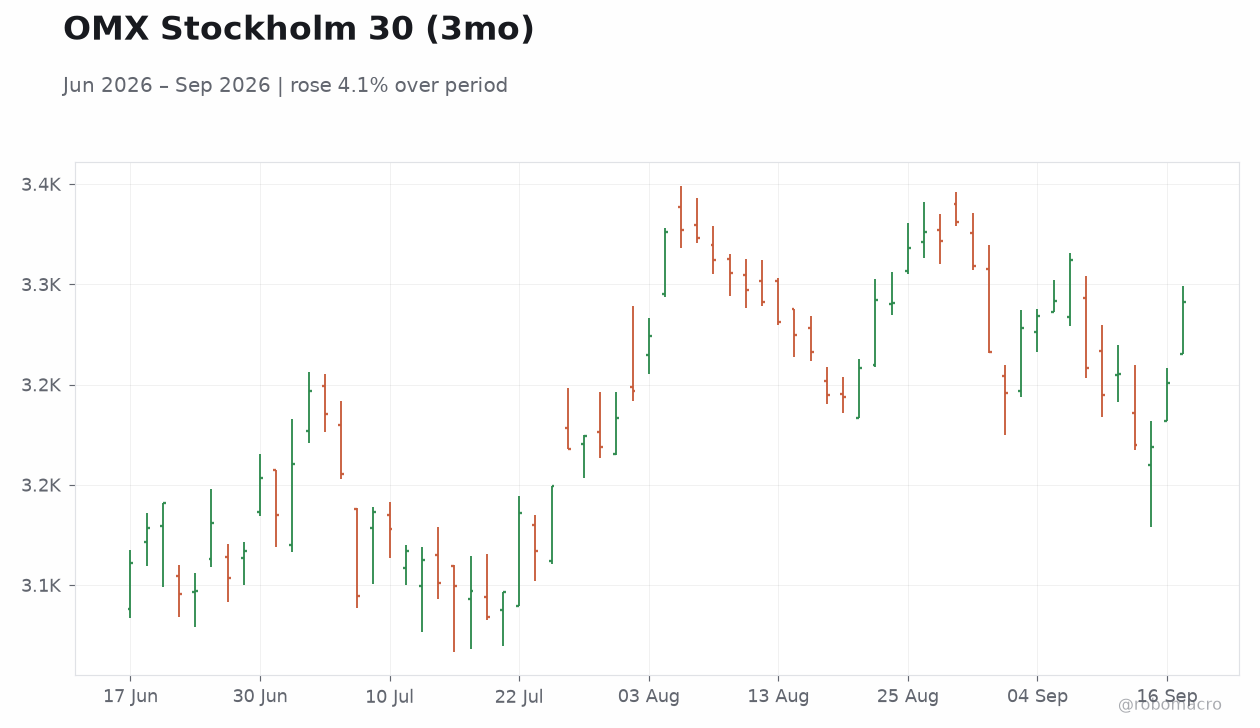
| OMX Stockholm 30 | 3,291.30 | +1.25% |
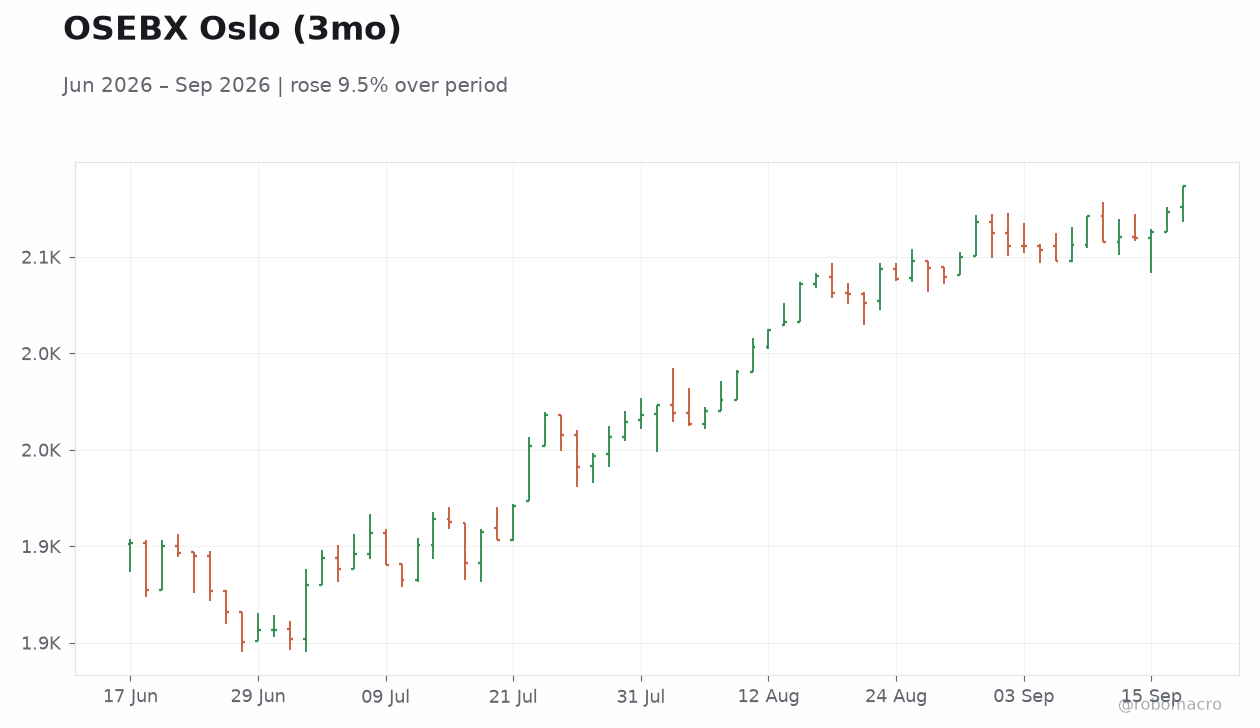
| Oslo Bors | 2,136.55 | +0.62% |
| OMX Copenhagen 25 | 1,882.89 | +1.70% |
| OMX Helsinki 25 | 6,612.16 | +1.74% |
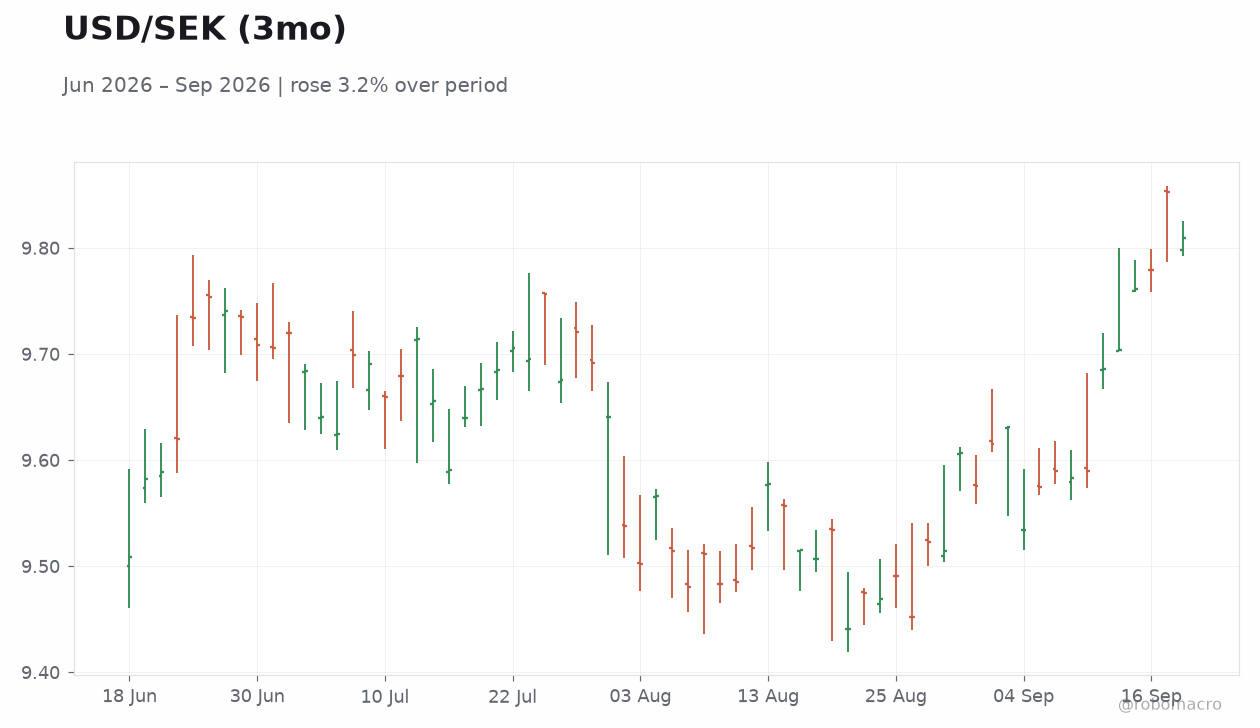
| USD/SEK | 9.85 | +0.75% |
| USD/NOK | 9.42 | +0.76% |
| EUR/SEK | 11.30 | +0.16% |
| EUR/NOK | 10.81 | +0.05% |
| Brent Crude | 103.42 | -1.34% |
| Gold | 4,426.10 | +0.60% |
| Bitcoin | 77,500.74 | +1.77% |
| Sweden 10Y Govt Yield | 3.23% | -2 bp |
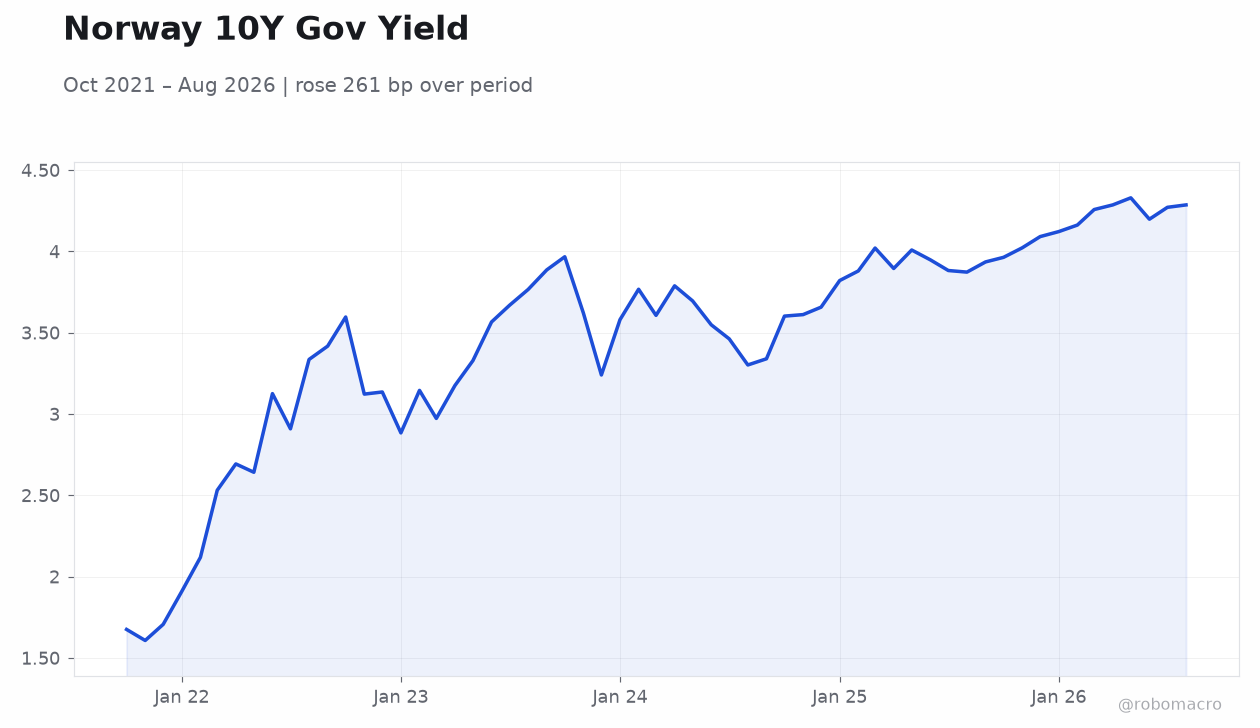
| Norway 10Y Govt Yield | 4.51% | -3 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
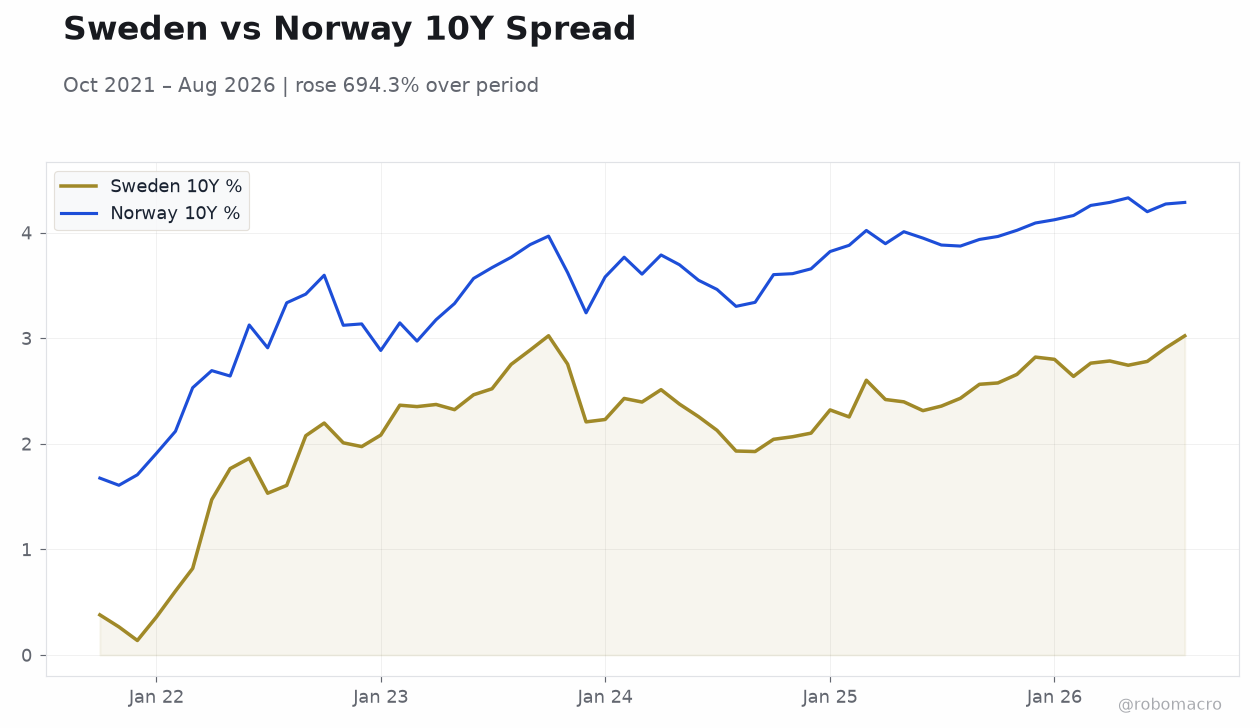 Sweden vs Norway 10Y Spread | Type: macro_line | Sweden 10Y %: 3.023 (2026-08-01) | Range: 0.138–3.024 | Trend(6pt): 0.3806,1.974,2.43,2.42,2.781,3.023 | Norway 10Y %: 4.286 (2026-08-01) | Range: 1.608–4.33 | Trend(6pt): 1.676,3.136,3.768,3.895,4.198,4.286
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- Sweden’s centre-left secured a slim parliamentary majority, prompting Prime Minister Kristersson’s resignation and positioning Magdalena Andersson to return as PM.
- Nordic equities posted broad gains while 10-year yields eased, with Sweden’s at 3.23% (-2 bp) and Norway’s at 4.51% (-3 bp).
- No economic data releases occurred across the region; Norges Bank Regional Network noted only minor changes in growth prospects.
Yesterday's Recap
Nordic equity markets advanced on Thursday as Sweden’s political landscape shifted. The OMX Stockholm 30 rose 1.25% to 3,291.30, Oslo Børs gained 0.62% to 2,136.55, OMX Copenhagen 25 climbed 1.70% to 1,882.89, and OMX Helsinki 25 led with a 1.74% increase to 6,612.16. USD/SEK rose 0.75% to 9.85 while USD/NOK increased 0.76% to 9.42, reflecting modest Nordic-currency softening.
Sweden’s 10-year government yield fell 2 bp to 3.23% and Norway’s declined 3 bp to 4.51%. No CPI, GDP or labour-market figures were published for any Nordic country. The dominant development remained Sweden’s election outcome, with the centre-left opposition securing 176 seats to the government’s 173.
Peab won a SEK 349 million contract to expand Hitachi Energy facilities in Landskrona. Norges Bank’s Q3 Regional Network survey indicated only marginal revisions to Norwegian growth expectations.
The Day Ahead
The Nordic calendar remains empty for Friday, with no scheduled releases for CPI, industrial production or retail sales in Sweden, Norway, Denmark or Finland. Markets will monitor any post-election statements from incoming Swedish leadership on fiscal priorities. Norges Bank officials may comment on the Regional Network findings and oil-price effects on the krone.
Danish Nationalbank activity is expected to stay limited to routine EUR/DKK peg maintenance. Finland’s data flow will align with broader euro-area releases. Equity and fixed-income desks will watch Brent crude, which closed at 103.42 after a 1.34% decline, for any impact on Norwegian fiscal sentiment.
Other Economic Notes
Sweden’s export-oriented manufacturing sector faces policy uncertainty following the narrow left-wing victory, though Andersson’s emphasis on inclusive growth may support domestic demand. Norway’s oil-linked economy continues to benefit from Brent levels above 100 despite the daily pullback, supporting the krone’s medium-term valuation. Denmark’s pegged currency regime limits independent rate moves, keeping Danmarks Nationalbank focused on euro-area liquidity conditions.
Finland’s eurozone membership transmits ECB policy directly, with no separate national rate signals expected. ↓ p.2