Nordics Macro Daily(Beta Mode)
Riksbank Holds, Norges Bank Faces Oil Slide
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| OMX Stockholm 30 | 3,286.87 | +0.69% |
| Oslo Bors | 2,107.80 | -0.45% |
| OMX Copenhagen 25 | 1,870.16 | -0.68% |
| OMX Helsinki 25 | 6,556.84 | -0.03% |
| USD/SEK | 9.83 | +0.07% |
| USD/NOK | 9.42 | -0.02% |
| EUR/SEK | 11.28 | +0.09% |
| EUR/NOK | 10.81 | +0.02% |
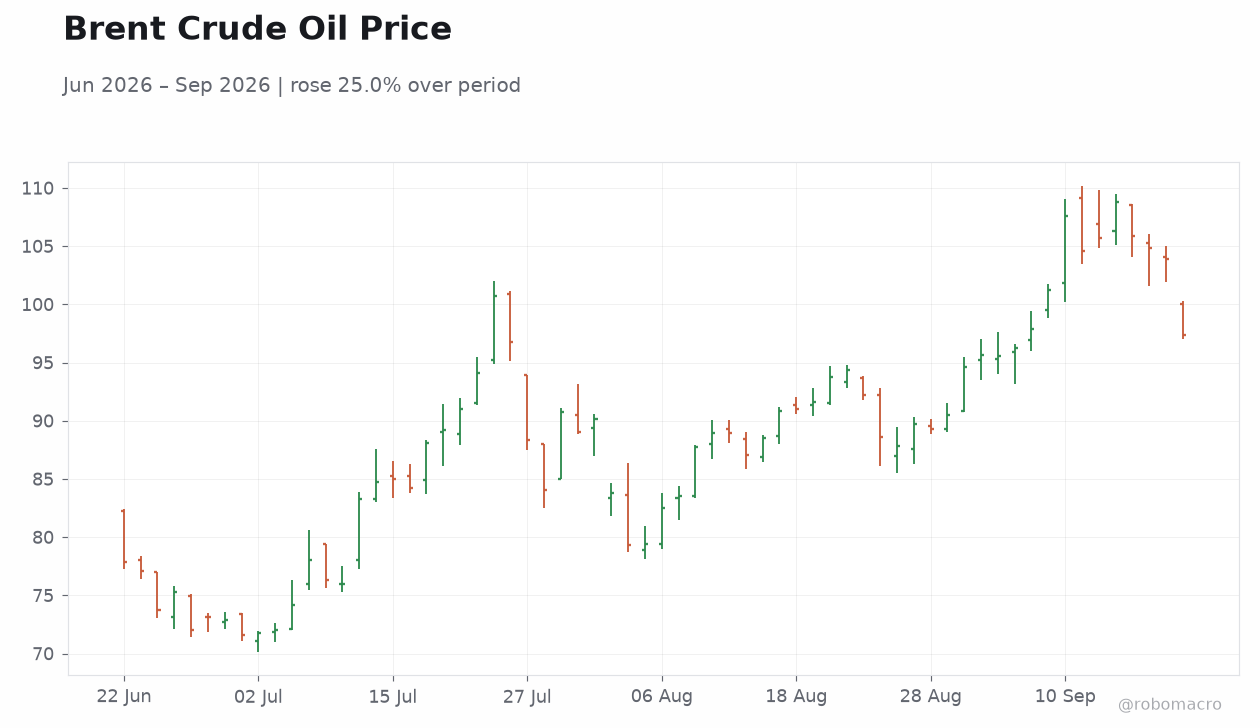
| Brent Crude | 97.35 | -6.28% |
| Gold | 4,384.50 | -0.91% |
| Bitcoin | 81,599.65 | +0.45% |
| Sweden 10Y Govt Yield | 3.21% | +3 bp |
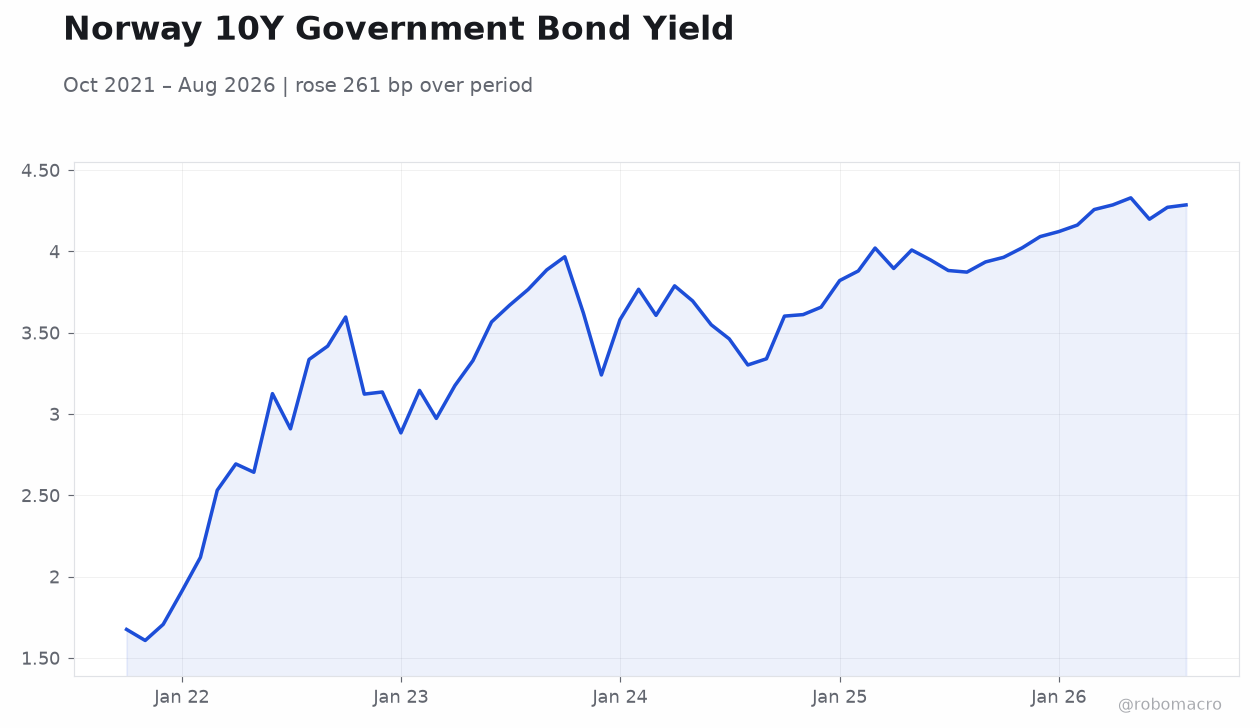
| Norway 10Y Govt Yield | 4.47% | -4 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
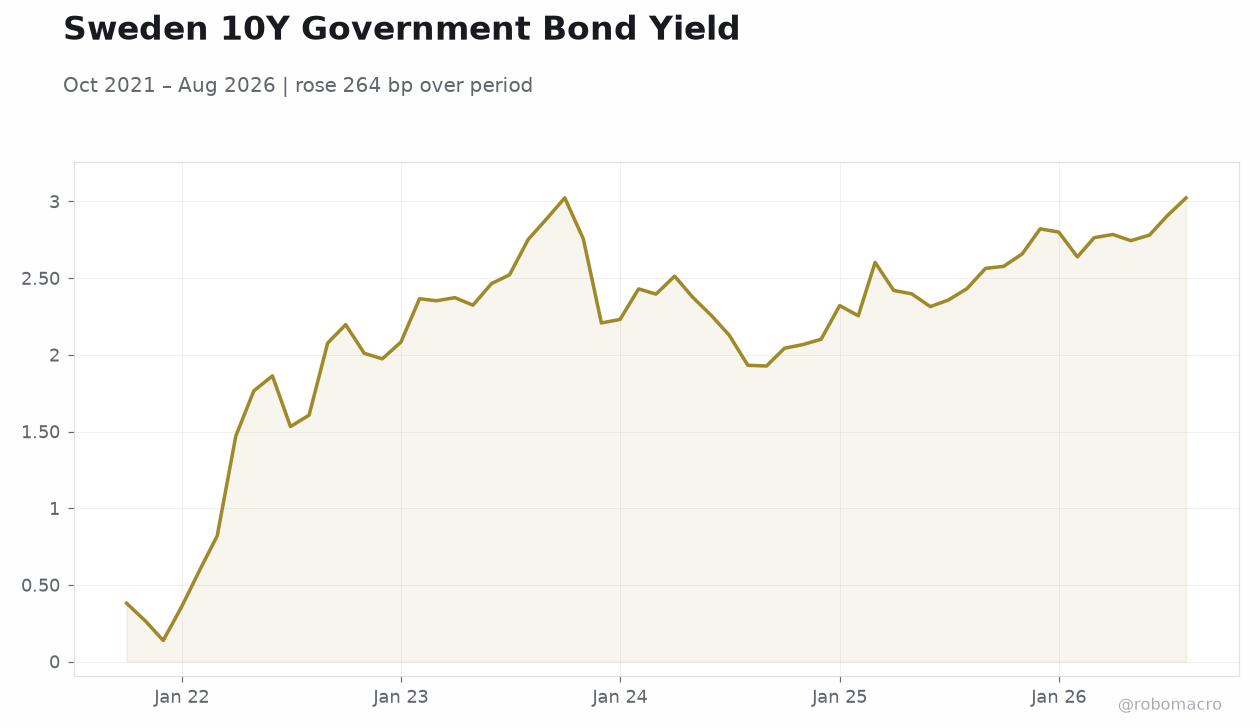 Sweden 10Y Government Bond Yield | Type: macro_line | Yield %: 3.023 (2026-08-01) | Range: 0.138–3.024 | Trend(6pt): 0.3806,1.974,2.43,2.42,2.781,3.023
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Riksbank Rate Decision | 1.75 | - | 23:30 |
| Norges Bank Interest Rate Decision | 4.25 | - | 00:00 |
| Press Conference by Riksbank | - | - | 01:00 |
- Riksbank set to hold policy rate on September 23 before potential November hike.
- Norges Bank decision on September 24 clouded by Brent crude drop of 6.28% to 97.35.
- Nordic equities mixed as OMX Stockholm 30 rose 0.69% while Oslo Bors fell 0.45%.
Yesterday's Recap
Equity markets in the Nordic region closed mixed on September 20. OMX Stockholm 30 advanced 0.69% to 3,286.87 while Oslo Bors declined 0.45% to 2,107.80. OMX Copenhagen 25 fell 0.68% to 1,870.16 and OMX Helsinki 25 edged down 0.03% to 6,556.84.
In FX markets, USD/SEK rose 0.07% to 9.83 and EUR/SEK gained 0.09% to 11.28, with USD/NOK easing 0.02% to 9.42. Government bond yields diverged, with Sweden’s 10-year yield rising 3 bp to 3.21% and Norway’s 10-year yield falling 4 bp to 4.47%. Brent crude’s 6.28% decline to 97.35 weighed on Norway’s fiscal outlook as an oil exporter, while Sweden’s low CPI YoY reading of 0.70% contrasted with Norway’s 3.30% figure.
No macroeconomic data releases occurred across Sweden, Norway, Denmark or Finland.
The Day Ahead
Markets will focus on the Riksbank rate decision scheduled for September 23 at 23:30 ET, with previews pointing to a hold at the current level followed by a possible November move. The subsequent press conference at 01:00 ET on September 24 will provide further guidance on inflation and growth. Norges Bank’s interest rate decision at 00:00 ET on September 24 will draw attention given persistent inflation above target and ongoing economic expansion.
Lower oil prices may influence Norges Bank’s assessment of NOK valuation and petroleum revenue. No releases are scheduled for Denmark or Finland in the immediate window.
Other Economic Notes
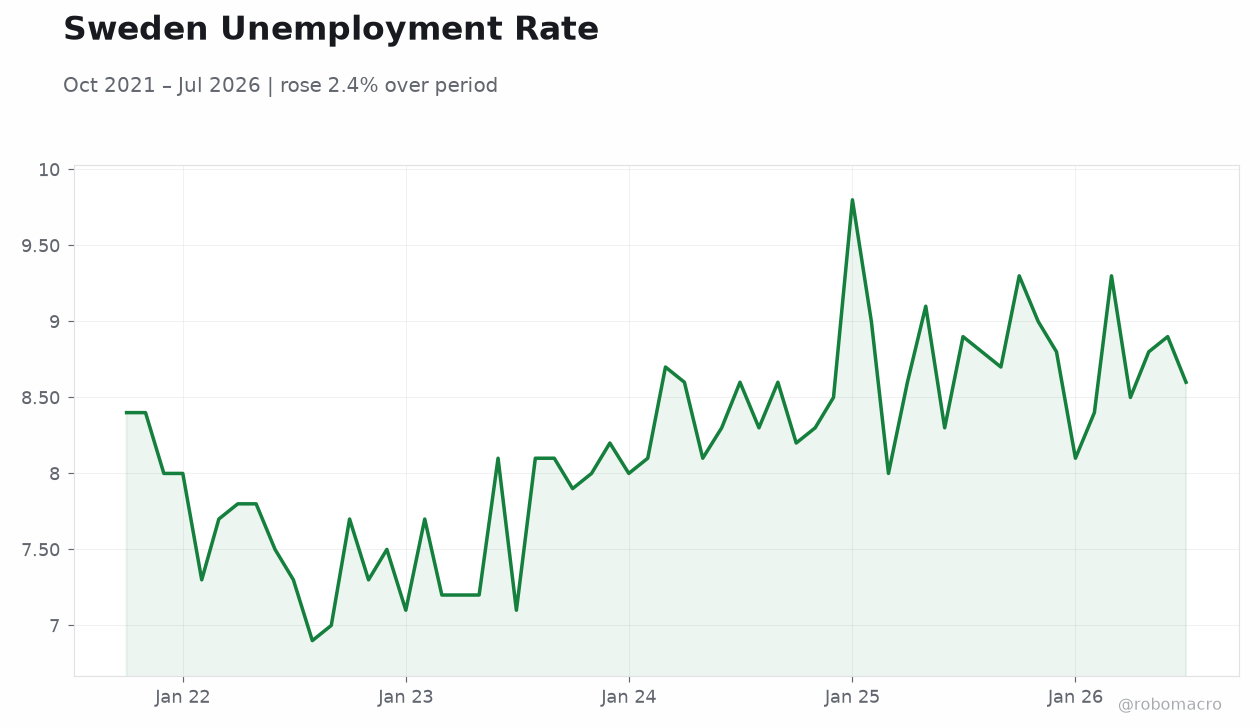
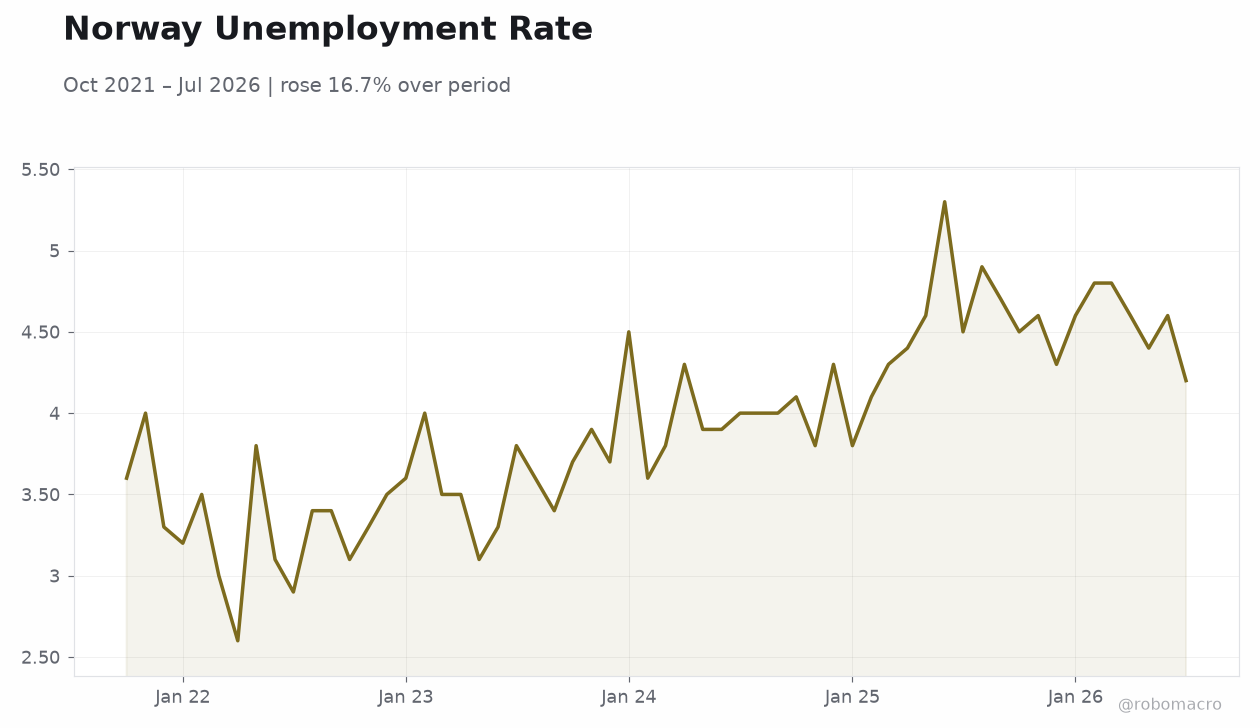
Sweden’s export-oriented manufacturing sector faces stable but low inflation at 0.70% YoY, supporting expectations of measured policy adjustments. Norway’s higher CPI of 3.30% YoY keeps pressure on Norges Bank despite the sharp Brent decline that reduces expected fiscal inflows. Denmark maintains its EUR/DKK peg through alignment with ECB policy, limiting independent rate flexibility.
Finland, operating under the ECB framework, experiences indirect effects from eurozone-wide developments rather than domestic Nordic policy shifts. Housing market data remain absent from recent releases, leaving focus on central bank signals.