Nordics Macro Daily(Beta Mode)
Riksbank Hold, Norges Hike Eyed as Oil Falls
Market Snapshot
| Asset | Level | Change |
|---|---|---|
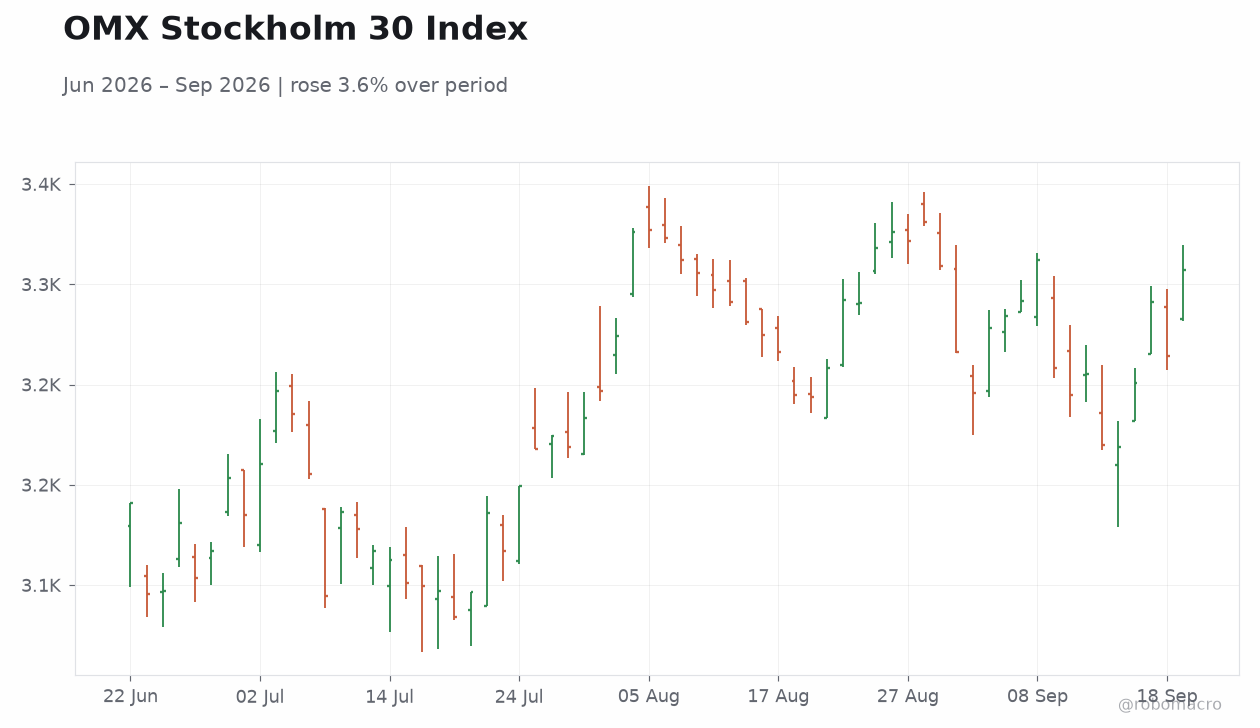
| OMX Stockholm 30 | 3,307.02 | +1.31% |
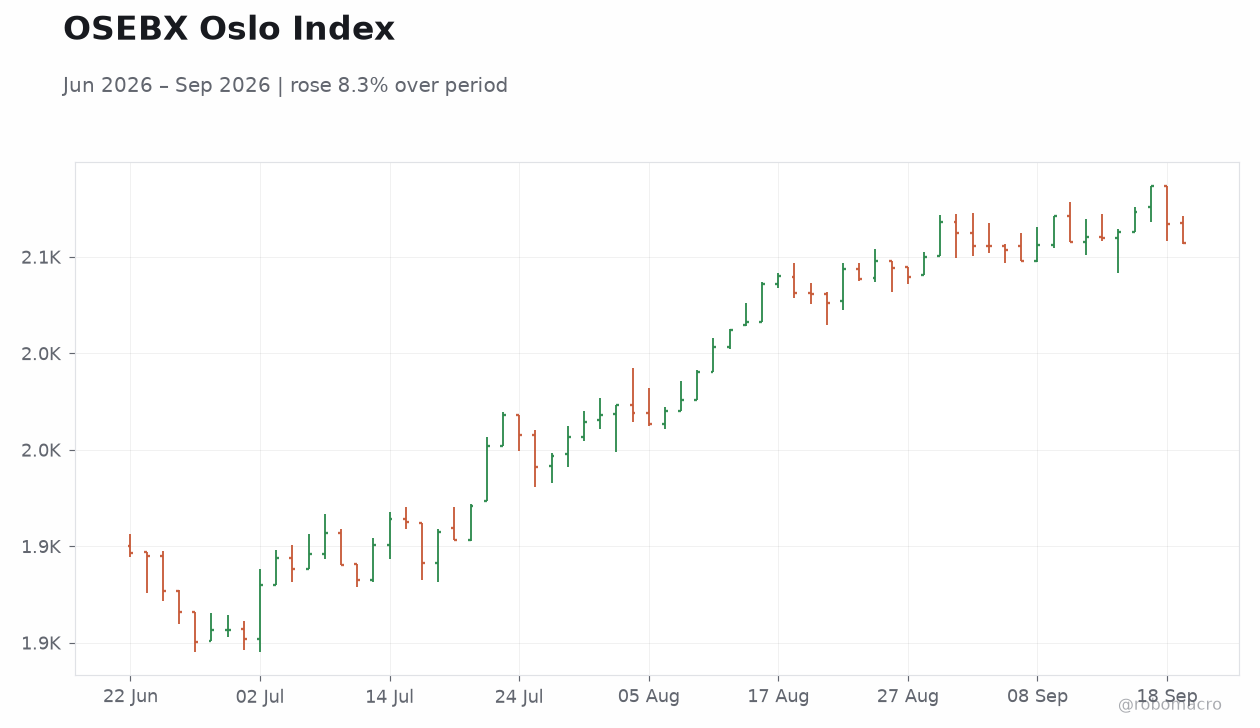
| Oslo Bors | 2,107.46 | -0.47% |
| OMX Copenhagen 25 | 1,858.54 | -0.62% |
| OMX Helsinki 25 | 6,585.46 | +0.41% |
| USD/SEK | 9.84 | +0.06% |
| USD/NOK | 9.43 | +0.28% |
| EUR/SEK | 11.28 | -0.07% |
| EUR/NOK | 10.81 | +0.14% |
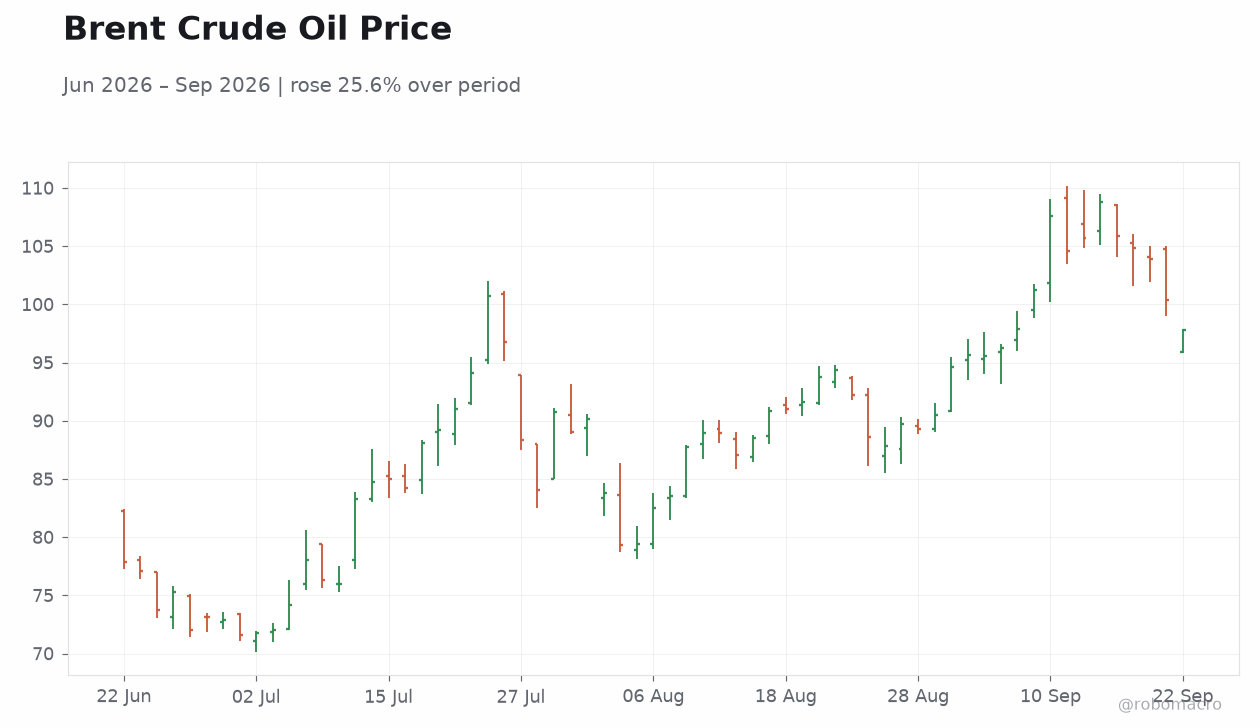
| Brent Crude | 97.80 | -2.53% |
| Gold | 4,356.30 | -0.63% |
| Bitcoin | 85,533.00 | +5.41% |
| Sweden 10Y Govt Yield | 3.21% | +3 bp |
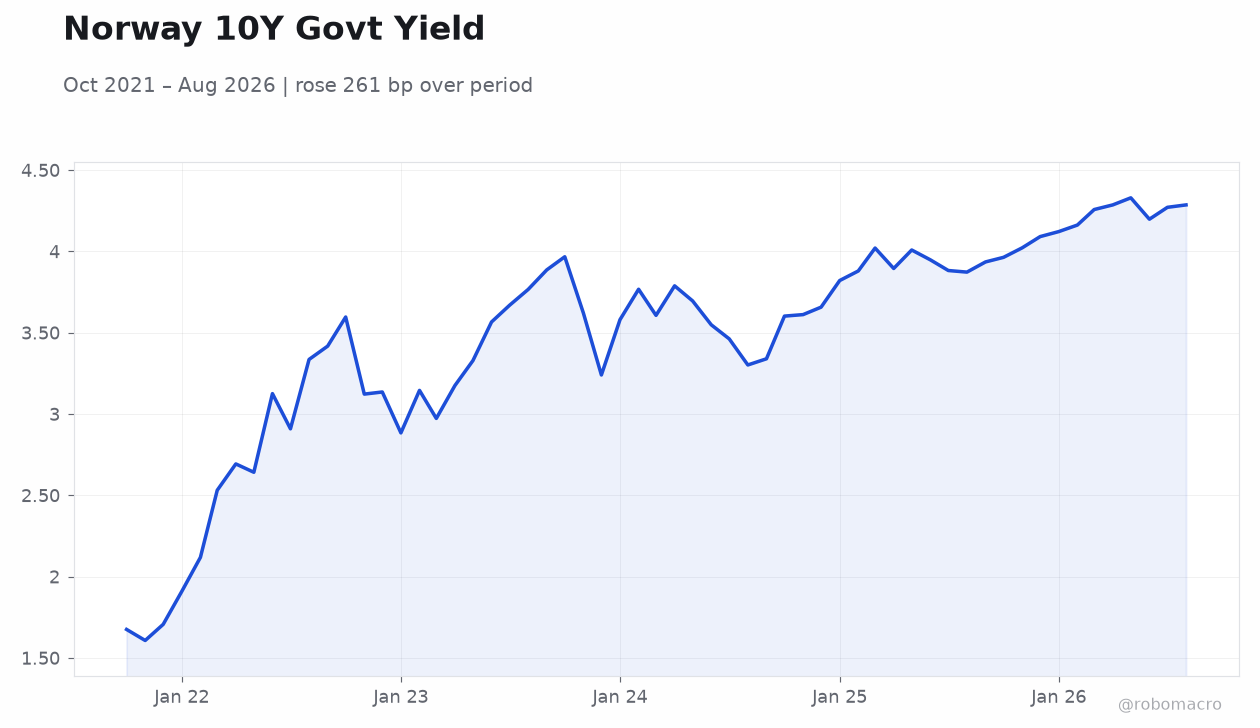
| Norway 10Y Govt Yield | 4.48% | +1 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
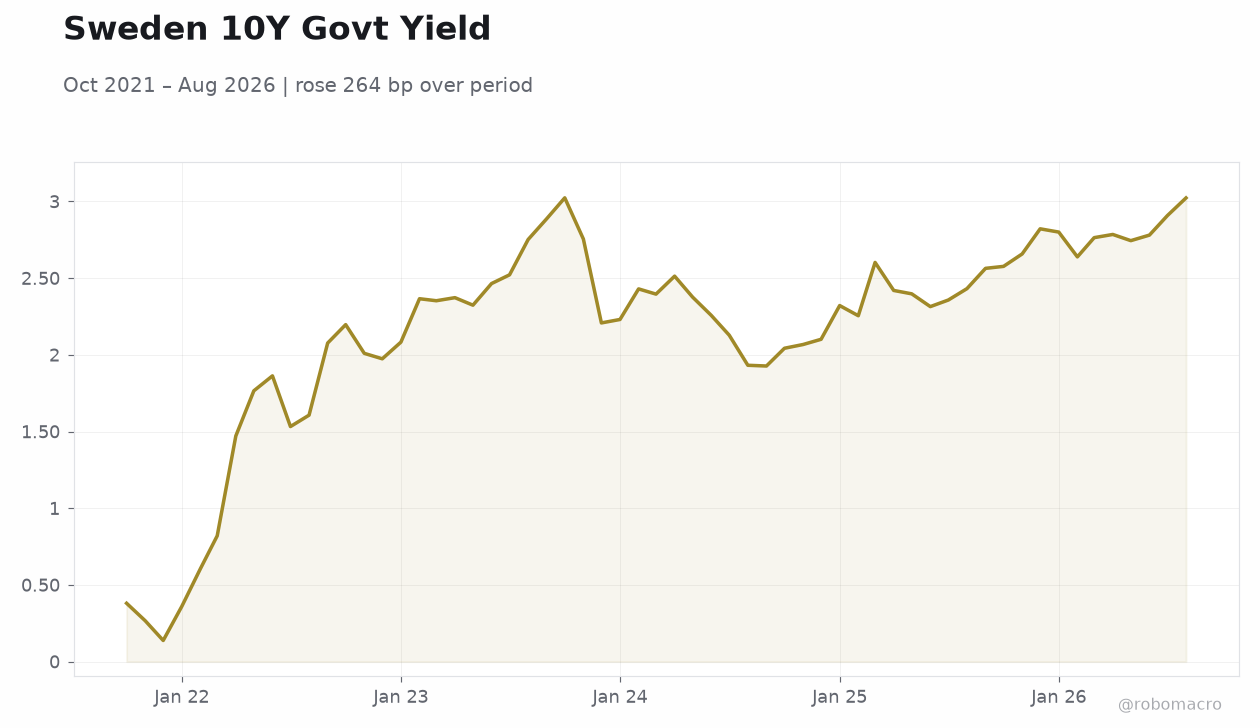 Sweden 10Y Govt Yield | Type: macro_line | Yield %: 3.023 (2026-08-01) | Range: 0.138–3.024 | Trend(6pt): 0.3806,1.974,2.43,2.42,2.781,3.023
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Riksbank Rate Decision | 1.75 | 1.75 | 23:30 |
| Norges Bank Interest Rate Decision | 4.25 | 4.50 | 00:00 |
| Press Conference by Riksbank | - | - | 01:00 |
- Riksbank expected to hold policy rate at 1.75% with focus on subdued 0.70% Sweden CPI YoY.
- Norges Bank decision leans toward 25 bp hike to 4.50% despite Brent crude falling 2.53%.
- Nordic equities mixed as OMX Stockholm 30 gained 1.31% while Oslo Bors declined 0.47%.
Yesterday's Recap
Equity markets delivered mixed results across the Nordic bloc on September 21. The OMX Stockholm 30 advanced 1.31% to 3,307.02 while the OMX Helsinki 25 rose 0.41% to 6,585.46. In contrast, the Oslo Bors fell 0.47% to 2,107.46 and the OMX Copenhagen 25 declined 0.62% to 1,858.54.
Currency moves remained contained with USD/SEK rising 0.06% to 9.84 and USD/NOK climbing 0.28% to 9.43. Brent crude’s 2.53% drop to 97.80 weighed on Norway’s fiscal outlook given its role as a major oil exporter. Sweden’s 10-year government yield increased 3 bp to 3.21% while Norway’s 10-year yield edged 1 bp higher to 4.48%.
No macroeconomic data releases occurred in Sweden, Norway, Denmark or Finland.
The Day Ahead
Attention centers on the Riksbank’s rate decision scheduled for 23:30 ET with consensus pointing to a hold at 1.75%. The subsequent press conference at 01:00 ET will provide updated guidance on inflation and growth. Markets also await the Norges Bank decision at 00:00 ET where a 25 bp hike to 4.50% remains the base case.
Norway’s higher 3.30% CPI YoY supports the case for further tightening relative to Sweden’s 0.70% reading. No data releases are listed for Denmark or Finland. Traders will monitor any signals on krona and krone volatility following the Brent decline.
Other Economic Notes
Lower oil prices reduce expected transfers to Norway’s sovereign wealth fund and ease pressure on the krone. Sweden’s export-oriented manufacturing sector faces headwinds from subdued domestic inflation and softer external demand. Denmark’s economy remains anchored by the EUR/DKK peg with Danmarks Nationalbank following ECB moves.
Finland’s eurozone membership means ECB policy directly shapes its borrowing costs and trade competitiveness. Housing markets in Sweden continue to adjust after prior rate hikes while Norway’s petroleum revenue outlook softens with Brent at 97.80.
Global Macro News
Brent’s sharp decline directly affects Norway’s fiscal position and currency valuation as the country relies heavily on petroleum exports. German economic data showing temporary loss of momentum may weigh on Swedish and Danish export orders given tight trade linkages. ↓ p.2