Nordics Macro Daily(Beta Mode)
Norges Bank Hike Call Splits Economists
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| OMX Stockholm 30 | 3,316.90 | +0.30% |
| Oslo Bors | 2,096.59 | -0.52% |
| OMX Copenhagen 25 | 1,849.85 | -0.47% |
| OMX Helsinki 25 | 6,599.92 | +0.22% |
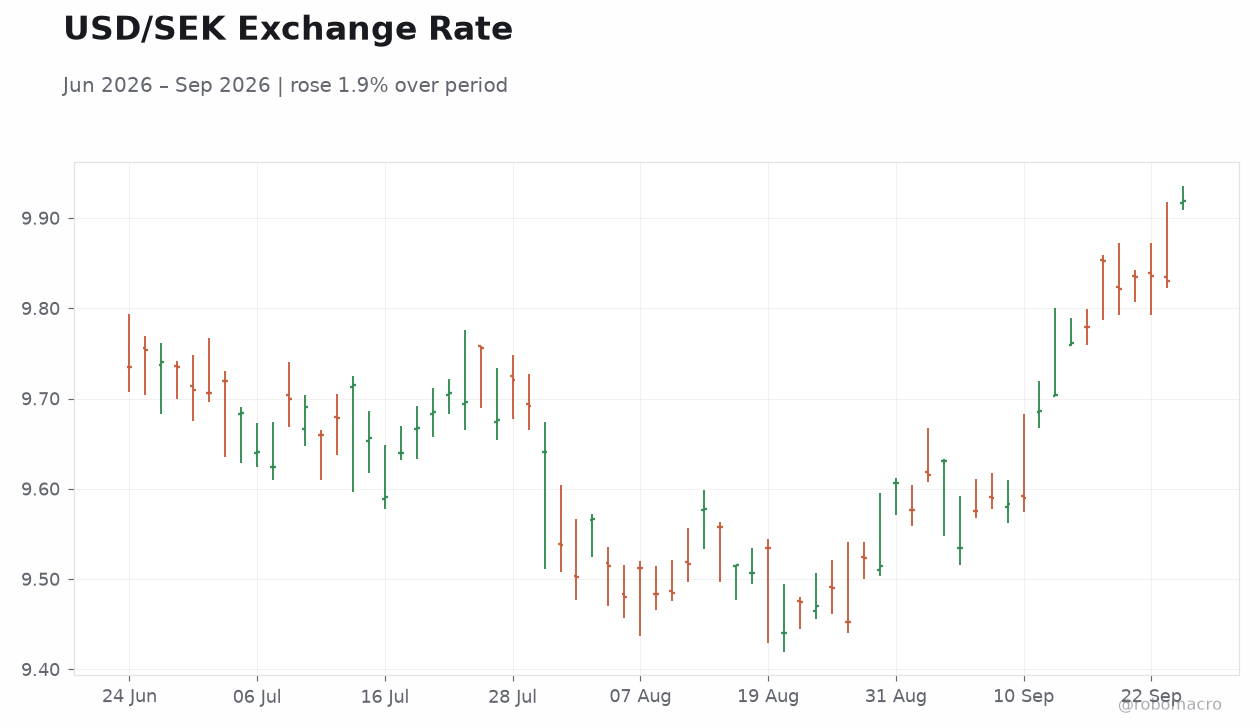
| USD/SEK | 9.92 | +0.87% |
| USD/NOK | 9.49 | +0.54% |
| EUR/SEK | 11.29 | +0.30% |
| EUR/NOK | 10.80 | -0.01% |
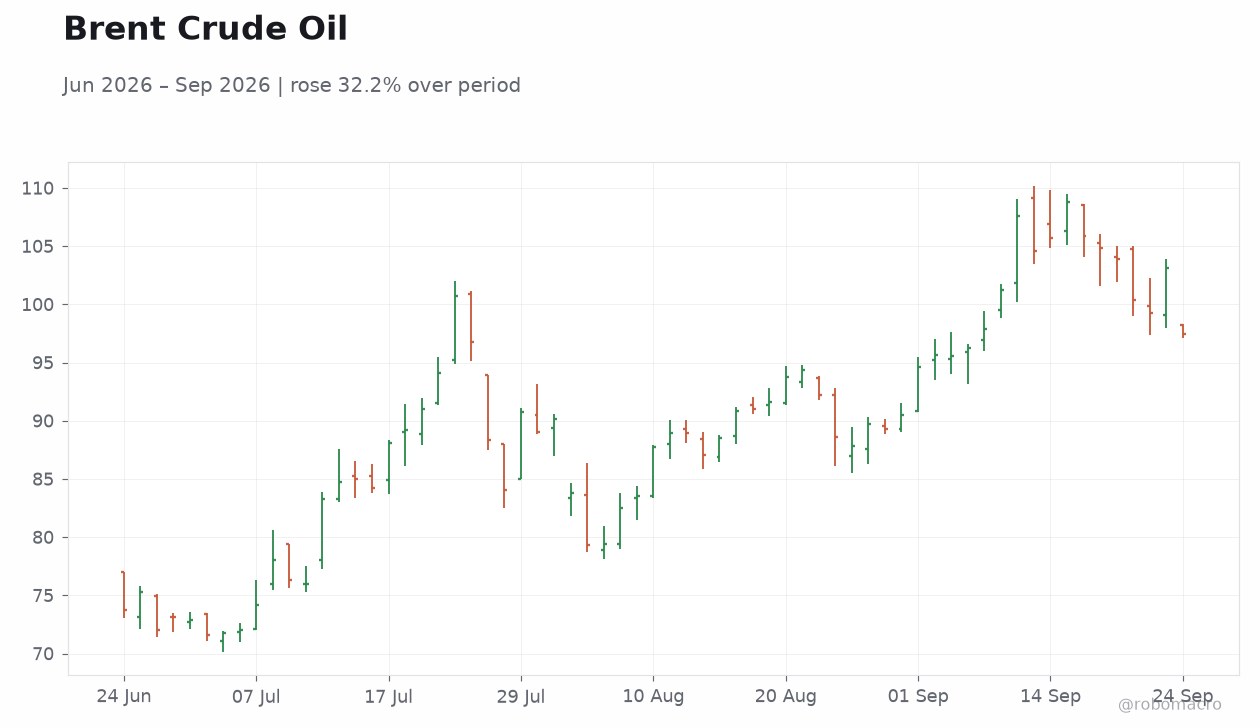
| Brent Crude | 97.45 | -5.46% |
| Gold | 4,324.80 | +0.15% |
| Bitcoin | 84,183.14 | -2.31% |
| Sweden 10Y Govt Yield | 3.12% | -2 bp |
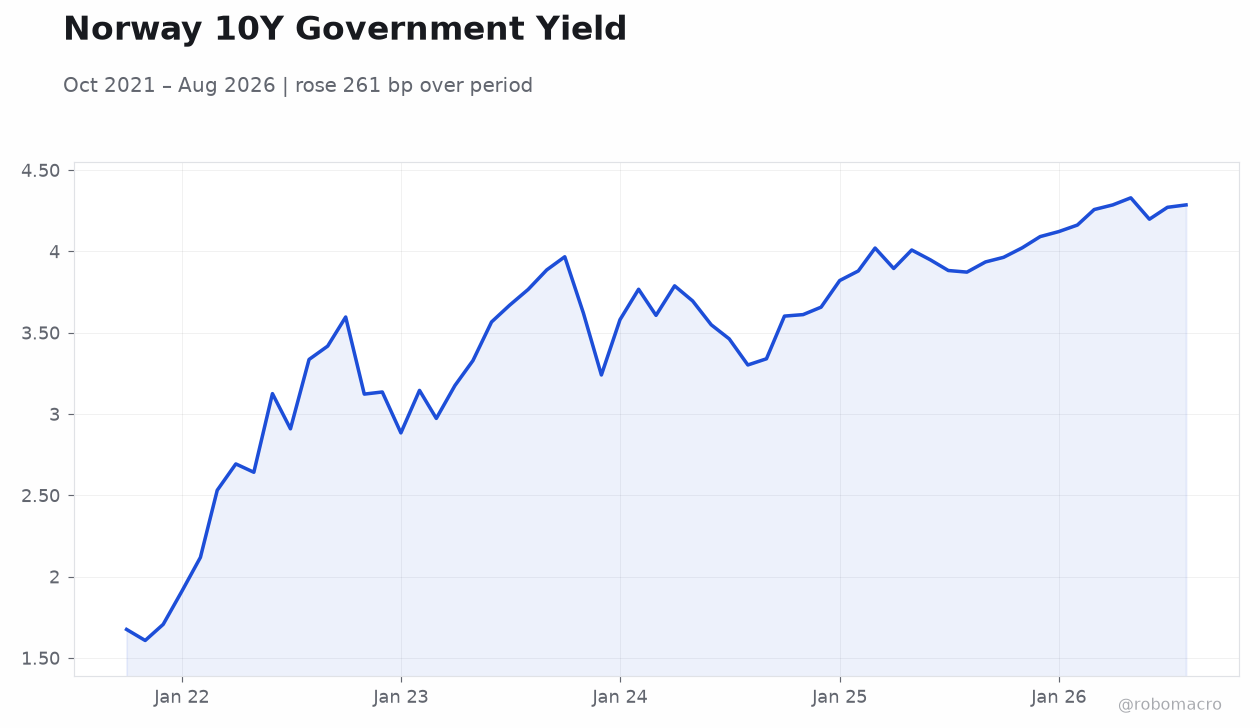
| Norway 10Y Govt Yield | 4.48% | +2 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
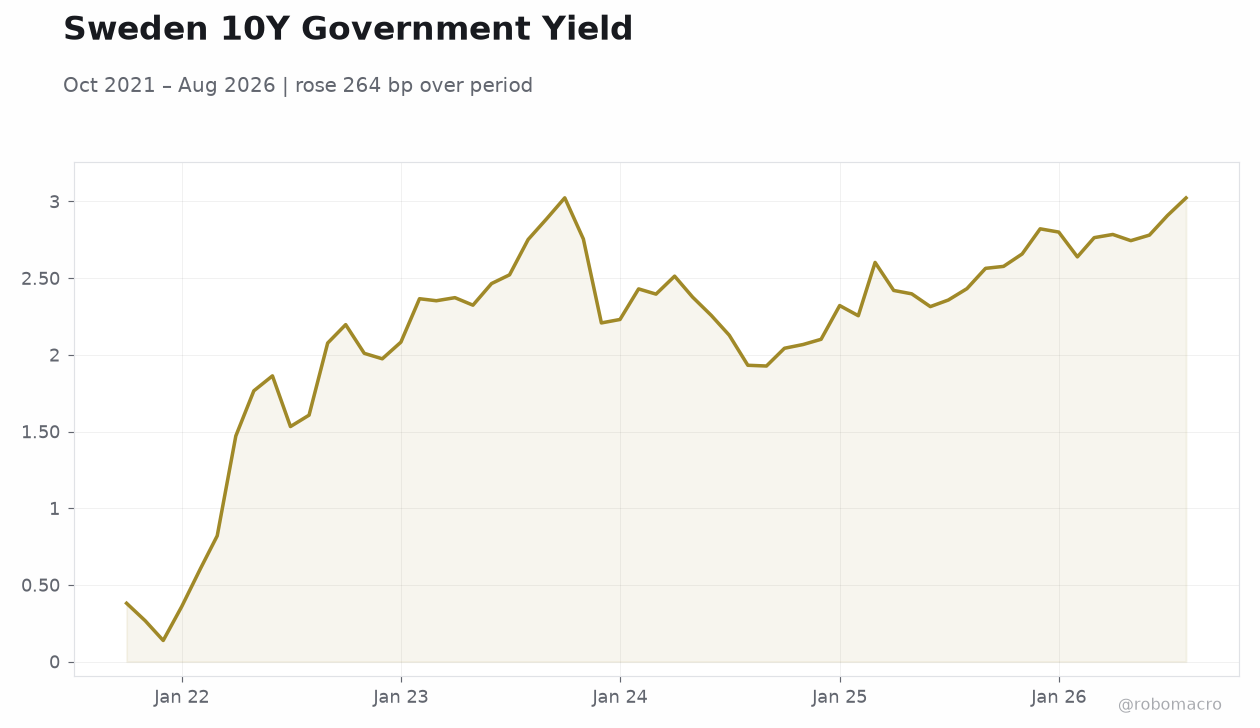 Sweden 10Y Government Yield | Type: macro_line | Yield %: 3.023 (2026-08-01) | Range: 0.138–3.024 | Trend(6pt): 0.3806,1.974,2.43,2.42,2.781,3.023
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- Riksbank set to hold rates today with Q4 hike still possible amid steady SEK outlook.
- Norges Bank faces tight vote on second 2026 rate increase as Brent crude falls 5.46%.
- Danish economy shows resilience while OMX Stockholm rises 0.30% and Oslo Bors drops 0.52%.
Yesterday's Recap
Equity markets closed mixed across the Nordic bloc on 23 September. OMX Stockholm 30 advanced 0.30% to 3,316.90 while OMX Helsinki 25 gained 0.22% to 6,599.92. Oslo Bors declined 0.52% to 2,096.59 and OMX Copenhagen 25 fell 0.47% to 1,849.85.
The Swedish krona weakened as USD/SEK rose 0.87% to 9.92 and EUR/SEK climbed 0.30% to 11.29. USD/NOK increased 0.54% to 9.49 while EUR/NOK stayed near flat at 10.80. Brent crude plunged 5.46% to 97.45, reducing near-term revenue prospects for Norway’s oil sector.
Sweden’s 10-year government yield eased 2 bp to 3.12% and Norway’s 10-year yield rose 2 bp to 4.48%. Riksbank certificate buybacks were announced and Societe Generale highlighted growth and rate outlook support for the krona. No macroeconomic data releases occurred in Sweden, Norway, Denmark or Finland.
The Day Ahead
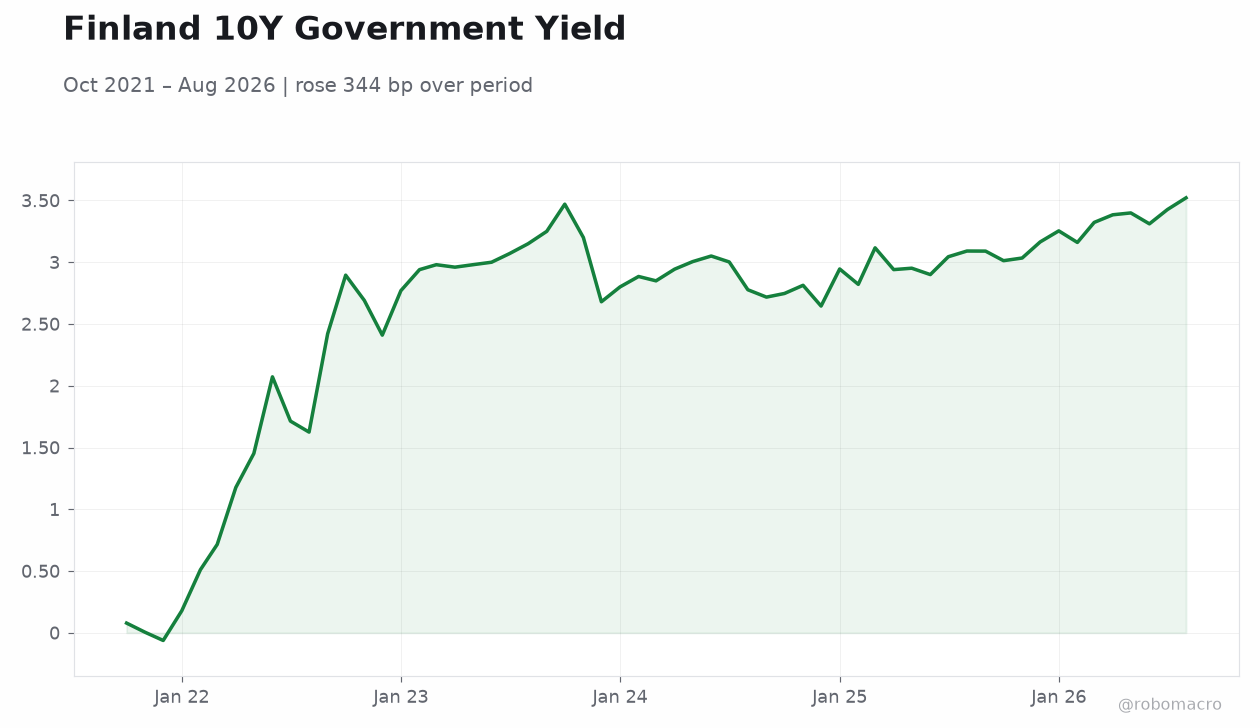
The Riksbank policy announcement scheduled for 24 September dominates the calendar with markets expecting rates to remain unchanged. No other economic releases or bond auctions are listed for Sweden, Norway, Denmark or Finland. Analysts continue to debate the possibility of a Riksbank hike later in Q4 2026.
Norges Bank’s upcoming decision draws equal attention after economists split almost evenly on a second rate increase this year. Currency strategists note that any Norges Bank pause could add downside pressure to the Norwegian krone. Danish Nationalbank commentary on the economy’s resilience against global shocks will also feature in regional coverage.
Other Economic Notes
The Danish economy continues to defy global turmoil according to Danmarks Nationalbank assessments released this week. Landshypotek Bank raised Swedish mortgage rates by 15-25 basis points on loans with one- to five-year fixed terms. Societe Generale’s latest note argues that Swedish growth and the expected policy path continue to favour the krona.
Brent’s sharp decline reduces fiscal headroom for Norway’s oil-funded budget and could ease upward pressure on the krone. No fresh housing, trade or unemployment prints emerged from any Nordic country on 23 September.