Nordics Macro Daily(Beta Mode)
Riksbank Holds, Norges Bank Hikes to 4.5%
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| OMX Stockholm 30 | 3,295.03 | +0.73% |
| Oslo Bors | 2,082.80 | -0.66% |
| OMX Copenhagen 25 | 1,836.48 | -0.11% |
| OMX Helsinki 25 | 6,521.77 | +0.06% |
| USD/SEK | 9.91 | -0.13% |
| USD/NOK | 9.50 | -0.12% |
| EUR/SEK | 11.30 | +0.04% |
| EUR/NOK | 10.83 | +0.06% |
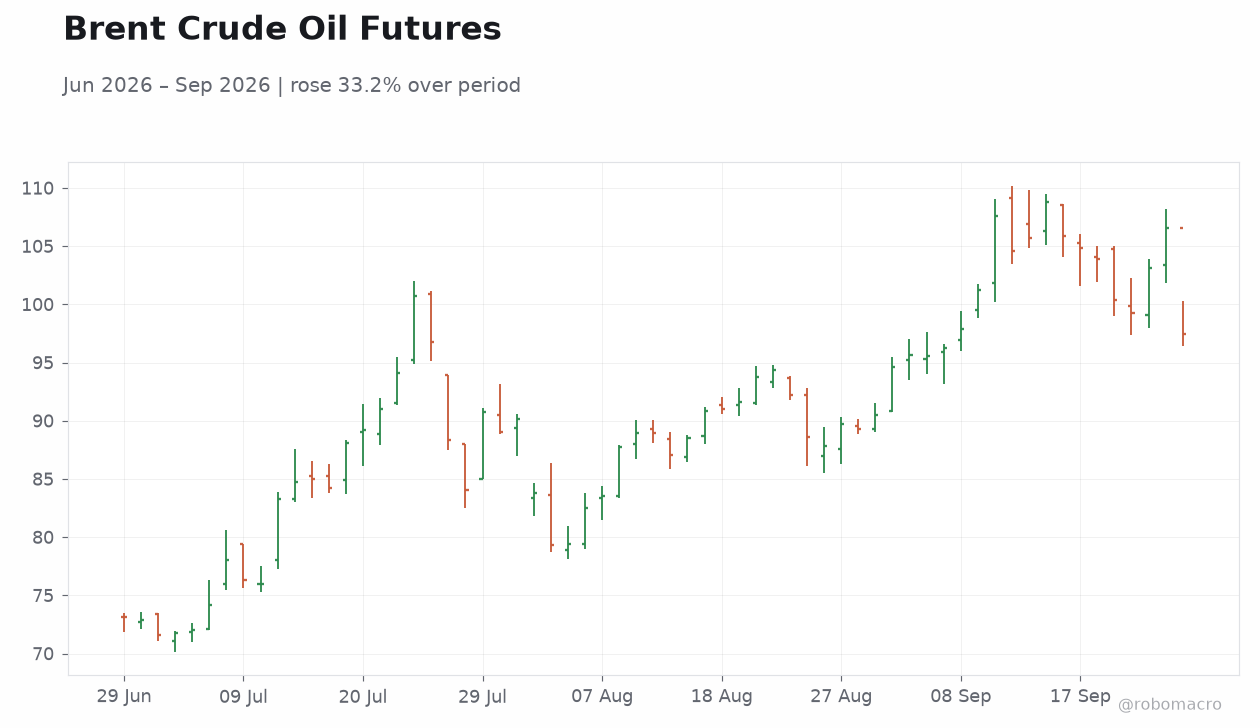
| Brent Crude | 97.44 | -8.59% |
| Gold | 4,321.20 | +0.54% |
| Bitcoin | 84,478.95 | +0.09% |
| Sweden 10Y Govt Yield | 3.28% | +3 bp |
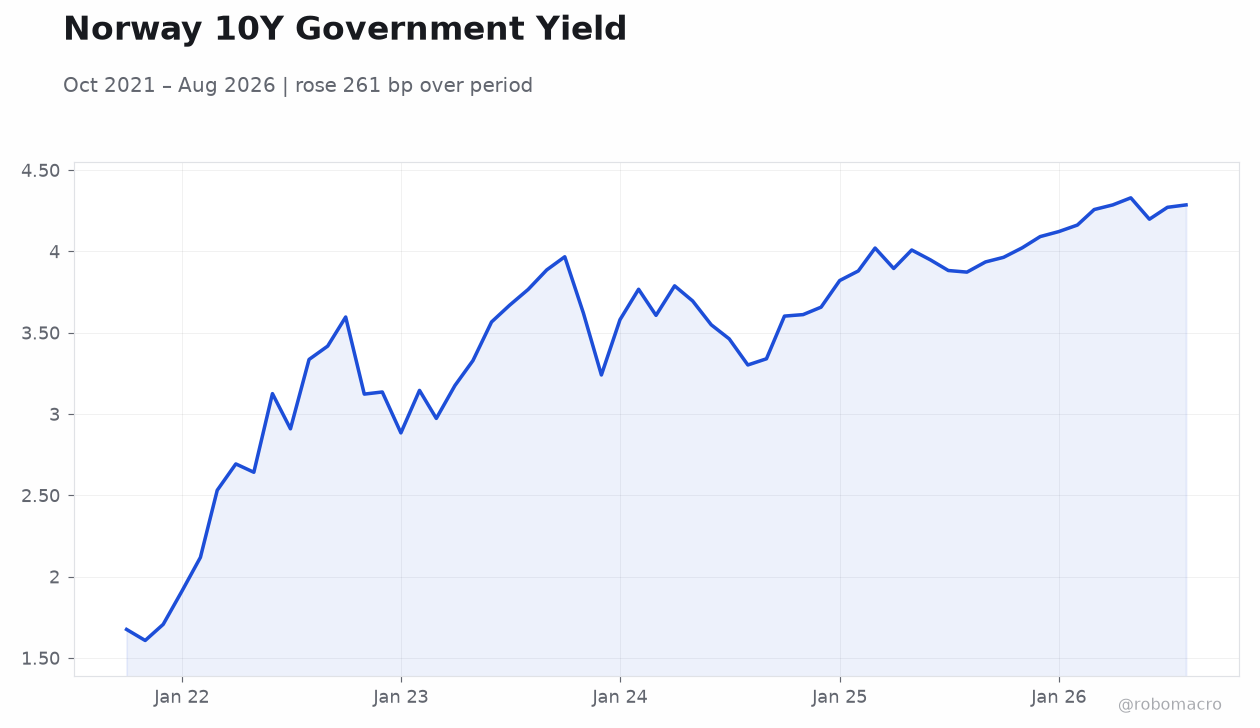
| Norway 10Y Govt Yield | 4.58% | +3 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| Riksbank Rate Decision | 1.75 | 1.75 | 1.75 |
| Norges Bank Interest Rate Decision | 4.25 | 4.50 | 4.50 |
| Riksbank Press Conference | - | - | - |
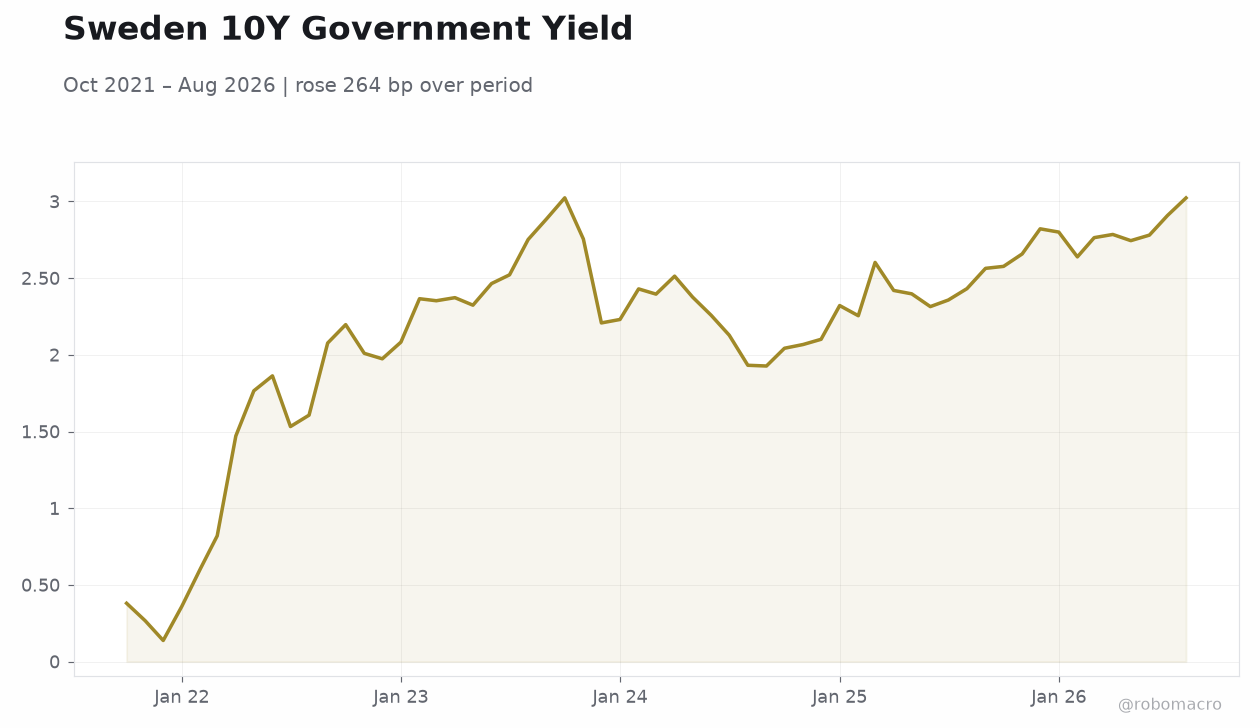 Sweden 10Y Government Yield | Type: macro_line | Yield %: 3.023 (2026-08-01) | Range: 0.138–3.024 | Trend(6pt): 0.3806,1.974,2.43,2.42,2.781,3.023
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- Riksbank holds policy rate at 1.75% as temporary VAT and fuel cuts mute inflation
- Norges Bank raises key rate 25 bp to 4.50%, triggering mortgage-rate hikes at major banks
- OMX Stockholm 30 rises 0.73% while Oslo Bors falls 0.66% amid 8.59% Brent drop
Yesterday's Recap
Sweden’s Riksbank left its policy rate unchanged at 1.75% on September 26, matching consensus, with the accompanying press conference noting that temporary VAT and fuel-tax cuts continue to suppress measured inflation and limit hawkish signals. The bank reiterated its expectation of a rate increase later this year despite a delayed inflation rebound. Norway’s Norges Bank raised its key rate by 25 bp to 4.50%, aligning with consensus and underscoring domestic inflation and wage pressures.
Several large Norwegian banks immediately passed the hike through to mortgage rates. Equity markets posted mixed closes, with the OMX Stockholm 30 advancing 0.73% to 3,295.03 while the Oslo Bors declined 0.66% to 2,082.80. The Sweden 10-year government yield rose 3 bp to 3.28% and the Norway 10-year yield also added 3 bp to 4.58%.
USD/SEK fell 0.13% to 9.91 and USD/NOK declined 0.12% to 9.50 as Brent crude plunged 8.59% to 97.44. Gold rose 0.54% to 4,321.20 while Bitcoin gained 0.09% to 84,478.95.
The Day Ahead
No high-impact Nordic data releases are scheduled for September 27 or 28. Markets will monitor follow-through commentary from the Riksbank and Norges Bank on the timing of future policy adjustments. Attention will also focus on any further mortgage-rate repricing by Norwegian lenders after yesterday’s hike.
Regional equity and fixed-income desks will track global risk sentiment given the sharp move lower in Brent. Analysts expect limited volatility in EUR/SEK and EUR/NOK absent fresh ECB or Fed signals. OMX Copenhagen 25 eased 0.11% to 1,836.48 and OMX Helsinki 25 gained 0.06% to 6,521.77, reflecting subdued regional equity breadth.
Other Economic Notes
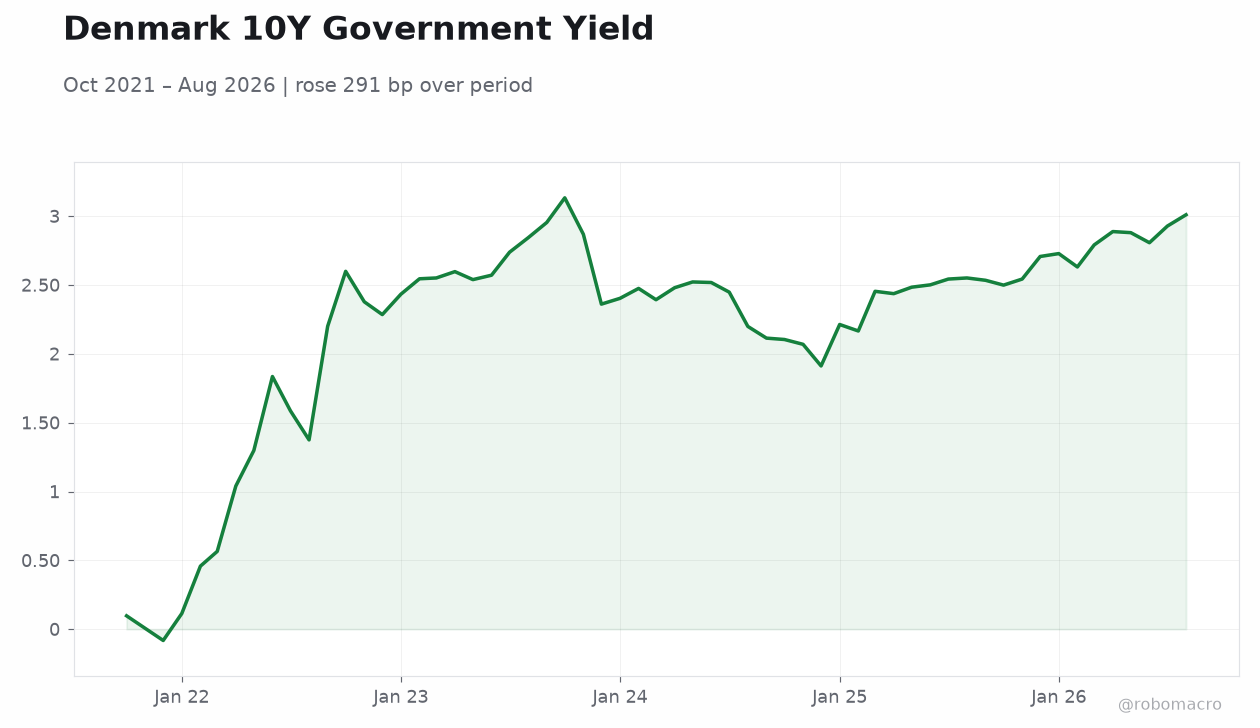
Norway’s fiscal outlook faces near-term pressure from the steep decline in Brent, which reduces oil-related revenue and exerts downward pressure on the krone despite supportive carry-trade positioning. Sweden’s export-oriented manufacturing sector continues to navigate subdued domestic inflation, with the krona sensitive to shifts in global rate expectations. Denmark’s economy remains robust, though structural imbalances in housing and labor markets present ongoing challenges.
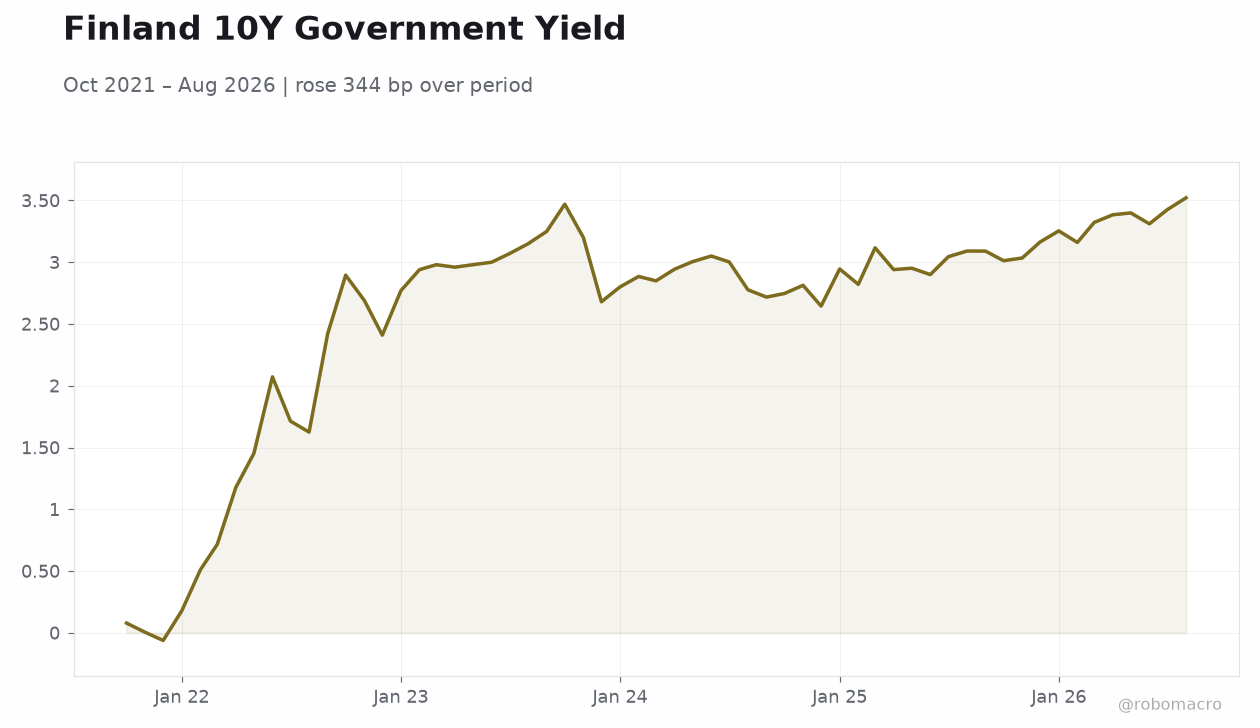
Finland’s euro-area membership means its policy stance tracks the ECB, limiting independent monetary flexibility. ↓ p.2