Nordics Macro Daily(Beta Mode)
Nordic Equities Slide Amid Quiet Data Calendar
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| OMX Stockholm 30 | 3,226.59 | -1.30% |
| Oslo Bors | 2,057.18 | -0.87% |
| OMX Copenhagen 25 | 1,793.49 | -1.68% |
| OMX Helsinki 25 | 6,376.58 | -0.77% |
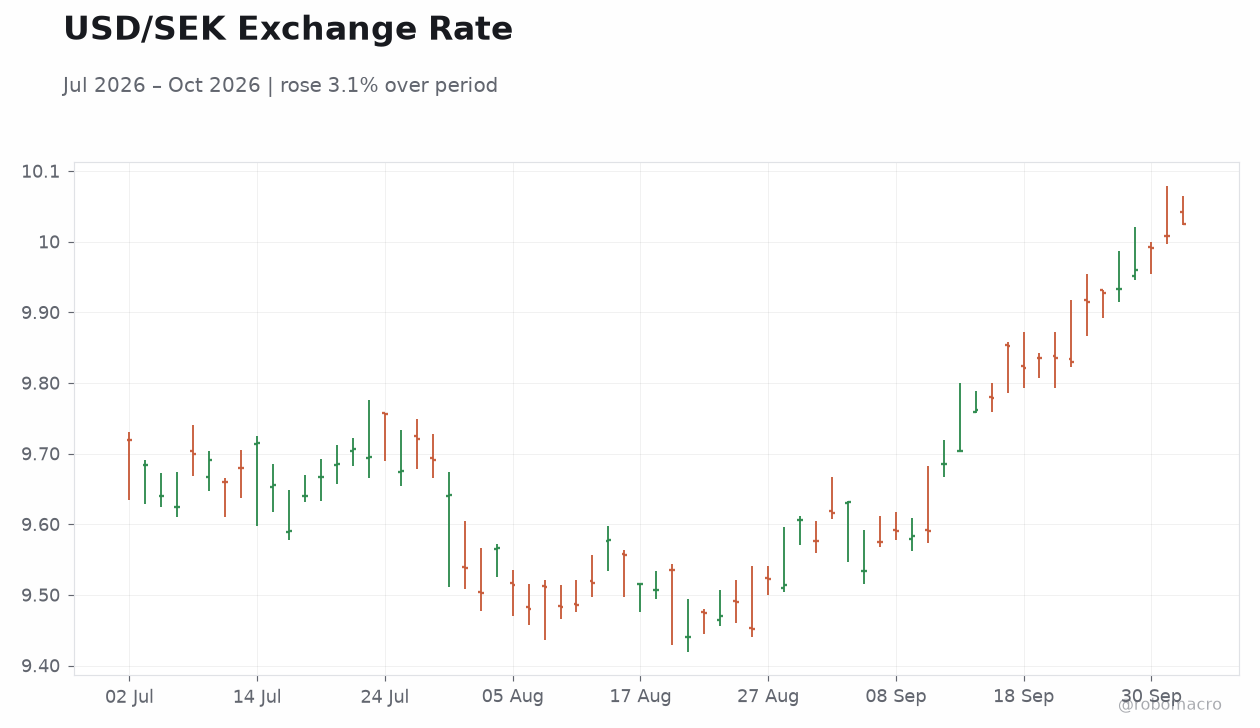
| USD/SEK | 10.03 | +0.18% |
| USD/NOK | 9.62 | -0.06% |
| EUR/SEK | 11.34 | +0.04% |
| EUR/NOK | 10.82 | -0.73% |
| Brent Crude | 102.27 | -0.04% |
| Gold | 4,211.70 | +0.22% |
| Bitcoin | 86,569.07 | +3.61% |
| Sweden 10Y Govt Yield | 3.25% | -4 bp |
| Norway 10Y Govt Yield | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
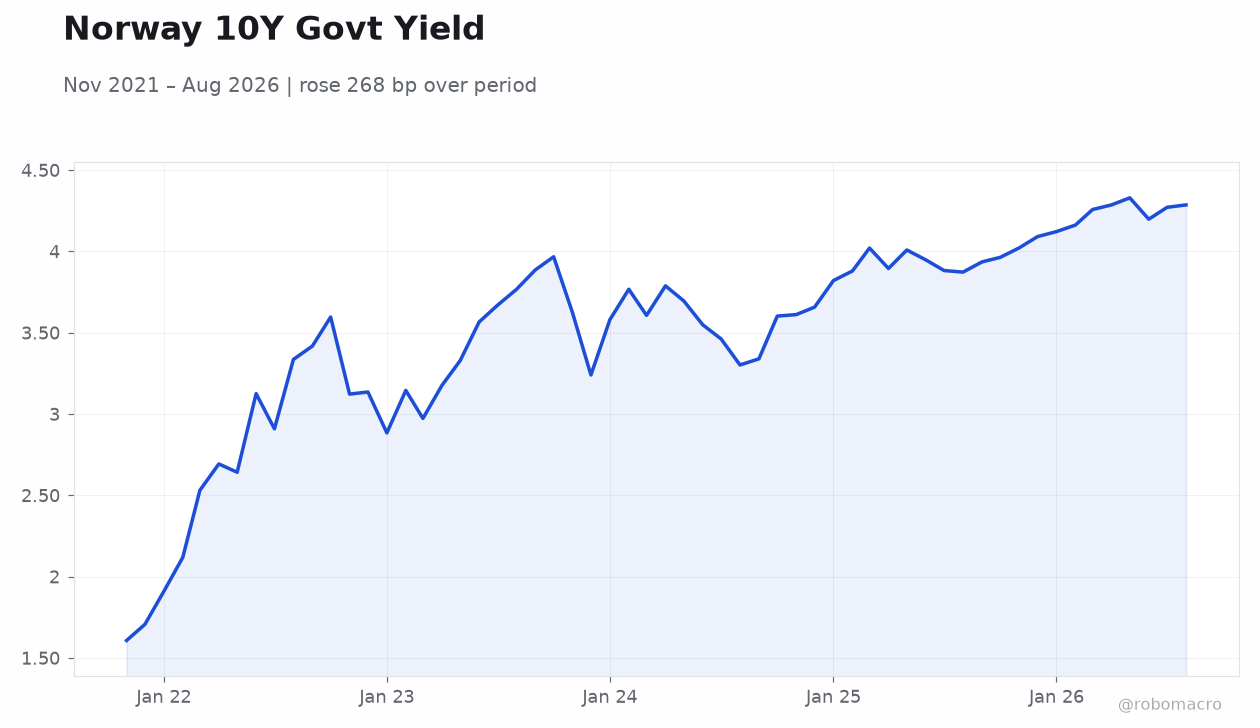
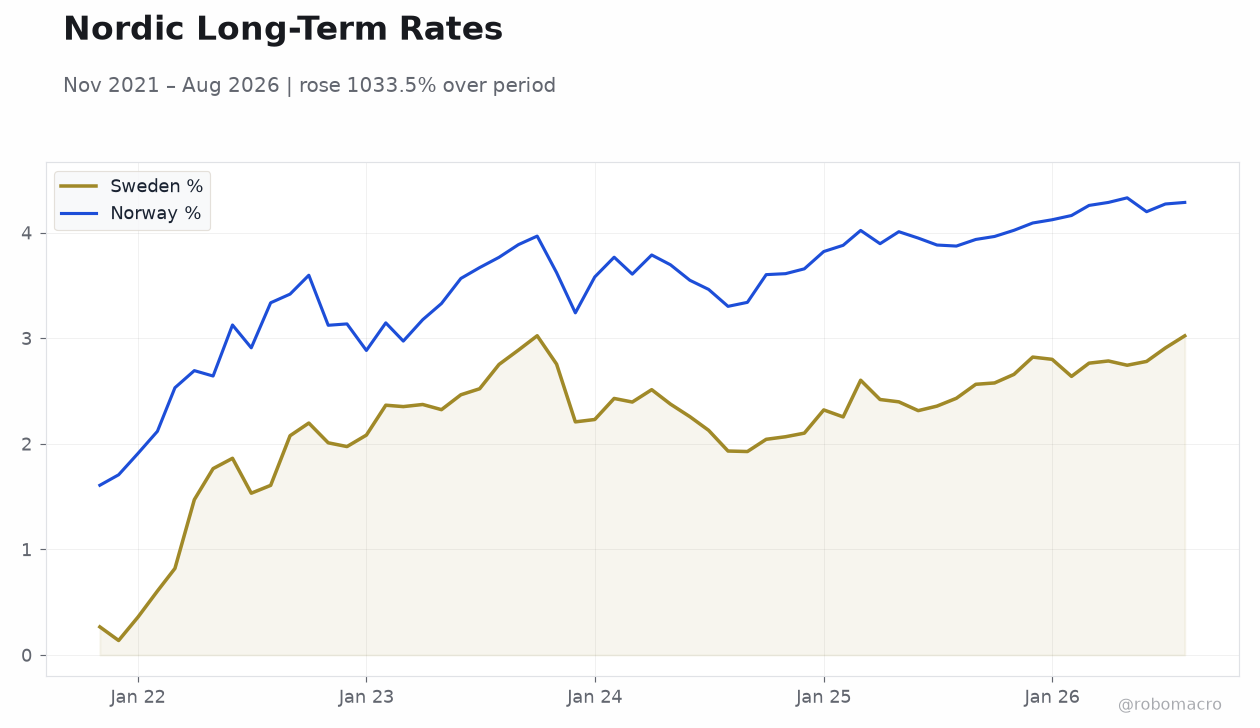 Nordic Long-Term Rates | Type: macro_line | Sweden %: 3.023 (2026-08-01) | Range: 0.138–3.024 | Trend(6pt): 0.2667,2.083,2.396,2.398,2.908,3.023 | Norway %: 4.286 (2026-08-01) | Range: 1.608–4.33 | Trend(6pt): 1.608,2.884,3.607,4.009,4.272,4.286
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- Nordic equity benchmarks fell across the board, led by Copenhagen's 1.68% drop.
- Sweden's 10-year yield eased 4 bp to 3.25% while currencies showed mixed moves.
- No macro releases emerged from Sweden, Norway, Denmark or Finland.
Yesterday's Recap
Nordic equity markets closed lower on October 1 with no offsetting data prints. The OMX Stockholm 30 declined 1.30% to 3,226.59 while Oslo Bors fell 0.87% to 2,057.18. Copenhagen posted the steepest loss as the OMX Copenhagen 25 dropped 1.68% to 1,793.49.
Helsinki eased 0.77% to 6,376.58. USD/SEK rose 0.18% to 10.03 and EUR/NOK declined 0.73% to 10.82. Sweden's 10-year government yield fell 4 bp to 3.25%.
Brent crude held near 102.27 with no fresh Norwegian production figures released. Gold advanced 0.22% to 4,211.70 and Bitcoin gained 3.61% to 86,569.07, providing limited offsets amid broader risk-off sentiment. Norway's 10-year yield data were unavailable.
The absence of any economic prints left markets without fresh domestic anchors, directing attention to external factors such as euro-area growth concerns and stable oil prices near 102.27.
The Day Ahead
The economic calendar remains empty for October 2 and 3 across all four Nordic countries. No CPI, GDP, unemployment or industrial production prints are scheduled. Riksbank and Norges Bank officials have no public appearances listed.
Bond auctions are also absent. Markets will therefore focus on external drivers including euro-area sentiment and oil-price stability. The lack of domestic data leaves policy-rate expectations unchanged in the near term.
Sweden's August CPI at 0.70% YoY and Norway's August CPI at 3.30% YoY continue to shape the backdrop without new updates. Export-oriented sectors in Sweden and Denmark remain sensitive to softer European demand signals, while Denmark's euro peg and Finland's ECB alignment limit independent policy responses. Traders will monitor any spillover from global equity caution and Brent crude movements around 102.27.
Other Economic Notes
Sweden's August CPI at 0.70% YoY continues to anchor expectations for subdued price pressures. Norway's August CPI at 3.30% YoY remains elevated yet stable, supporting the fiscal buffer provided by oil revenues. Denmark's currency peg to the euro limits independent monetary flexibility while Finland operates fully under ECB policy.
Export-oriented manufacturing sectors in Sweden and Denmark face headwinds from softer European demand. ↓ p.2