Nordics Macro Daily(Beta Mode)
Nordic Equities Rise as Swedish Debt Widens
Market Snapshot
| Asset | Level | Change |
|---|---|---|
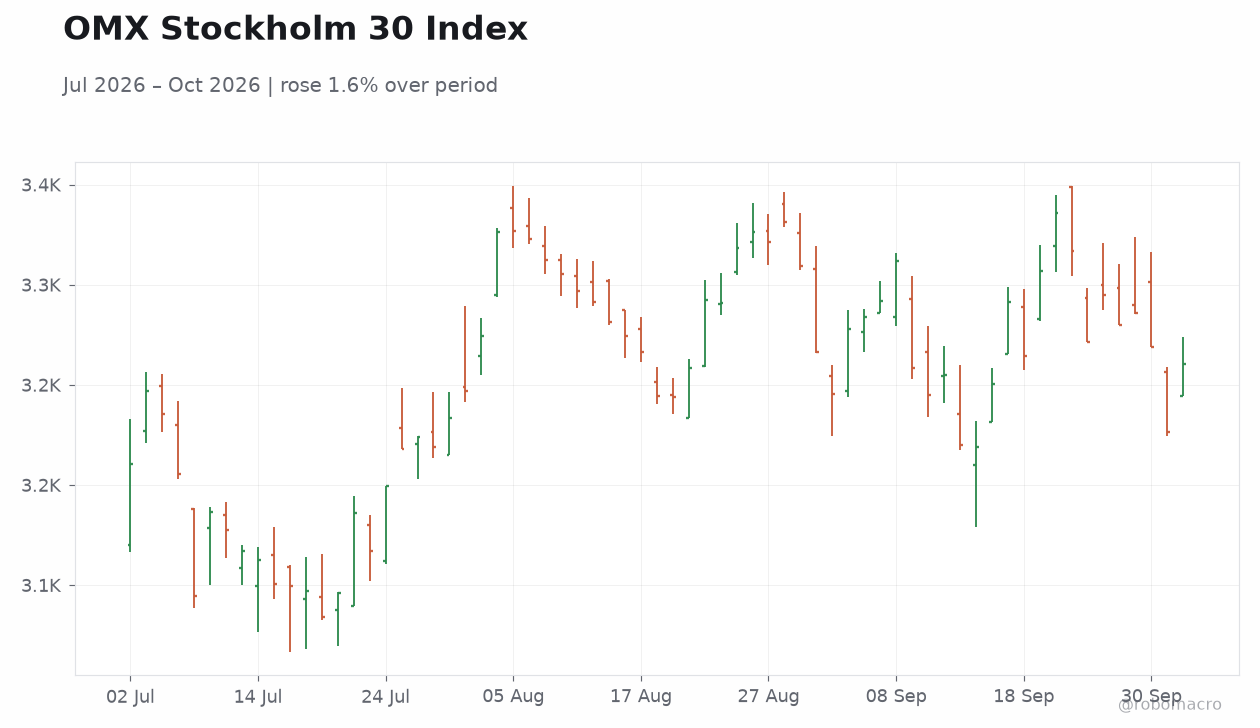
| OMX Stockholm 30 | 3,260.51 | +1.05% |
| Oslo Bors | 2,062.77 | +0.27% |
| OMX Copenhagen 25 | 1,819.11 | +1.43% |
| OMX Helsinki 25 | 6,416.21 | +0.62% |
| USD/SEK | 10.08 | +0.39% |
| USD/NOK | 9.66 | +0.32% |
| EUR/SEK | 11.28 | -0.18% |
| EUR/NOK | 10.80 | -0.26% |
| Brent Crude | 101.85 | -0.39% |
| Gold | 4,158.50 | -0.09% |
| Bitcoin | 85,563.98 | +0.94% |
| Sweden 10Y Govt Yield | 3.14% | -11 bp |
| Norway 10Y Govt Yield | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
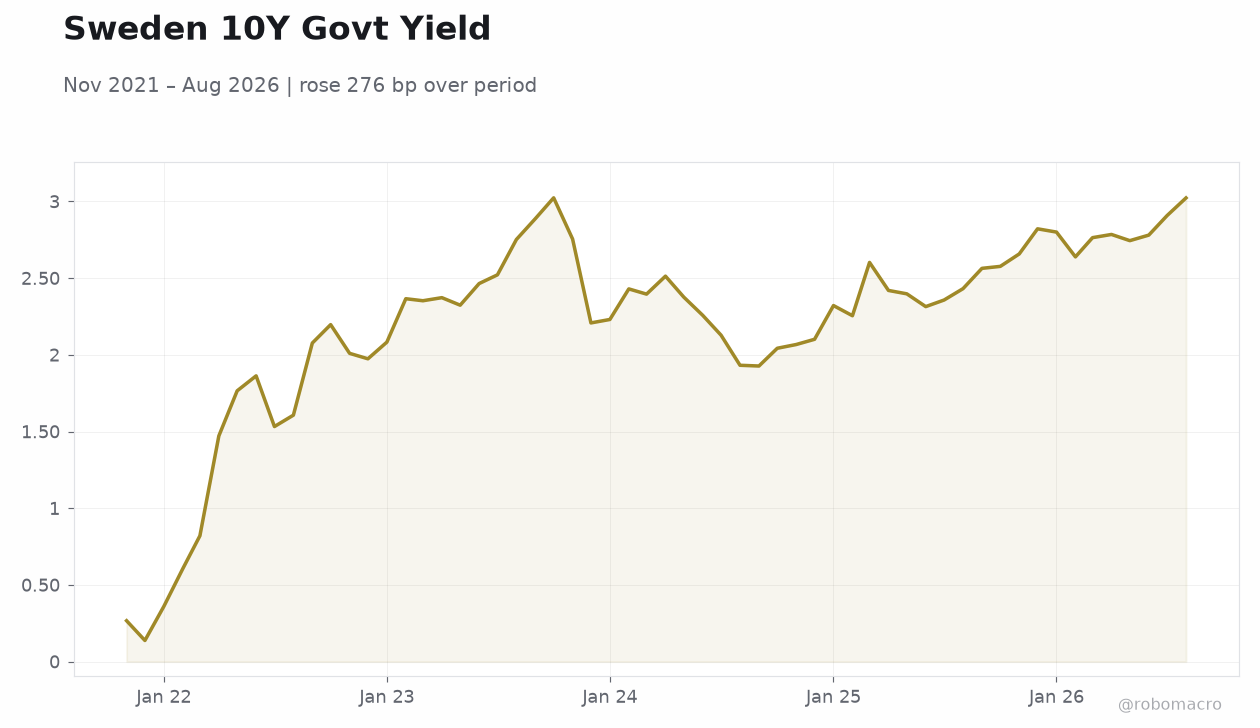 Sweden 10Y Govt Yield | Type: macro_line | Yield %: 3.023 (2026-08-01) | Range: 0.138–3.024 | Trend(6pt): 0.2667,2.083,2.396,2.398,2.908,3.023
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- Nordic equities rose with Copenhagen leading gains
- Sweden public debt increased SEK 141 billion
- Sweden 10-year yield fell 11 bp to 3.14%
Yesterday's Recap
Nordic equity markets closed higher on 4 October despite an empty data calendar. The OMX Stockholm 30 advanced 1.05% to 3,260.51 while the OMX Copenhagen 25 gained 1.43% to 1,819.11. Oslo Bors rose 0.27% to 2,062.77 and OMX Helsinki 25 added 0.62% to 6,416.21.
Sweden reported a further widening of its fiscal deficit as public debt climbed SEK 141 billion. The Riksbank released terms for upcoming government bond auctions. USD/SEK increased 0.39% to 10.08 and USD/NOK rose 0.32% to 9.66.
EUR/SEK eased 0.18% to 11.28 and EUR/NOK fell 0.26% to 10.80. Sweden’s 10-year government yield declined 11 bp to 3.14%. Brent Crude declined 0.39% to 101.85 while Gold slipped 0.09% to 4,158.50 and Bitcoin rose 0.94% to 85,563.98.
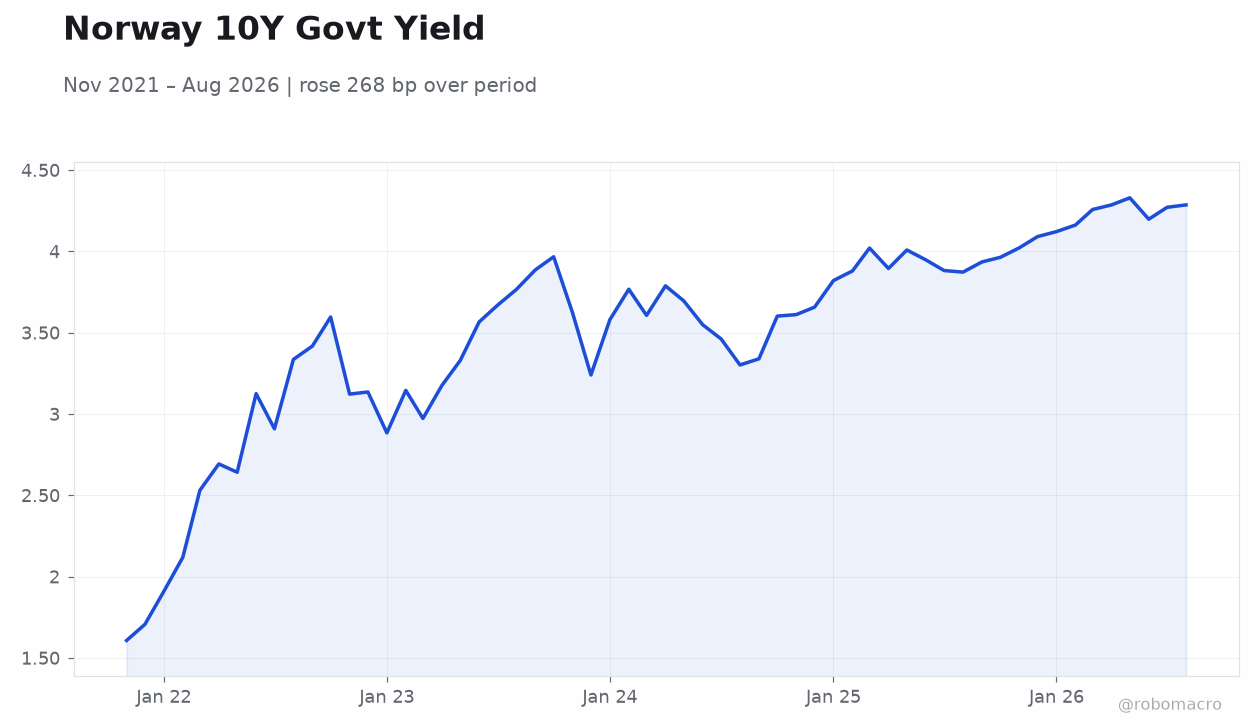
Norway 10-year yield data were unavailable.
The Day Ahead
No macroeconomic releases are scheduled for 6 October across Sweden, Norway, Denmark or Finland. Markets will monitor political negotiations in Stockholm over government formation. The Riksbank’s bond auction schedule remains in focus for liquidity effects.
Norway’s krone will continue to track Brent crude movements near 101.85. Regional investors may also watch any ECB signals that could indirectly affect Danish and Finnish rates. Equity flows are expected to stay light ahead of the weekend.
Sweden’s coast guard investigation into a suspected Baltic Sea oil spill off Gotland may draw further attention if new details emerge.
Other Economic Notes
Sweden’s public finances deteriorated further with the debt increase highlighting structural budget pressures. Political talks remain delicate as a second senior Sweden Democrat urged the party to drop its demand for ministerial posts. Sweden’s coast guard continues to investigate a suspected oil spill in the Baltic Sea off Gotland.
Export-oriented manufacturing sectors in Sweden and Denmark stay sensitive to global demand shifts. No fresh housing or industrial production prints emerged to alter near-term growth views. Norway’s unemployment rate held steady at 2.6 percent according to the latest available figures.