South Africa Macro Daily(Beta Mode)
Rand Firms as JSE Advances Ahead of CPI
Market Snapshot
| Asset | Level | Change |
|---|---|---|
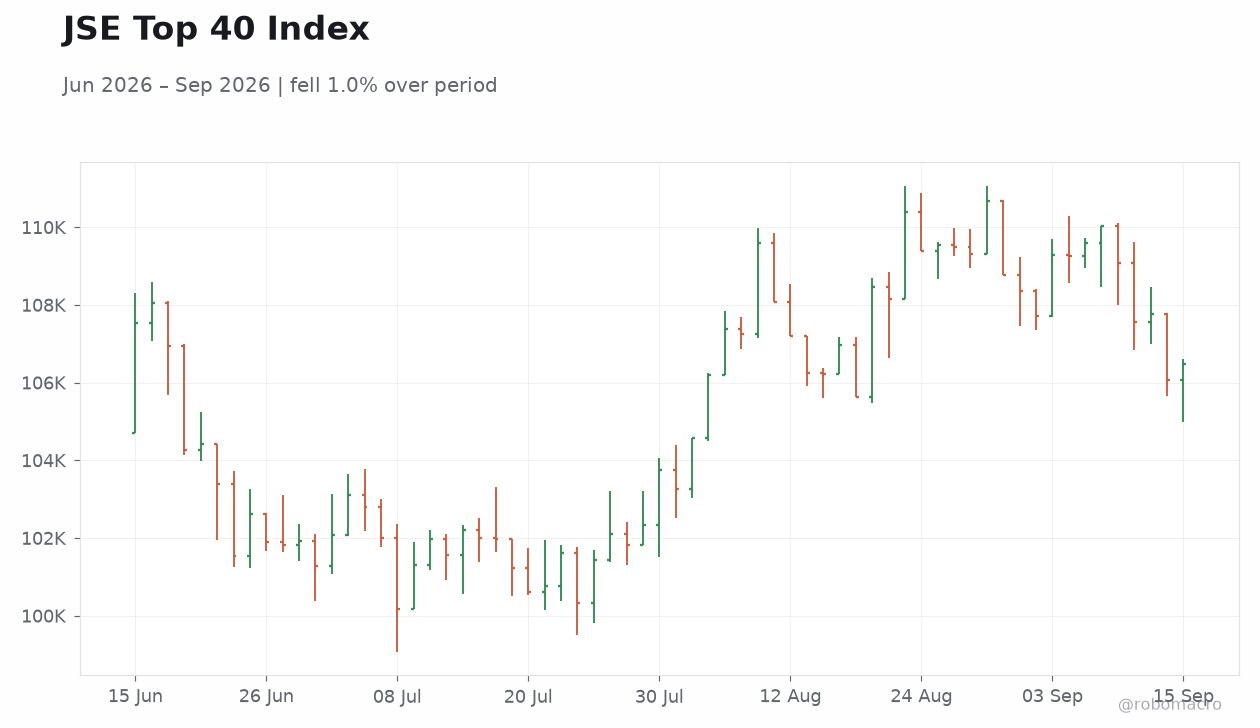
| JSE Top 40 | 106,494.60 | +0.40% |
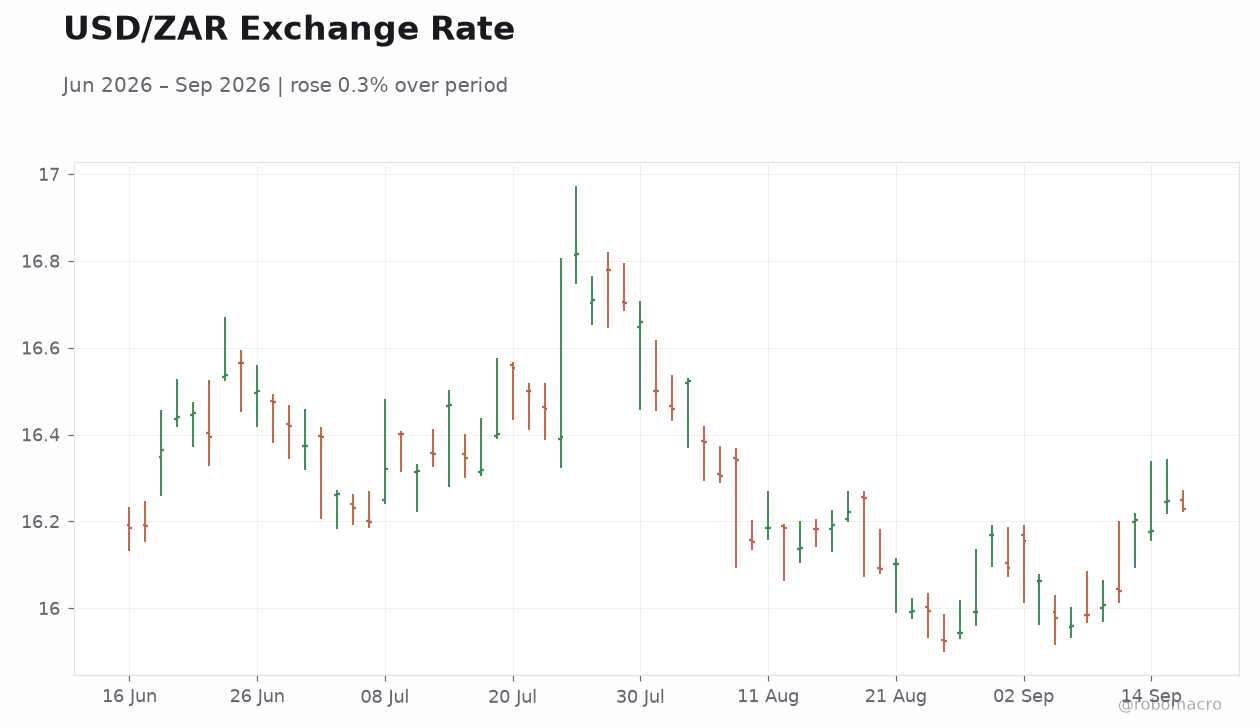
| USD/ZAR | 16.23 | -0.12% |
| EUR/ZAR | 18.73 | -0.17% |
| Platinum | 1,801.80 | +1.61% |
| Gold | 4,368.30 | +0.82% |
| Brent Crude | 107.97 | -0.72% |
| Naspers | 74,048.00 | +1.63% |
| Bitcoin | 75,842.47 | -2.97% |
| South Africa 5Y Govt Yield | 8.73% | +6 bp |
| South Africa 10Y Govt Yield | 9.01% | +7 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
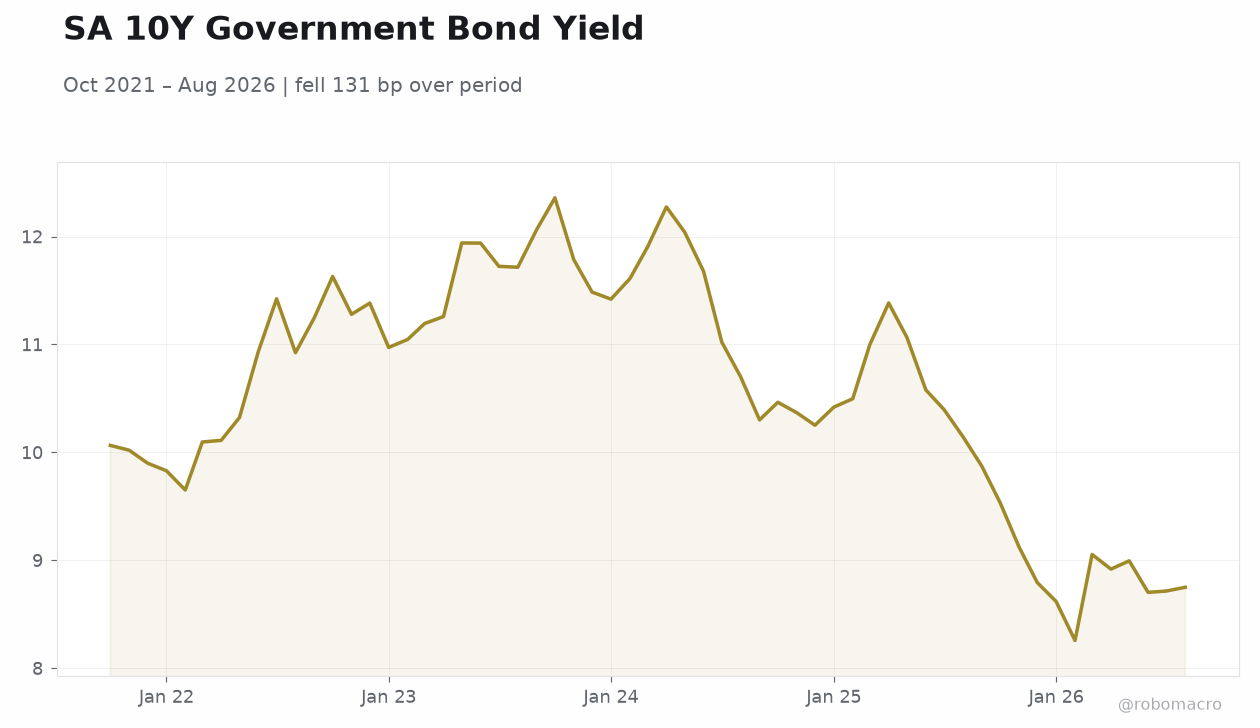 SA 10Y Government Bond Yield | Type: macro_line | Yield %: 8.75 (2026-08-01) | Range: 8.257–12.36 | Trend(6pt): 10.06,11.38,11.61,11.38,8.703,8.75
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Wednesday (2026-09-23) | |||
| Inflation Rate Month-over-Month | 0.20 | - | 04:00 |
| Inflation Rate Year-over-Year | 4.30 | - | 04:00 |
- JSE Top 40 rises 0.40% to 106,494.60 while Naspers gains 1.63%
- USD/ZAR eases 0.12% to 16.23 as 10-year yield climbs 7 bp to 9.01%
- South Africa inflation prints scheduled for 23 September
Yesterday's Recap
No economic data were released on 15 September. The JSE Top 40 advanced 0.40% to close at 106,494.60, led by a 1.63% gain in Naspers. Platinum rose 1.61% to 1,801.80 and gold added 0.82% to 4,368.30, while Brent crude fell 0.72% to 107.97.
The rand strengthened, with USD/ZAR declining 0.12% to 16.23 and EUR/ZAR dropping 0.17% to 18.73. South African government bond yields increased, the 5-year rising 6 bp to 8.73% and the 10-year adding 7 bp to 9.01%. Bitcoin declined 2.97% to 75,842.47.
The United States announced new visa restrictions targeting South African nationals accused of racism, inciting violence and uncompensated land seizures, with Secretary of State Marco Rubio confirming the policy.
The Day Ahead
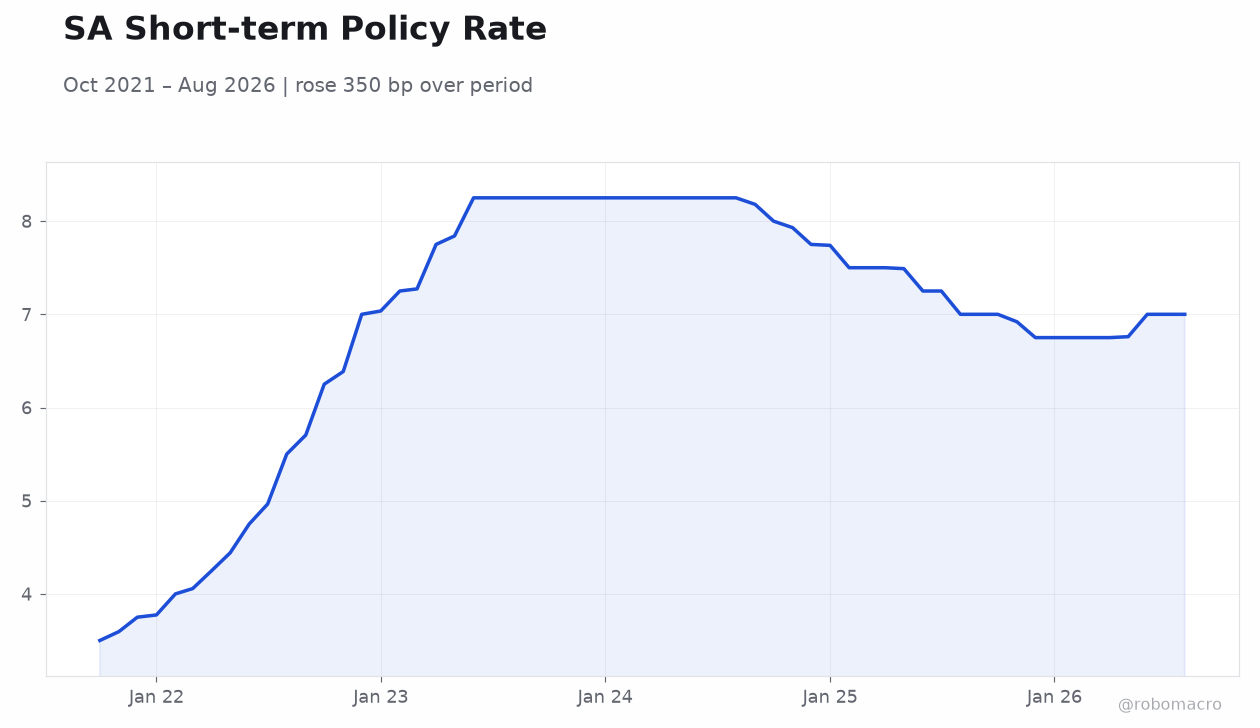
No South African data releases are scheduled for 16 September. Attention turns to the 23 September inflation prints, which will provide the next direct read on price pressures ahead of the October MPC meeting. Medium-impact MoM and YoY figures are expected to shape near-term rate expectations and rand positioning.
Market participants will also monitor any further statements from US officials on bilateral visa policy. Equity and commodity flows remain sensitive to global risk sentiment given South Africa’s mining exposure.
Other Economic Notes
The US visa restrictions add external pressure on South African sentiment and could weigh on investment and emigration trends. A judicial commission has begun hearings into alleged ties between politicians and criminal gangs, raising governance concerns that markets have long flagged. Police alerts following the discovery of a seventh woman’s body near Johannesburg highlight persistent violent crime challenges.
These domestic issues coincide with ongoing scrutiny of land policy and bilateral relations with Washington. Broader credit conditions and inflation dynamics continue to anchor local fixed-income pricing.
Global Macro News
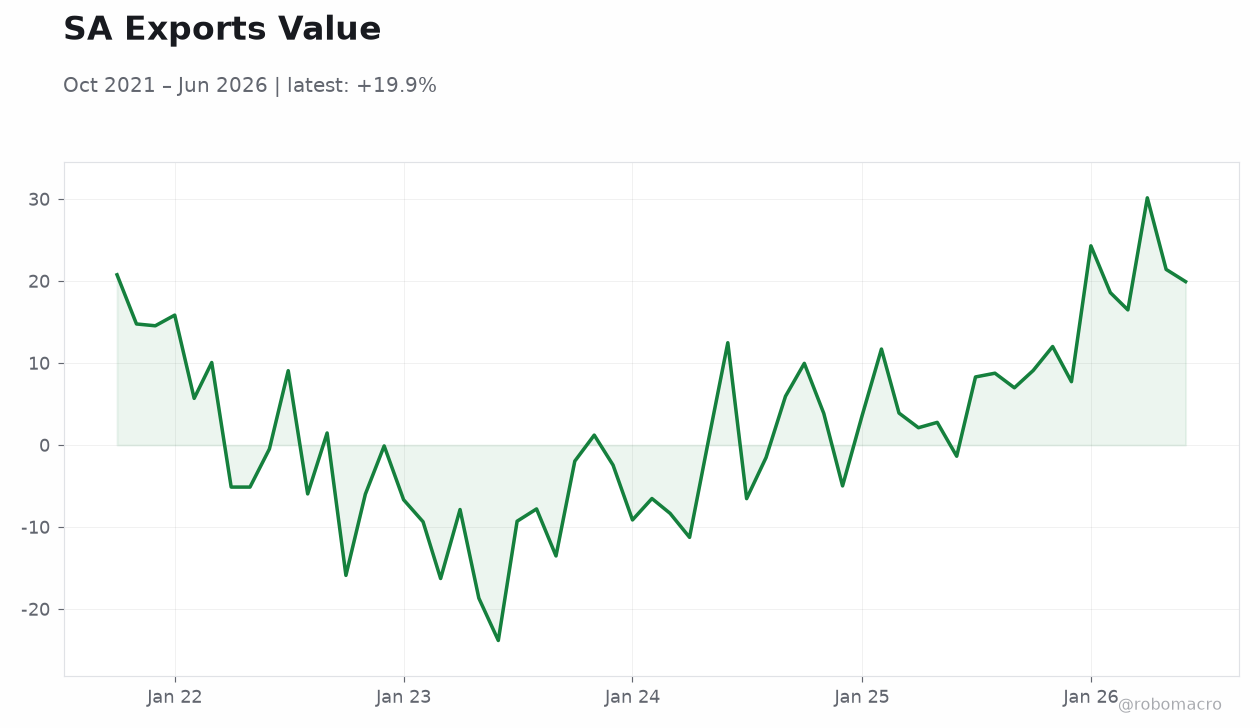
Gold and platinum strength provided support to South African mining equities and the current account outlook. Brent crude’s decline eased imported energy costs but highlighted volatility in global oil markets that affects the fiscal balance. ↓ p.2