South Africa Macro Daily(Beta Mode)
SA Yields Rise as Rand Dips Pre-Fed
Market Snapshot
| Asset | Level | Change |
|---|---|---|
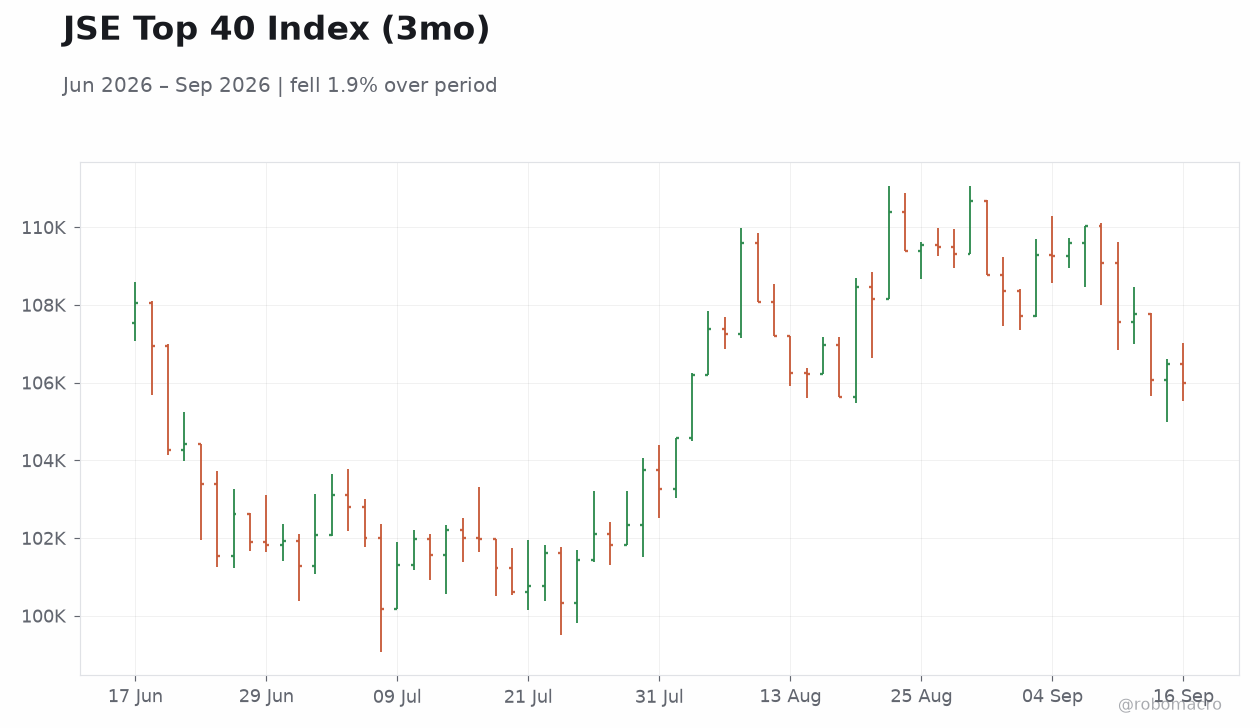
| JSE Top 40 | 105,986.20 | -0.48% |
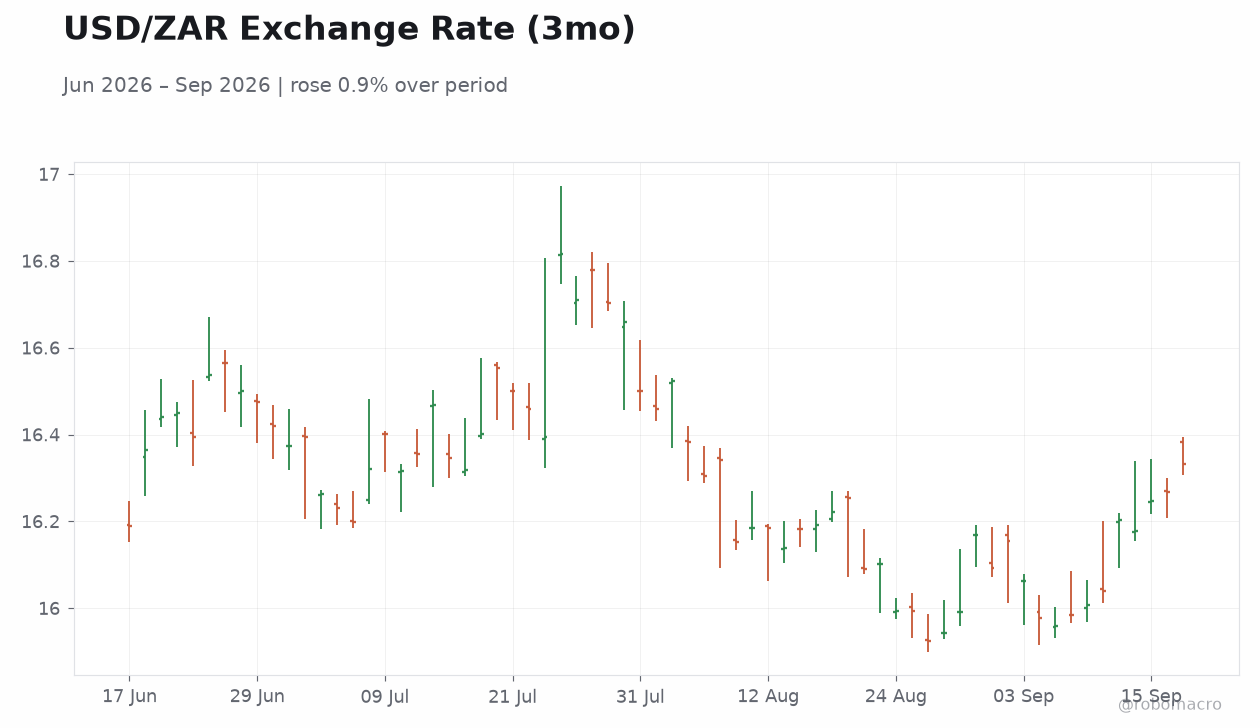
| USD/ZAR | 16.27 | +0.12% |
| EUR/ZAR | 18.73 | -0.22% |
| Platinum | 1,785.80 | +0.15% |
| Gold | 4,334.40 | -1.21% |
| Brent Crude | 105.31 | -0.49% |
| Naspers | 73,161.00 | -1.66% |
| Bitcoin | 76,315.19 | +0.93% |
| South Africa 5Y Govt Yield | 8.82% | +9 bp |
| South Africa 10Y Govt Yield | 9.11% | +10 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
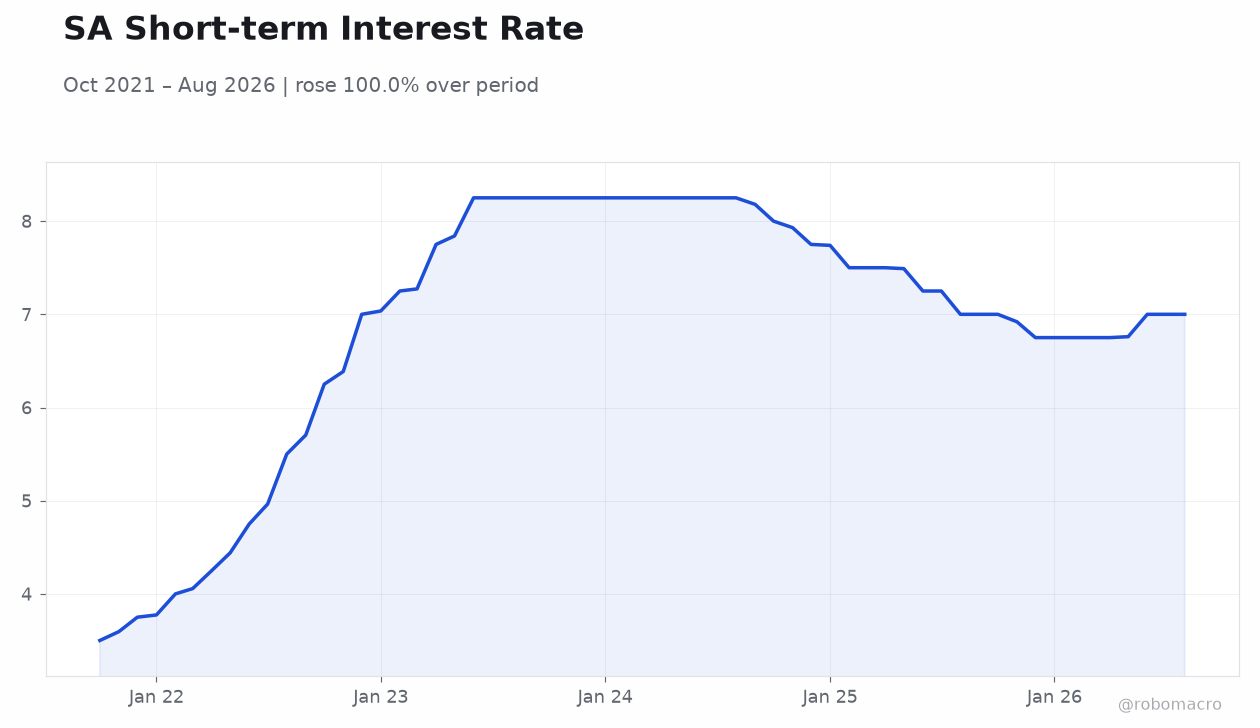
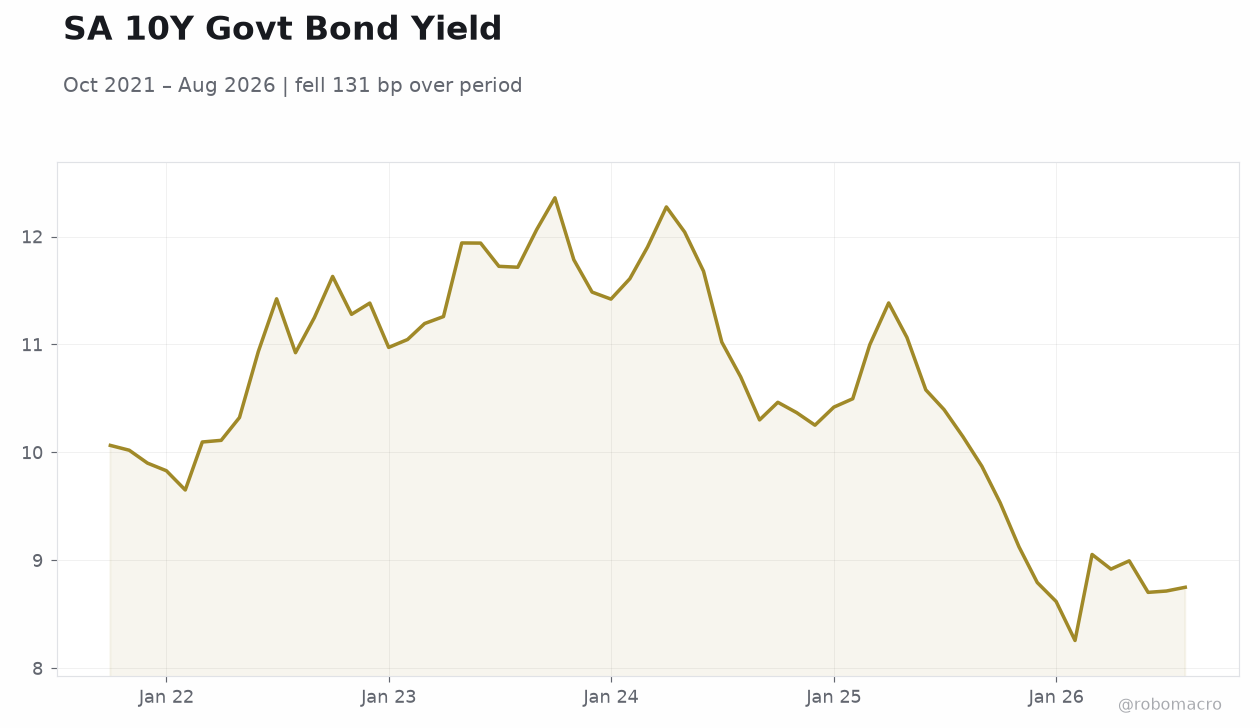 SA 10Y Govt Bond Yield | Type: macro_line | Yield %: 8.75 (2026-08-01) | Range: 8.257–12.36 | Trend(6pt): 10.06,11.38,11.61,11.38,8.703,8.75
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Wednesday (2026-09-23) | |||
| Inflation Rate Month-over-Month | 0.20 | - | 04:00 |
| Inflation Rate Year-over-Year | 4.30 | - | 04:00 |
- JSE Top 40 slips 0.48% while 10-year yield climbs 10 bp to 9.11%.
- USD/ZAR edges 0.12% higher to 16.27 ahead of Fed decision.
- Inflation Rate MoM and YoY releases scheduled for 23 September.
Yesterday's Recap
South African markets recorded no economic data releases on 16 September. The JSE Top 40 closed at 105,986.20, down 0.48% for the session. USD/ZAR finished at 16.27 after a 0.12% gain while EUR/ZAR eased 0.22% to 18.73.
Platinum advanced 0.15% to 1,785.80 but gold declined 1.21% to 4,334.40 and Brent Crude fell 0.49% to 105.31. The South Africa 5-year government yield rose 9 bp to 8.82% and the 10-year yield increased 10 bp to 9.11%. Bitcoin gained 0.93% to 76,315.19.
Naspers dropped 1.66% to 73,161.00 amid the broader equity retreat.
The Day Ahead
No South African data releases are scheduled for 17 September. Attention turns to the 23 September prints for Inflation Rate Month-over-Month and Year-over-Year. The prior MoM reading stood at 0.2% and the YoY figure at 4.3%.
These medium-impact releases will provide the next direct gauge of price pressures ahead of the next MPC meeting. Market participants will also monitor any updates on US visa restrictions and their potential effect on bilateral trade sentiment. Rand volatility is likely to remain elevated until the Fed policy decision clarifies global rate expectations.
Other Economic Notes
US visa restrictions targeting certain South African officials over land-reform policies have added to external uncertainty for the rand and capital flows. President Cyril Ramaphosa’s withdrawal from official duties due to health concerns follows the BRICS summit and may delay domestic policy announcements. Broader concerns over artificial intelligence adoption are surfacing in South Africa but have yet to register in near-term growth or employment data.
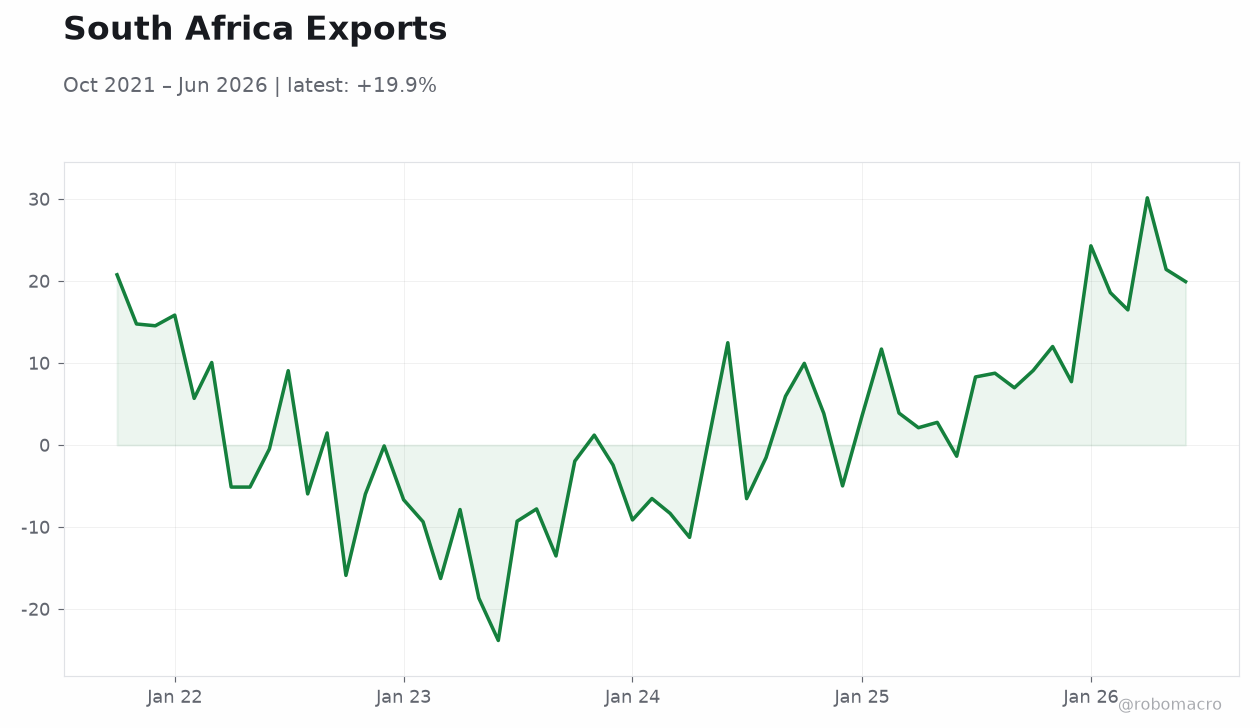
The subdued rand reflects caution ahead of the Fed meeting rather than any immediate shift in domestic fundamentals. Mining equities remain sensitive to global commodity prices, with platinum showing modest resilience while gold prices retreated.
Global Macro News
The South African rand remained under pressure as markets positioned for the upcoming Federal Reserve decision. Brent Crude at 105.31 and gold at 4,334.40 continue to influence the terms of trade for South Africa’s resource exports. ↓ p.2