South Africa Macro Daily(Beta Mode)
Yields Ease on Rate Outlook Signals
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| JSE Top 40 | 106,553.40 | +0.54% |
| USD/ZAR | 16.38 | +0.67% |
| EUR/ZAR | 18.78 | +0.09% |
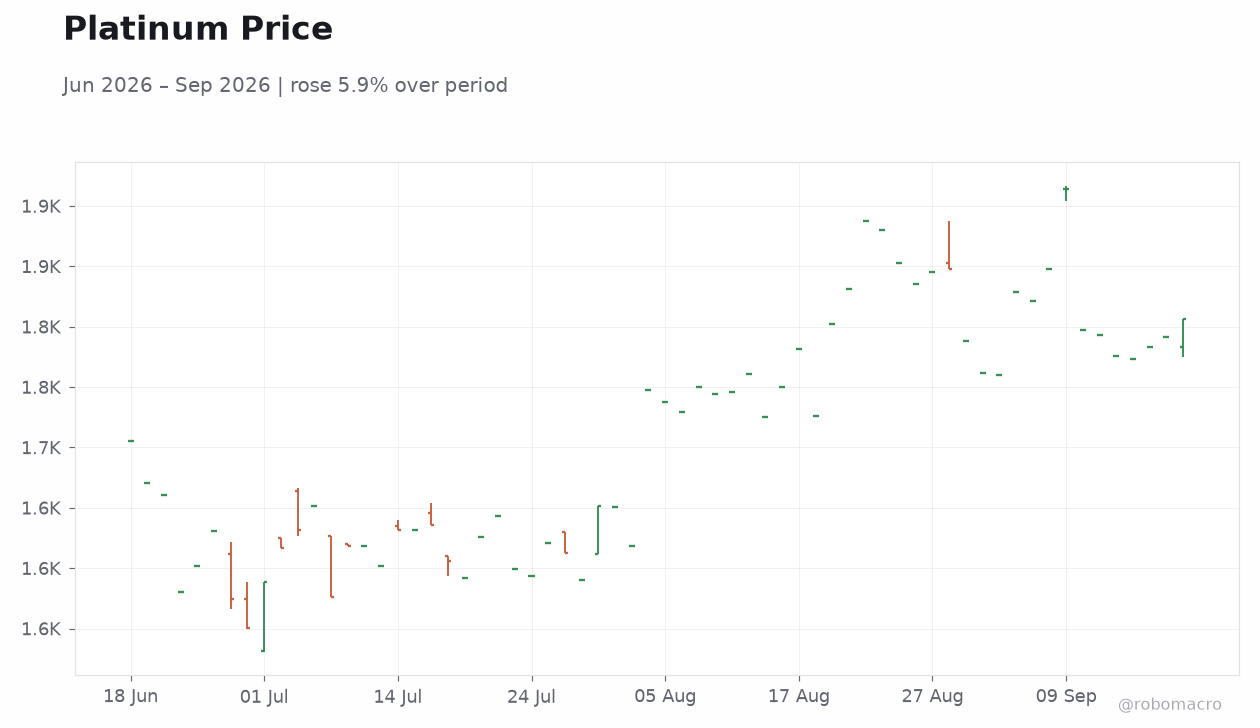
| Platinum | 1,806.30 | +0.83% |
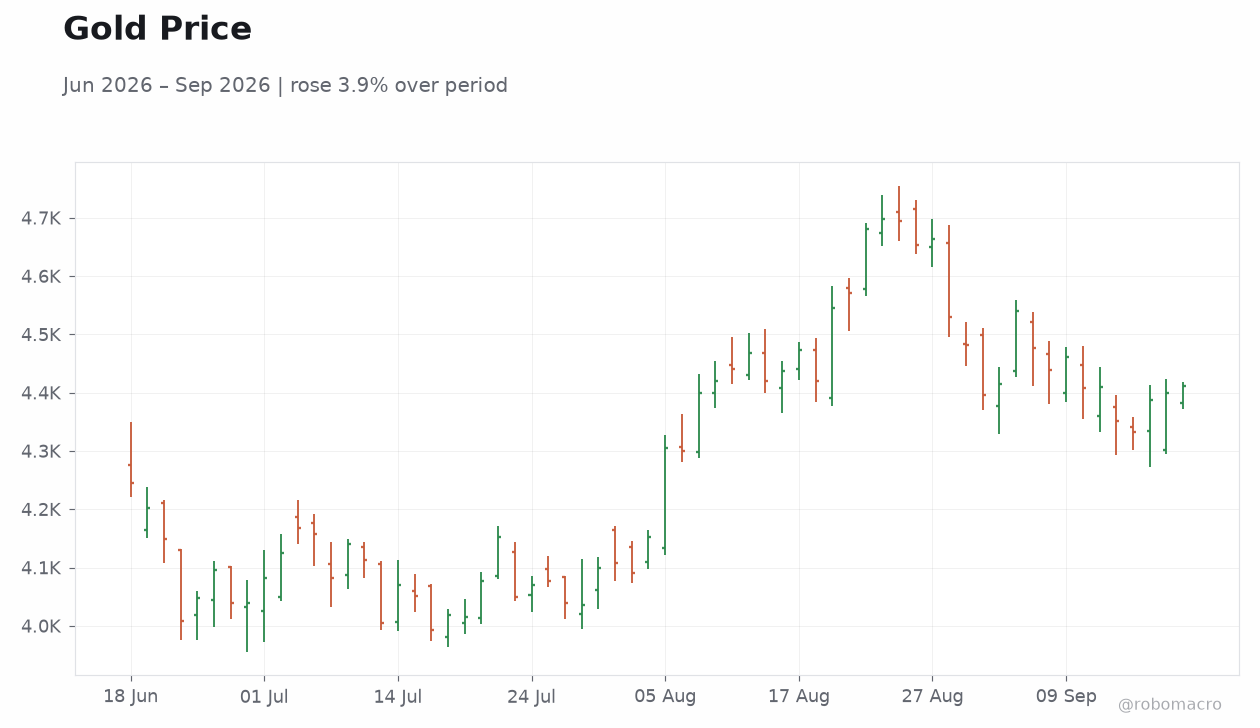
| Gold | 4,413.00 | +0.30% |
| Brent Crude | 103.39 | -1.36% |
| Naspers | 71,880.00 | -1.48% |
| Bitcoin | 77,483.91 | +1.75% |
| South Africa 5Y Govt Yield | 8.75% | -7 bp |
| South Africa 10Y Govt Yield | 9.03% | -8 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
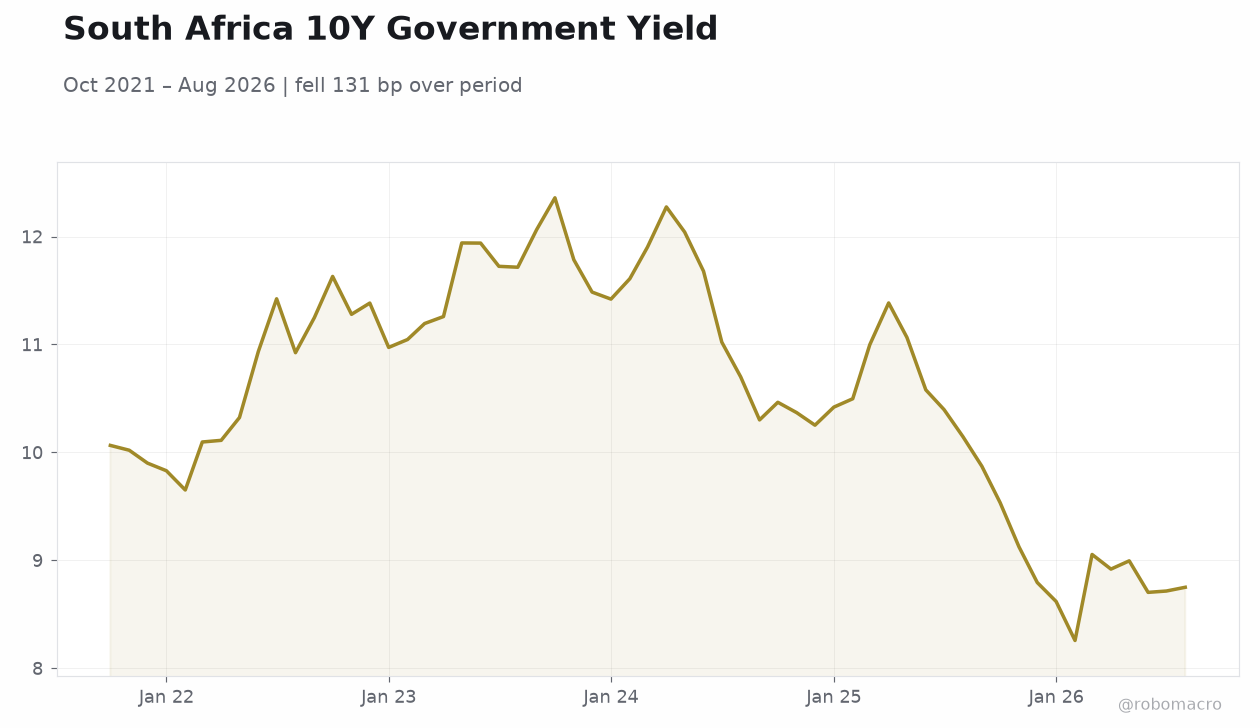 South Africa 10Y Government Yield | Type: macro_line | Percent: 8.75 (2026-08-01) | Range: 8.257–12.36 | Trend(6pt): 10.06,11.38,11.61,11.38,8.703,8.75
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- South African 5Y and 10Y government yields declined 7 bp and 8 bp to 8.75% and 9.03% respectively.
- JSE Top 40 advanced 0.54% to 106,553.40 while platinum and gold posted gains of 0.83% and 0.30%.
- USD/ZAR rose 0.67% to 16.38 amid reports of positive interest-rate developments.
Yesterday's Recap
South African markets recorded no economic data releases on 17 September. The JSE Top 40 closed higher at 106,553.40, supported by a 0.83% rise in platinum to 1,806.30 and a 0.30% gain in gold to 4,413.00. Brent crude fell 1.36% to 103.39 while Bitcoin advanced 1.75% to 77,483.91.
Government bond yields compressed, with the 5-year yield easing 7 bp to 8.75% and the 10-year yield declining 8 bp to 9.03%. The rand posted modest depreciation, with USD/ZAR finishing at 16.38 and EUR/ZAR at 18.78. Naspers declined 1.48% to 71,880.00.
News headlines highlighted favourable interest-rate signals and rand firmness without detailing specific catalysts. President Ramaphosa withdrew from public engagements after falling ill on return from the BRICS summit in India, though no direct market reaction was evident.
The Day Ahead
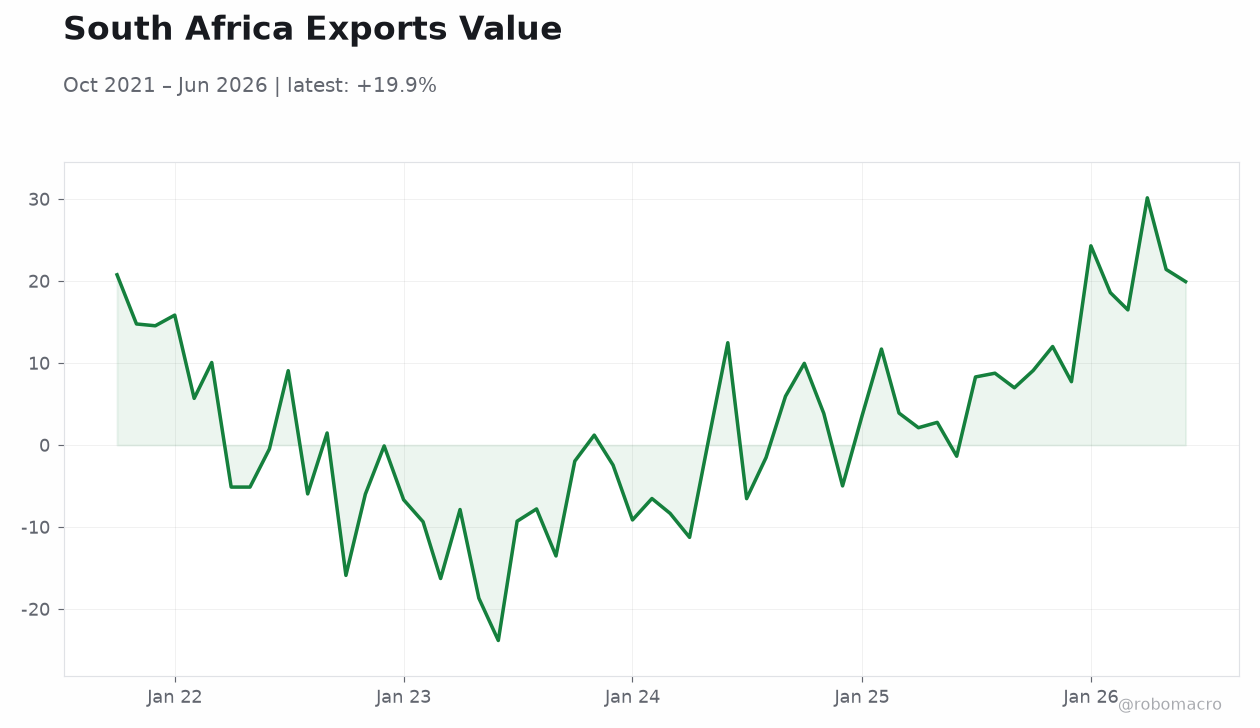
The economic calendar remains empty for 18 September with no scheduled releases or SARB events. Market participants will monitor commodity price movements, particularly platinum and gold, given their influence on export revenues and the current account. Attention may also turn to any follow-up statements from the BRICS summit or updates on President Ramaphosa’s schedule.
Global risk sentiment and US dollar direction will likely dictate rand trading ranges around the 16.38 level. Energy supply developments remain a latent focus even in the absence of fresh load-shedding reports. Investors will watch for any clarification on the string of recent femicide cases and their potential effect on domestic sentiment.
Other Economic Notes
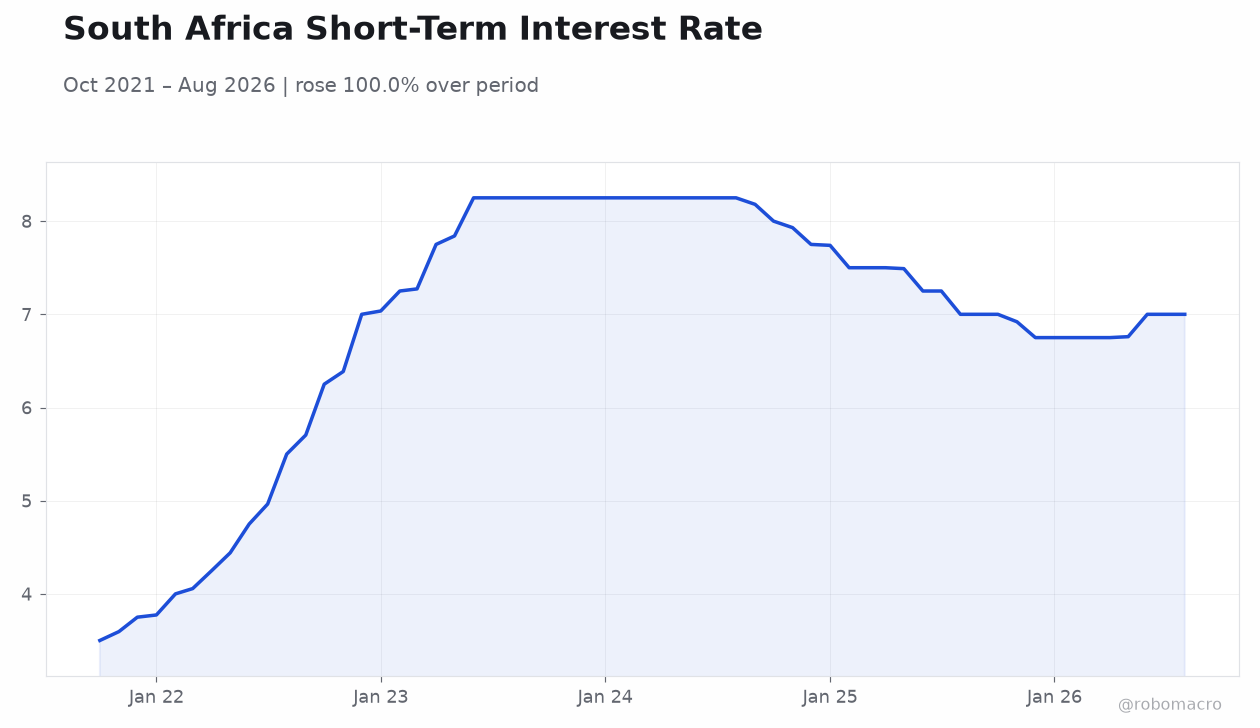
Headlines pointed to constructive interest-rate news that appears to have supported the local bond market and eased yields. The absence of fresh inflation or growth prints leaves the 7.00% repo rate as the prevailing policy anchor. Equity performance remained concentrated, with Naspers lagging the broader Top 40 index.
Mining-sector commodity prices provided a partial offset to softer Brent crude, underscoring South Africa’s exposure to precious metals. Broader themes of fiscal discipline and external financing costs continue to shape investor positioning ahead of any policy signals. ↓ p.2