South Africa Macro Daily(Beta Mode)
Rand Holds Steady Ahead of SARB Decision
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| JSE Top 40 | 105,242.10 | -1.23% |
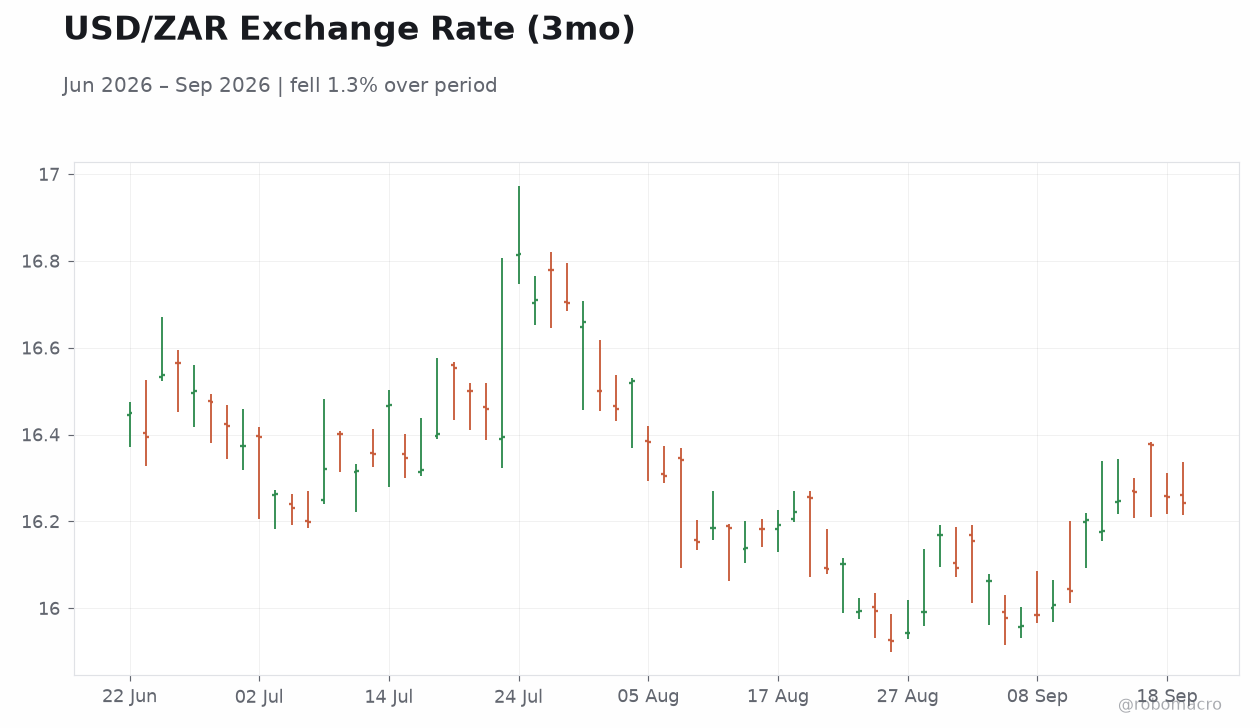
| USD/ZAR | 16.26 | -0.74% |
| EUR/ZAR | 18.65 | -0.69% |
| Platinum | 1,800.70 | -0.16% |
| Gold | 4,384.90 | -0.90% |
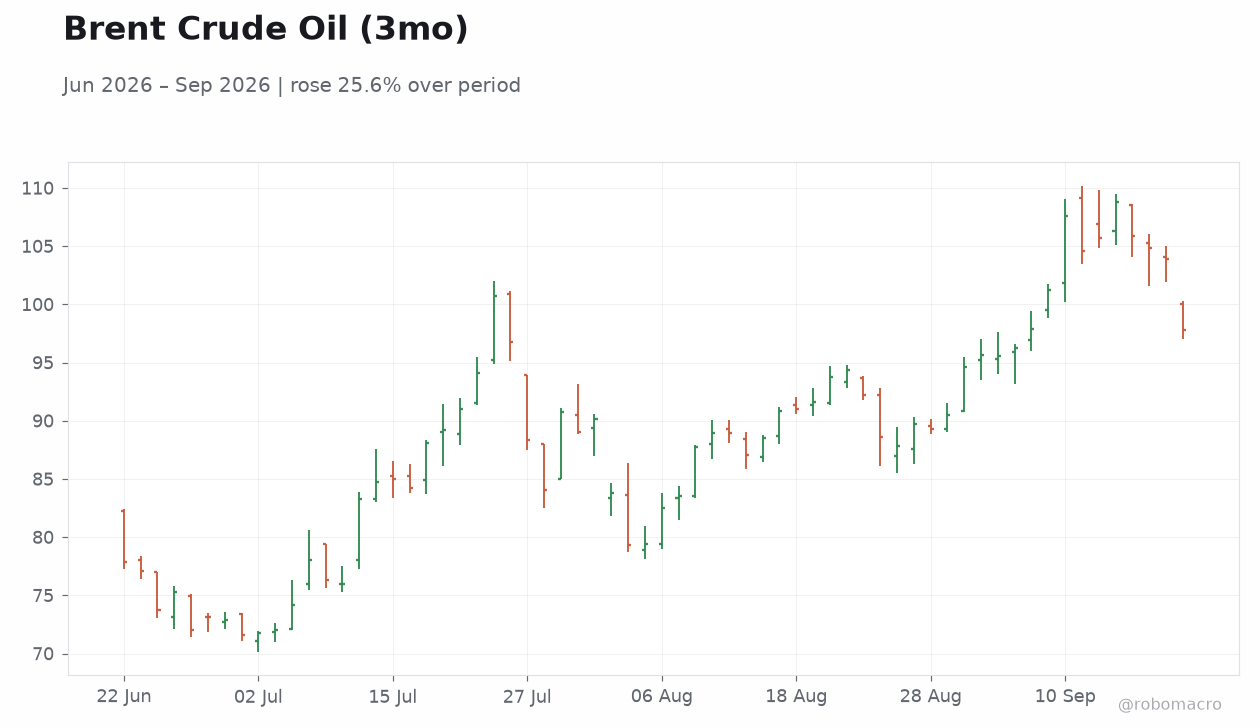
| Brent Crude | 97.71 | -5.93% |
| Naspers | 71,460.00 | -0.29% |
| Bitcoin | 81,494.54 | +0.32% |
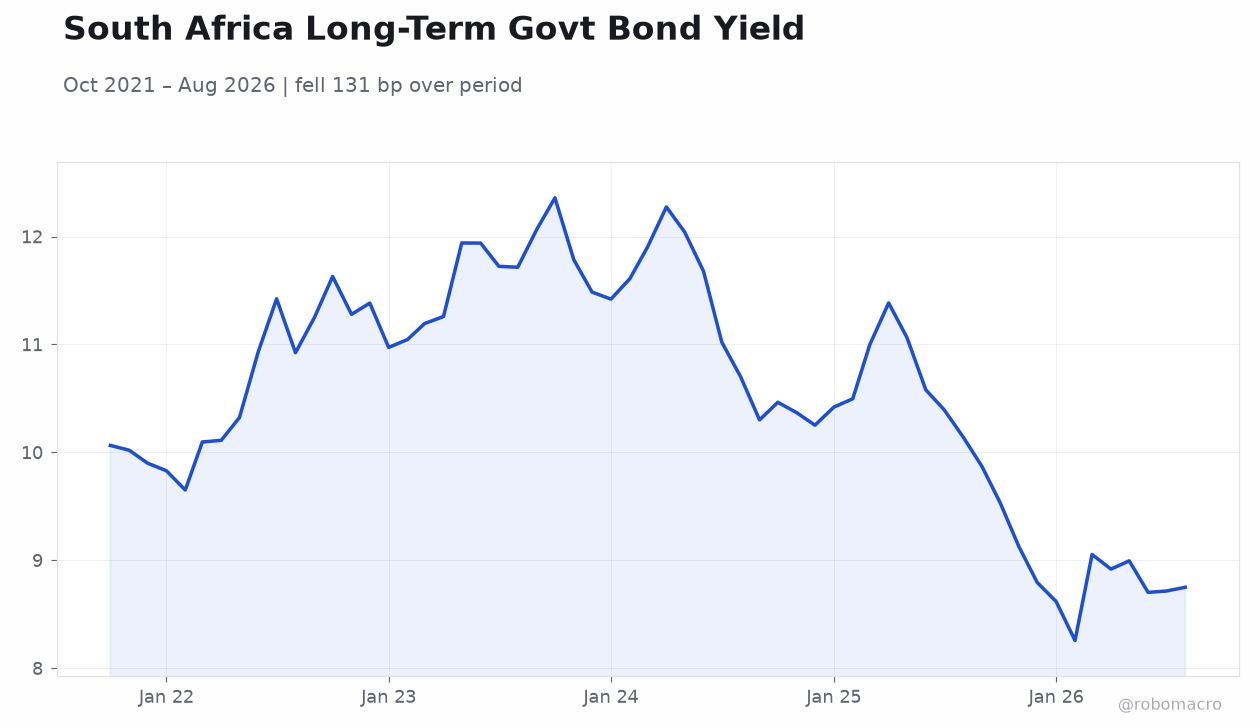
| South Africa 5Y Govt Yield | 8.67% | -8 bp |
| South Africa 10Y Govt Yield | 9.01% | -2 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
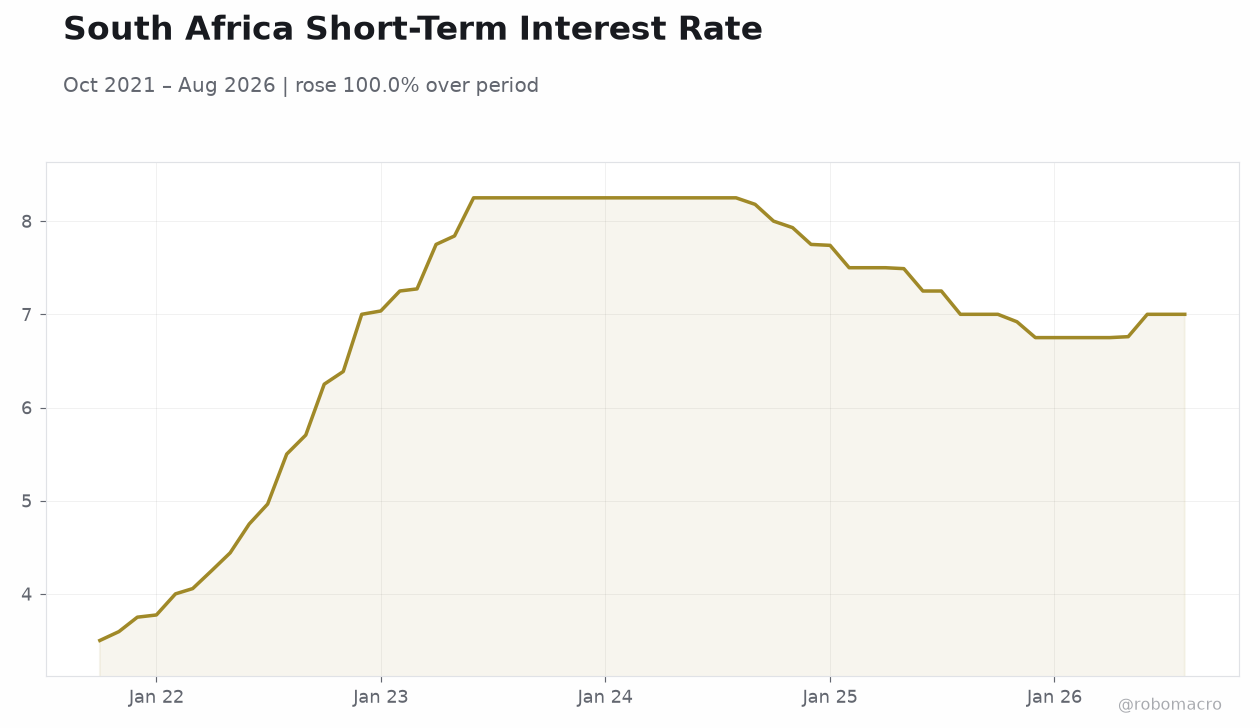 South Africa Short-Term Interest Rate | Type: macro_line | Policy Rate %: 7 (2026-08-01) | Range: 3.5–8.25 | Trend(5pt): 3.5,7,8.25,7.5,7
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Wednesday (2026-09-23) | |||
| Inflation Rate Month-over-Month | 0.20 | - | 00:00 |
| Inflation Rate Year-over-Year | 4.30 | - | 00:00 |
| Central Bank Interest Rate Decision | 7 | - | 05:00 |
- Rand holds steady ahead of inflation data and SARB meeting
- JSE Top 40 falls 1.23% while 5Y and 10Y yields ease 8 bp and 2 bp
- Brent crude drops 5.93% as oil shock raises hike prospects
Yesterday's Recap
No economic data releases occurred on 20 September. The JSE Top 40 closed at 105,242.10, down 1.23%. USD/ZAR fell 0.74% to 16.26 while EUR/ZAR declined 0.69% to 18.65.
South Africa 5Y government yield eased 8 bp to 8.67% and the 10Y yield fell 2 bp to 9.01%. Gold declined 0.90% to 4,384.90 and platinum slipped 0.16% to 1,800.70. Brent crude fell sharply 5.93% to 97.71.
Bitcoin rose 0.32% to 81,494.54. Naspers declined 0.29%. The rand's modest gains aligned with positioning ahead of the 23 September MPC meeting rather than any shift in the current policy stance.
Cash remains the dominant payment method across South African households and small businesses despite digital alternatives. The sugar industry received positive regulatory clarity that supports domestic production and export prospects. Western Cape water restrictions continue to pose risks to agricultural output and regional growth.
The Day Ahead
Markets focus on the 23 September releases of South Africa Inflation Rate MoM, Inflation Rate YoY and the SARB Interest Rate Decision. The high-impact rate decision follows the previous 7.00% repo rate. Traders anticipate a possible hike given the recent oil price shock and its pass-through to inflation.
The rand is expected to remain sensitive to any deviation from the 7.00% level. Bond yields may extend recent declines if the committee signals caution on further tightening. Equity and mining sectors will watch for any commentary on load-shedding and commodity price stability.
Bond market participants noted the 10Y yield near 9.01% as inflation expectations stay anchored near the upper end of the target band. Broader fiscal pressures from elevated debt service costs limit room for additional spending support.
Other Economic Notes
Cash remains the dominant payment method across South African households and small businesses despite digital alternatives. The sugar industry received positive regulatory clarity that supports domestic production and export prospects. Western Cape water restrictions continue to pose risks to agricultural output and regional growth.
↓ p.2