South Africa Macro Daily(Beta Mode)
SARB Decision Looms as Rand Tests Lows
Market Snapshot
| Asset | Level | Change |
|---|---|---|
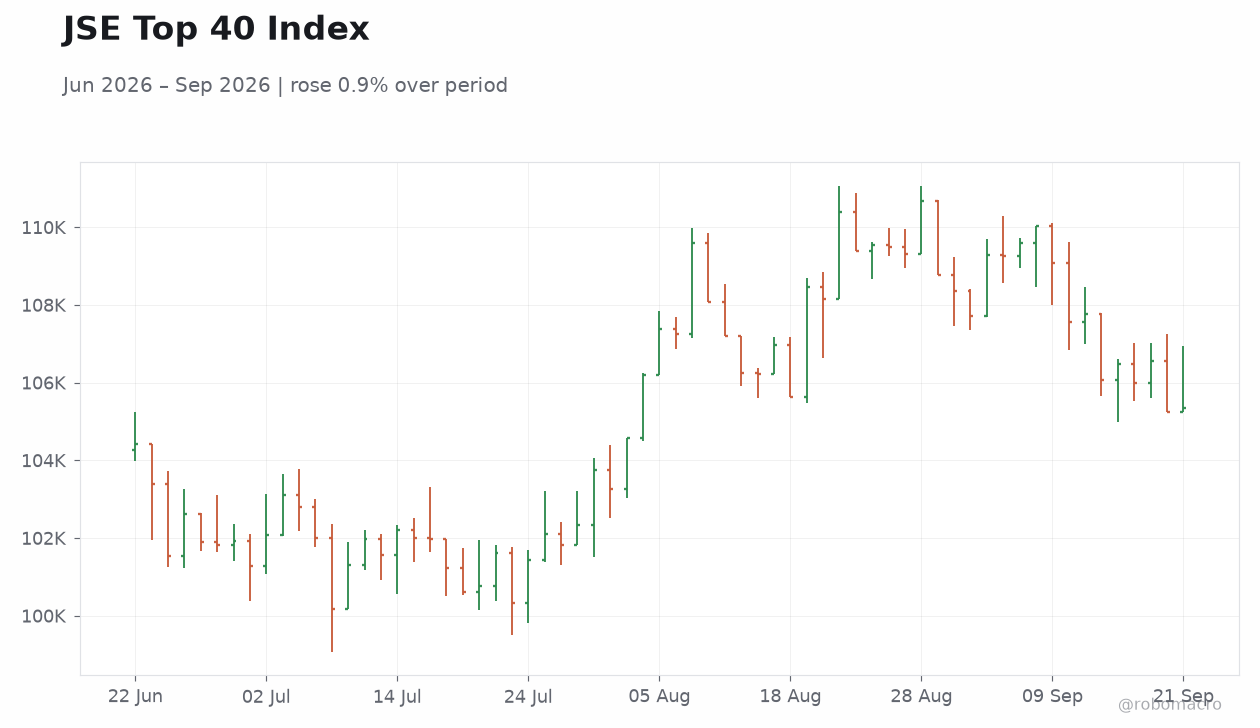
| JSE Top 40 | 105,343.40 | +0.10% |
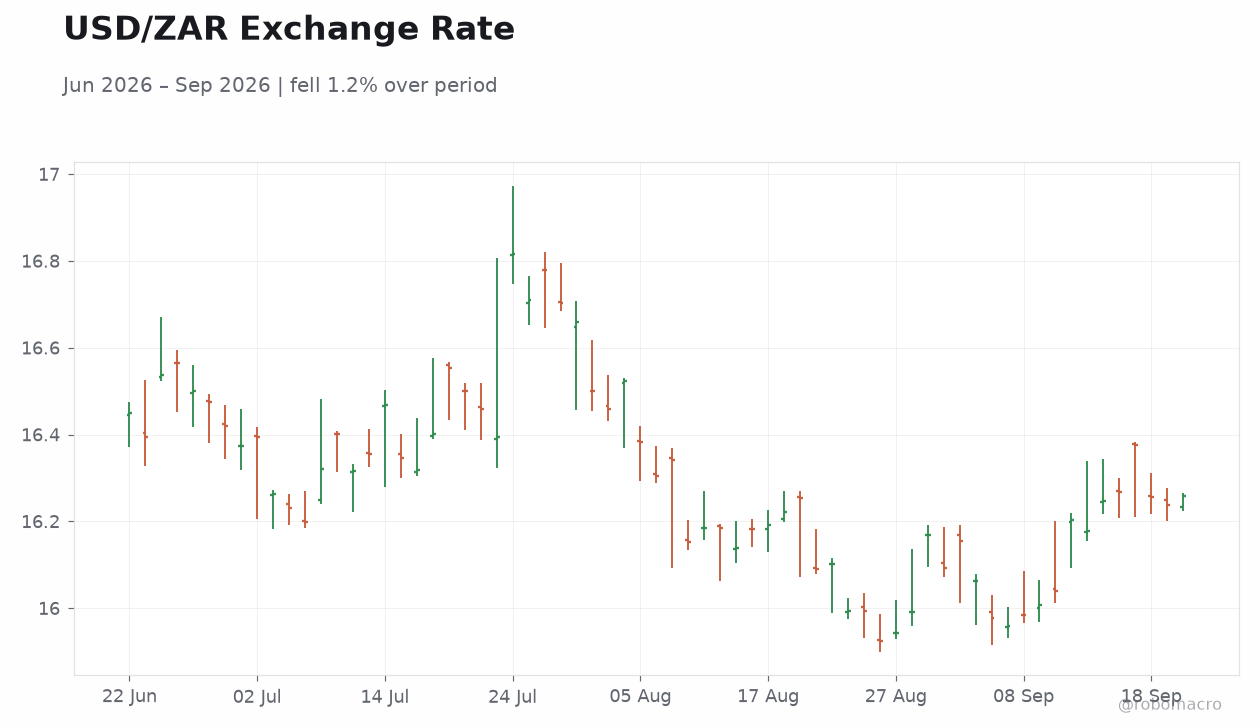
| USD/ZAR | 16.24 | -0.10% |
| EUR/ZAR | 18.65 | -0.00% |
| Platinum | 1,785.90 | -0.70% |
| Gold | 4,360.10 | -0.54% |
| Brent Crude | 97.61 | -2.72% |
| Naspers | 71,460.00 | -0.29% |
| Bitcoin | 85,535.94 | +5.41% |
| South Africa 5Y Govt Yield | 8.63% | -4 bp |
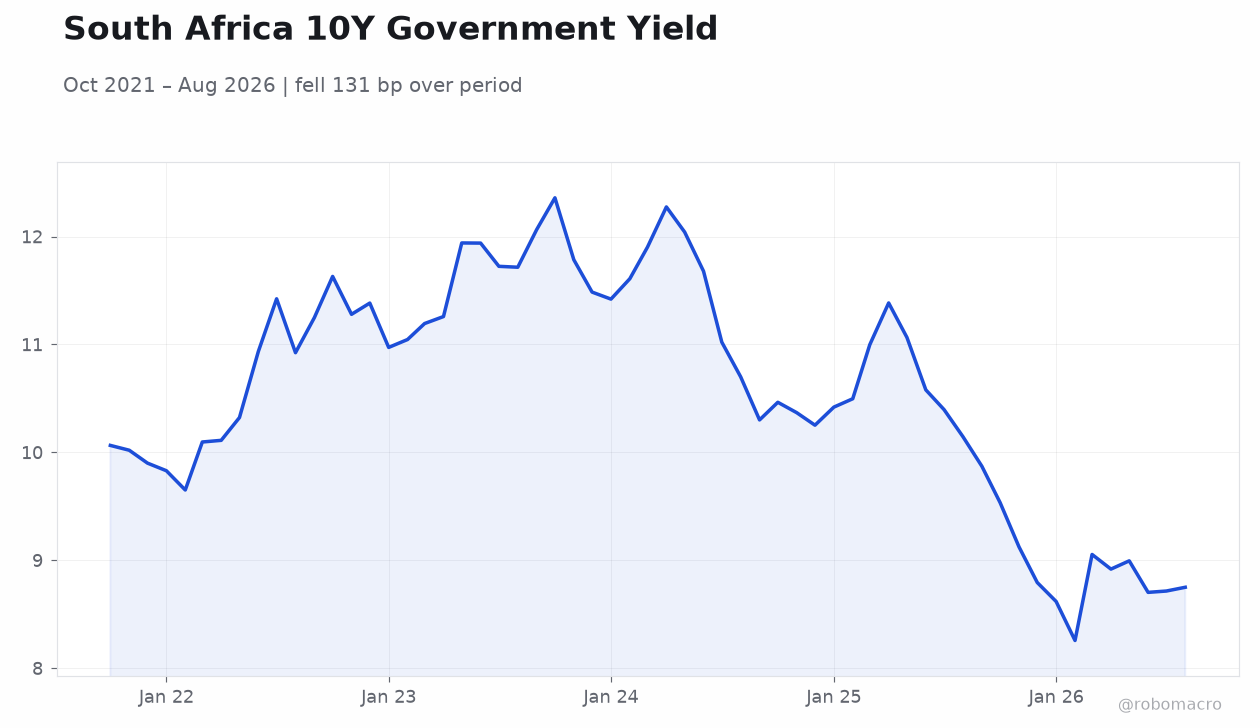
| South Africa 10Y Govt Yield | 8.86% | -15 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
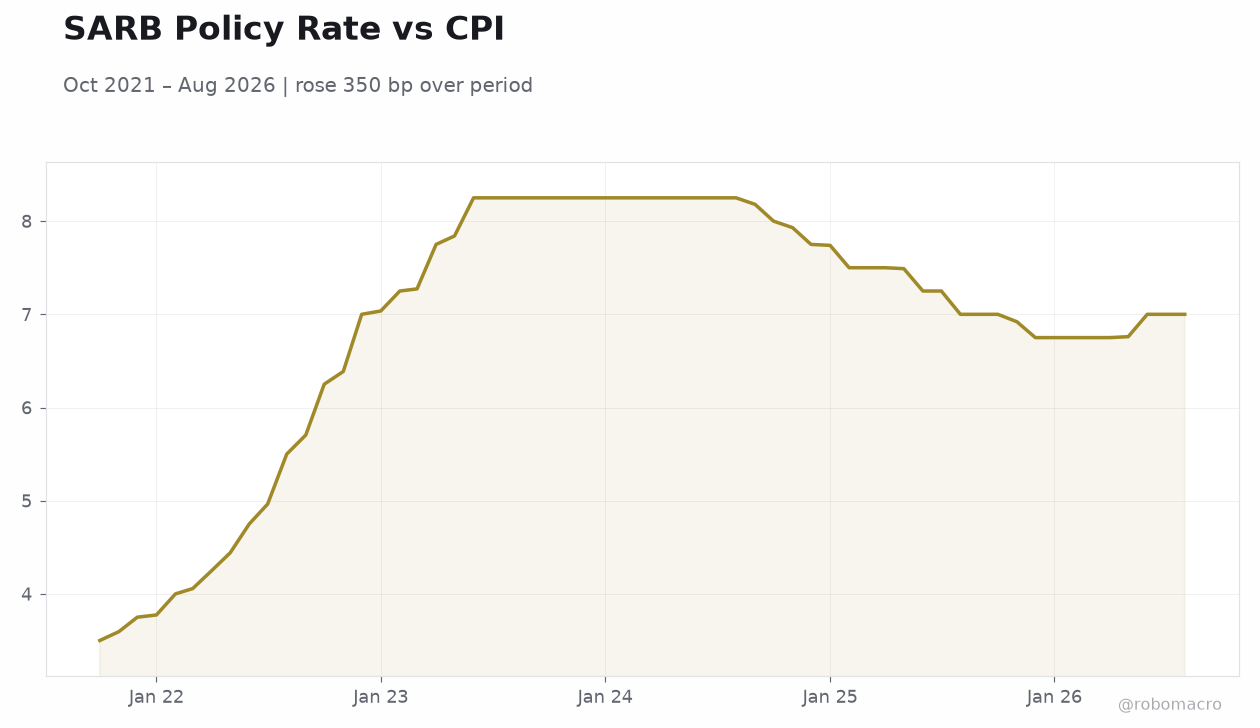 SARB Policy Rate vs CPI | Type: macro_line | Policy Rate %: 7 (2026-08-01) | Range: 3.5–8.25 | Trend(5pt): 3.5,7,8.25,7.5,7
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Wednesday (2026-09-23) | |||
| Inflation Rate Month-over-Month | 0.20 | - | 00:00 |
| Inflation Rate Year-over-Year | 4.30 | - | 00:00 |
| Central Bank Interest Rate Decision | 7 | - | 05:00 |
- SARB rate decision and CPI prints due tomorrow with repo rate at 7.00%
- 10-year yield eased 15 bp to 8.86% while USD/ZAR held near 16.24
- JSE Top 40 rose 0.10% as platinum and gold prices declined
Yesterday's Recap
South African markets showed modest gains on 21 September with the JSE Top 40 closing at 105,343.40, up 0.10%. USD/ZAR finished at 16.24 after a 0.10% decline while EUR/ZAR remained unchanged at 18.65. The 10-year government yield fell 15 bp to 8.86% and the 5-year yield declined 4 bp to 8.63%, reflecting market positioning ahead of the policy meeting.
Platinum dropped 0.70% to 1,785.90 and gold eased 0.54% to 4,360.10 as Brent crude fell 2.72% to 97.61. No economic data releases occurred. Bitcoin advanced 5.41% to 85,535.94, providing limited offset to commodity weakness.
The rand remained near its one-month low amid ongoing concerns over external pressures.
The Day Ahead
South Africa will release inflation data and the SARB policy decision on 23 September. The CPI month-over-month figure carries a previous reading of 0.2% while the year-over-year rate stands at a prior 4.3%. Markets will focus on the central bank interest rate decision, previously held at 7.00%.
The high-impact rate announcement will shape rand volatility and bond yield movements. Inflation prints will feed directly into the MPC assessment of price pressures. Analysts expect the data to confirm whether the 4.26% July CPI level has shifted materially.
Other Economic Notes
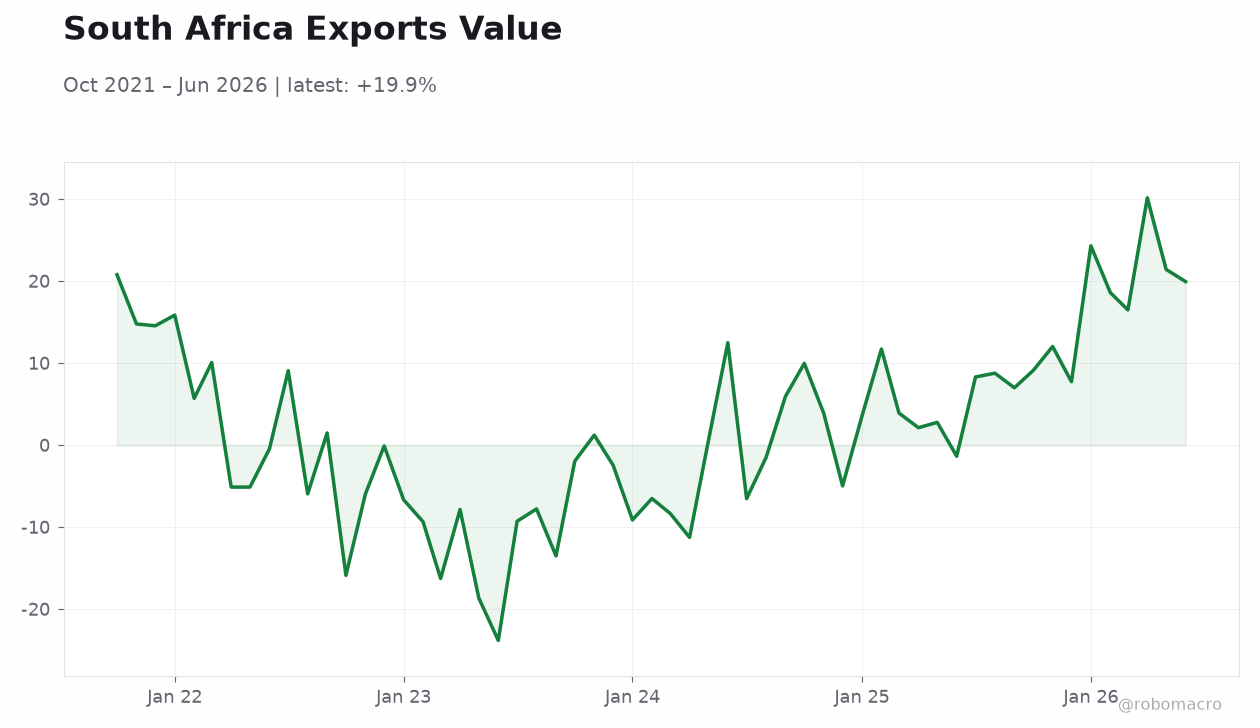
The rand's position at over one-month lows has prompted discussion of external vulnerability and domestic policy responses. Mining equities face pressure from declining platinum and gold prices, which could weigh on export revenues. Broader fiscal concerns include reports of irregular land transfers valued at R58 million, highlighting governance challenges.
These factors combine with the upcoming inflation release to keep focus on the SARB's inflation-targeting framework.
Global Macro News
Global commodity markets exerted downward pressure on South African assets as Brent crude declined sharply. The Bank of Japan rate hike produced limited yen gains according to UBS analysis, leaving emerging-market currencies including the rand exposed to dollar strength. US interest rate differentials continue to influence rand flows, with the currency outlook tied to the SARB response.
↓ p.2