South Africa Macro Daily(Beta Mode)
SARB Hike Pressures JSE as Rand Holds Range
Market Snapshot
| Asset | Level | Change |
|---|---|---|
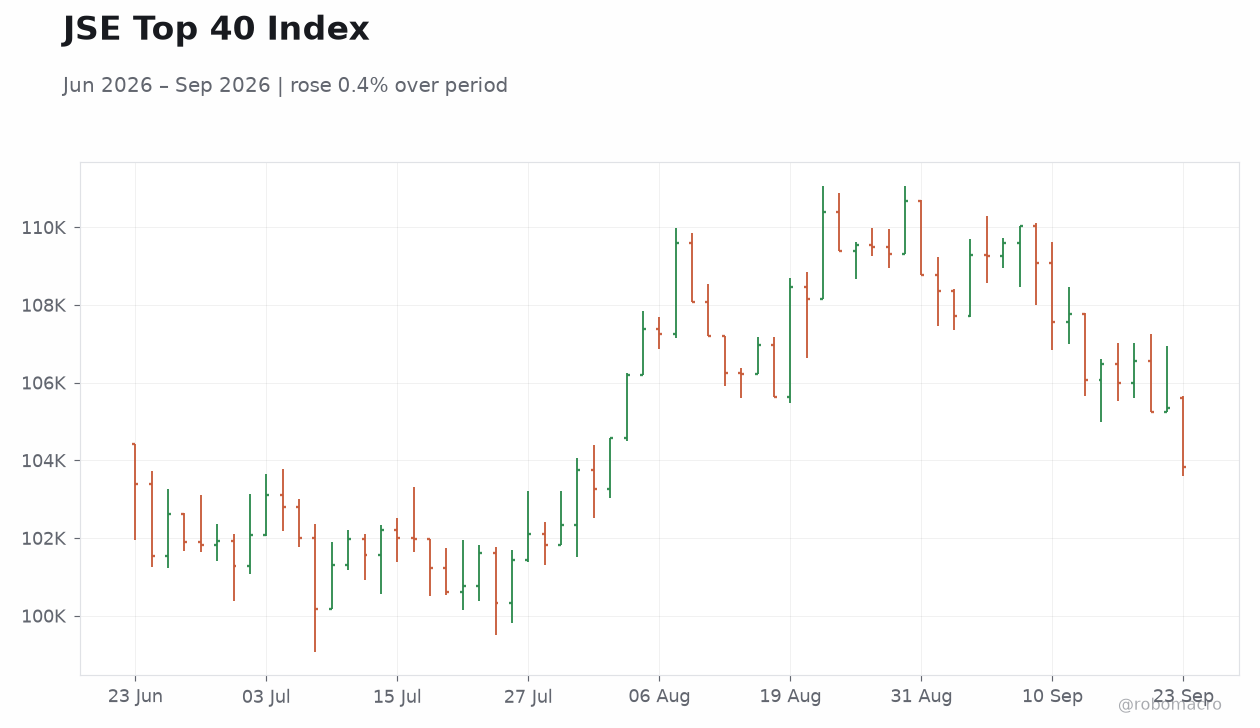
| JSE Top 40 | 103,823.10 | -1.44% |
| USD/ZAR | 16.16 | -0.36% |
| EUR/ZAR | 18.65 | +0.70% |
| Platinum | 1,758.70 | +0.74% |
| Gold | 4,317.70 | -0.02% |
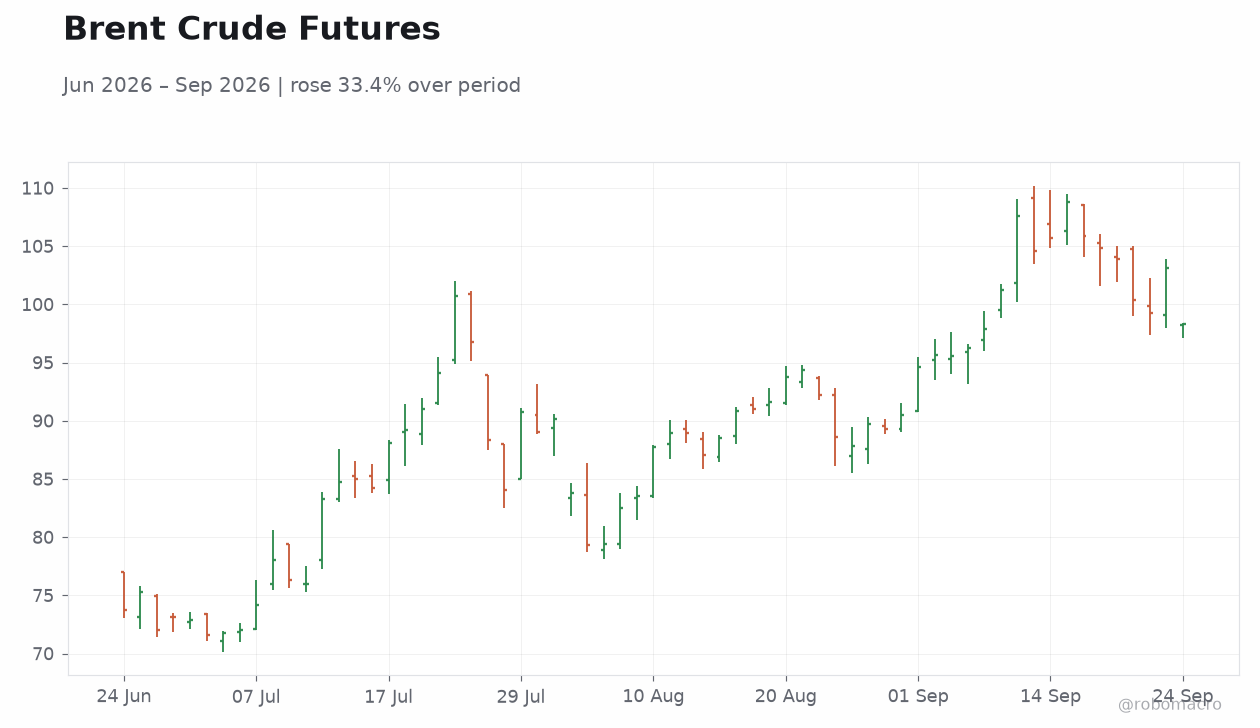
| Brent Crude | 98.17 | -4.76% |
| Naspers | 71,182.00 | -4.91% |
| Bitcoin | 84,170.76 | -2.32% |
| South Africa 5Y Govt Yield | 8.61% | -1 bp |
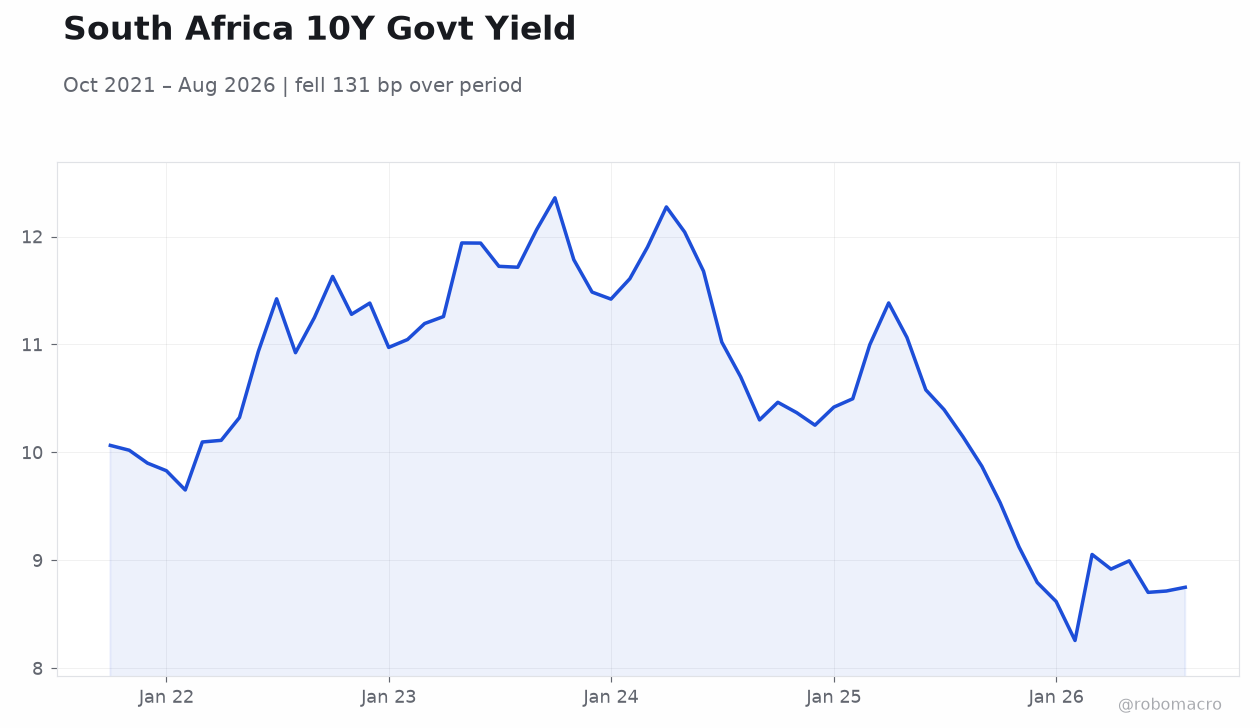
| South Africa 10Y Govt Yield | 8.85% | -2 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
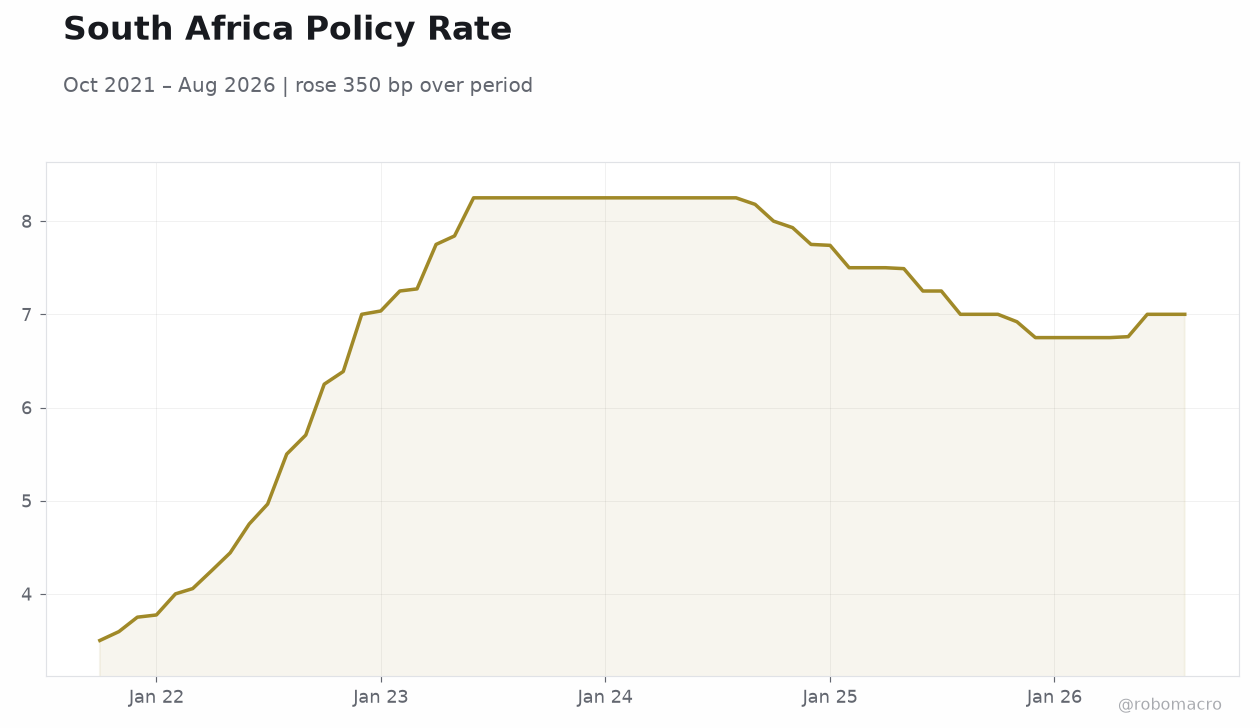 South Africa Policy Rate | Type: macro_line | Repo Rate %: 7 (2026-08-01) | Range: 3.5–8.25 | Trend(5pt): 3.5,7,8.25,7.5,7
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- SARB MPC lifts repo rate 25 bp to 7.25% amid persistent inflation pressures
- JSE Top 40 drops 1.44% while 10-year yield eases 2 bp to 8.85%
- Rand trades sideways with USD/ZAR at 16.16 after limited CPI reaction
Yesterday's Recap
South African markets absorbed the SARB’s decision to raise the repo rate to 7.25%. The JSE Top 40 closed at 103,823.10, down 1.44%, led lower by Naspers which fell 4.91%. USD/ZAR ended at 16.16 after a 0.36% decline while EUR/ZAR rose 0.70% to 18.65.
Platinum gained 0.74% to 1,758.70 and Brent Crude dropped 4.76% to 98.17. Government bond yields eased modestly with the 5-year at 8.61% and the 10-year at 8.85%. Commentary noted the rand remained range-bound after the latest CPI release and showed little immediate reaction to the rate decision.
The 10-year yield reached an over-two-week low as markets priced in the higher policy path. No economic releases occurred on the day, leaving the MPC announcement as the dominant driver.
The Day Ahead
No major South African data releases or SARB speeches are scheduled. Markets will likely focus on follow-through from the recent repo-rate hike and any external drivers affecting commodity prices. Attention may turn to global oil and metal moves given South Africa’s mining exposure.
The absence of domestic events leaves room for technical trading in the rand and bonds. Participants will monitor any comments from MPC members for signals on the future rate path. With the calendar empty, positioning in equities and fixed income is expected to reflect ongoing digestion of the policy tightening and Brent Crude’s sharp move lower.
Other Economic Notes
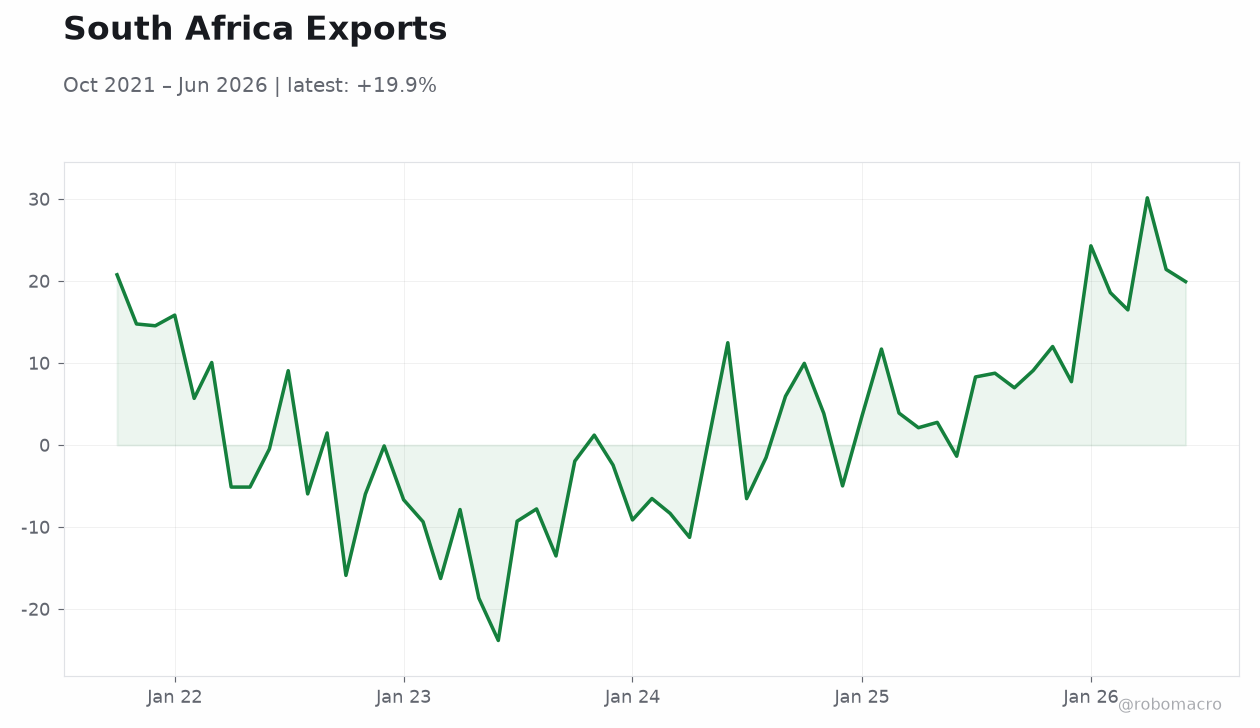
The rate increase drew criticism that higher borrowing costs are clearly hurting the economy and risk entrenching stagnant growth. Inflation remains above the midpoint of the target band, supporting the SARB’s tightening stance despite weak activity indicators. Mining output and platinum-group metals continue to influence both the trade balance and rand volatility.
Load-shedding risks remain a structural constraint on industrial production and investor sentiment. Fiscal space stays limited, keeping pressure on yields even as they edged lower yesterday. The CPI print elicited minimal immediate market reaction, consistent with the view that the SARB’s move was largely anticipated.