South Africa Macro Daily(Beta Mode)
Rand Firms After Trade Balance Beat
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| JSE Top 40 | 100,790.10 | -0.92% |
| USD/ZAR | 16.39 | -0.09% |
| EUR/ZAR | 18.61 | +0.12% |
| Platinum | 1,733.10 | +1.81% |
| Gold | 4,204.70 | +0.43% |
| Brent Crude | 96.85 | -6.45% |
| Naspers | 70,260.00 | -1.71% |
| Bitcoin | 83,823.16 | +0.24% |
| South Africa 5Y Govt Yield | 8.86% | +8 bp |
| South Africa 10Y Govt Yield | 9.09% | +1 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| Trade Balance | 20,140m | - | 20,470m |
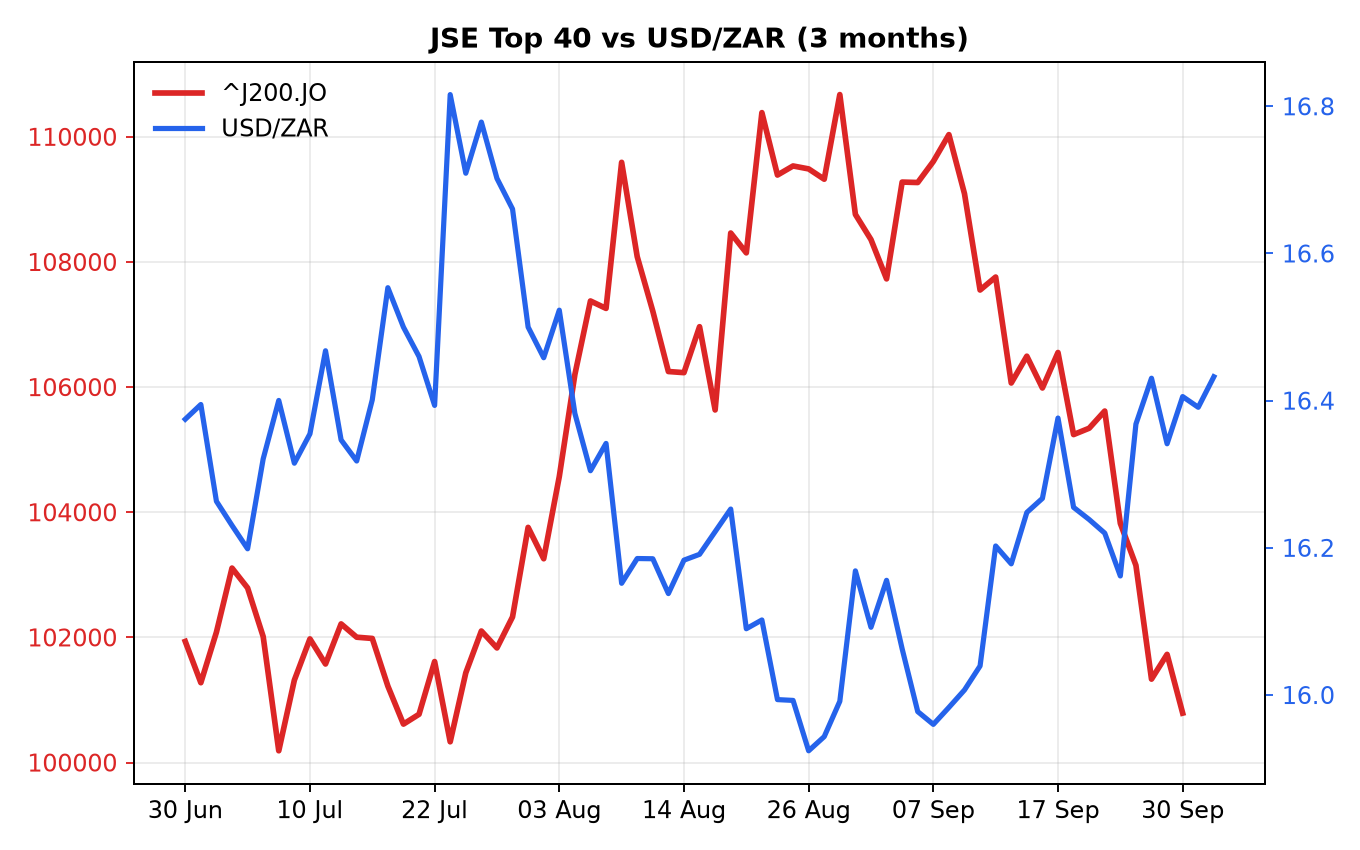
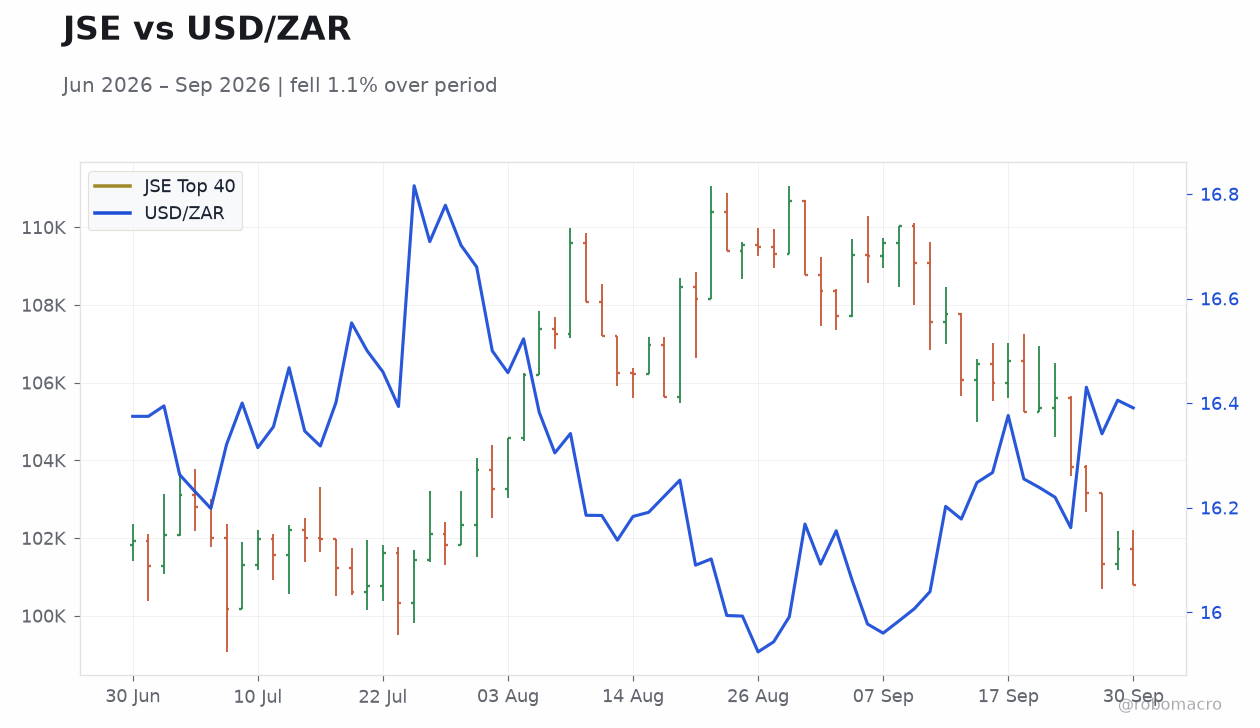 JSE vs USD/ZAR | Type: market_hloc | JSE Top 40: 1.008e+05 (2026-09-30) | Range: 1.002e+05–1.107e+05 | Trend(5pt): 1.019e+05,1.016e+05,1.062e+05,1.096e+05,1.008e+05 | USD/ZAR: 16.43 (2026-10-01) | Range: 15.92–16.82 | Trend(6pt): 16.37,16.39,16.18,15.96,16.41,16.43
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- Trade surplus widens to ZAR 20.47 billion from ZAR 20.14 billion
- USD/ZAR eases 0.09 percent to 16.39 while JSE Top 40 drops 0.92 percent
- Five-year government yield rises eight basis points to 8.86 percent
Yesterday's Recap
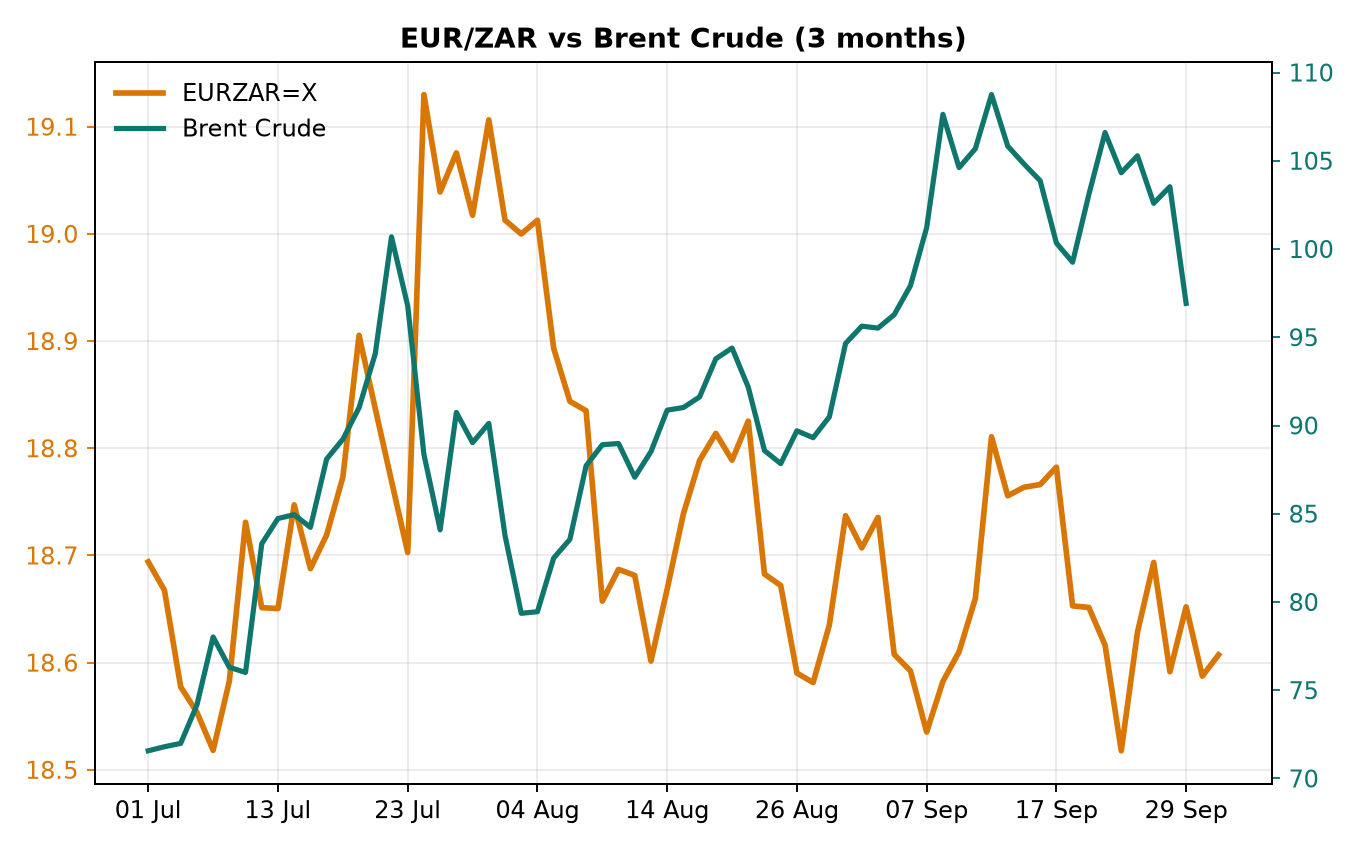
The rand firmed as investors digested the latest trade data. South Africa's trade surplus expanded to ZAR 20.47 billion from ZAR 20.14 billion previously. USD/ZAR eased 0.09 percent to 16.39 while EUR/ZAR rose 0.12 percent to 18.61.
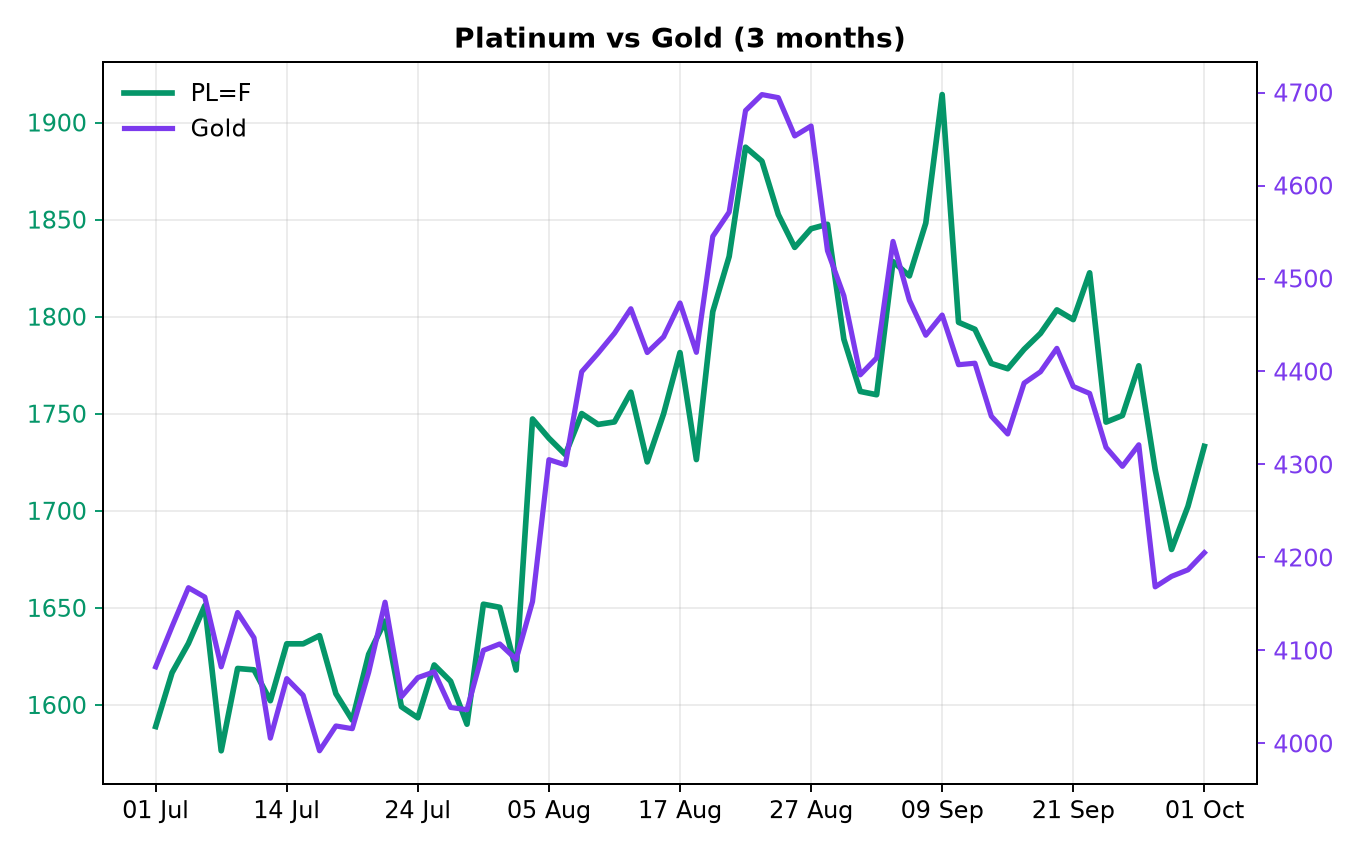
The JSE Top 40 fell 0.92 percent to 100,790.10. Platinum rose 1.81 percent to 1,733.10 and gold advanced 0.43 percent to 4,204.70. Brent crude dropped 6.45 percent to 96.85.
Government bond yields increased, with the five-year yield rising eight basis points to 8.86 percent and the ten-year yield adding one basis point to 9.09 percent. Market participants attributed the currency gains to the positive trade print and broader data review. Naspers declined 1.71 percent to 70,260.00, weighing on the equity index.
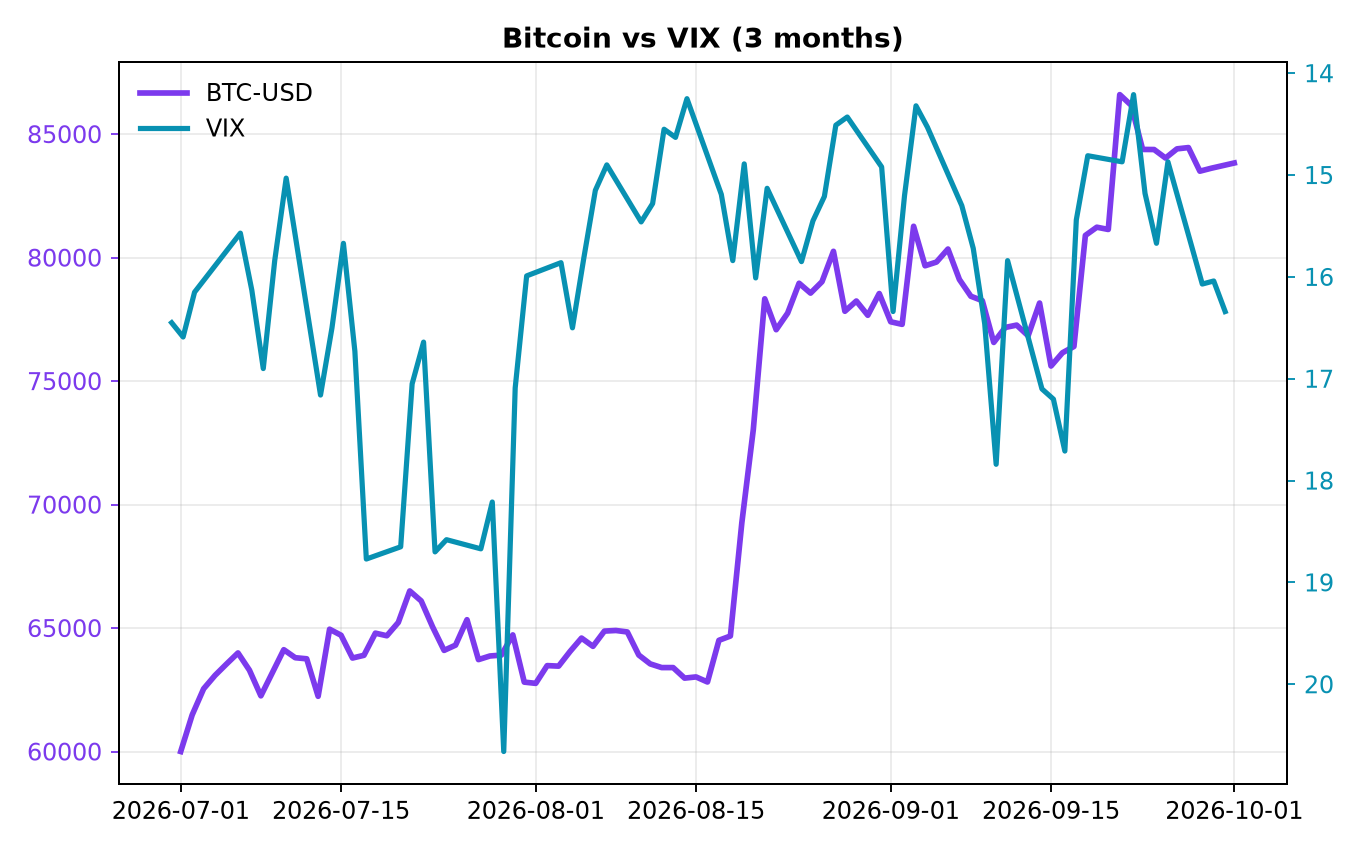
Bitcoin edged 0.24 percent higher to 83,823.16. The medium-impact trade release aligned with reports noting modest rand support from local data flows.
The Day Ahead
No economic releases are scheduled for October 1. Traders will monitor global commodity prices given South Africa's exposure to mining exports. Attention may turn to any updates on energy supply amid ongoing load shedding concerns.
No SARB communications are expected. Market focus remains on incoming data for rate path signals. The absence of domestic events could keep volumes light ahead of the weekend.
Platinum and gold price movements may influence sentiment toward resource equities, while Brent crude volatility could affect broader risk appetite. Currency pairs are likely to track external dollar flows in the absence of fresh local catalysts.
Other Economic Notes
South Africa's inflation rate stood at 4.26 percent as of July. The SARB maintains the repo rate at 7.00 percent. Recent commentary highlights that the period of accommodative policy may have been overstated in its effects on growth.
Fiscal pressures and structural challenges continue to weigh on growth prospects. President Ramaphosa's announcements on social issues carry limited direct economic impact. ↓ p.2