South Africa Macro Daily(Beta Mode)
JSE Rallies as Budget Anchor Looms
Market Snapshot
| Asset | Level | Change |
|---|---|---|
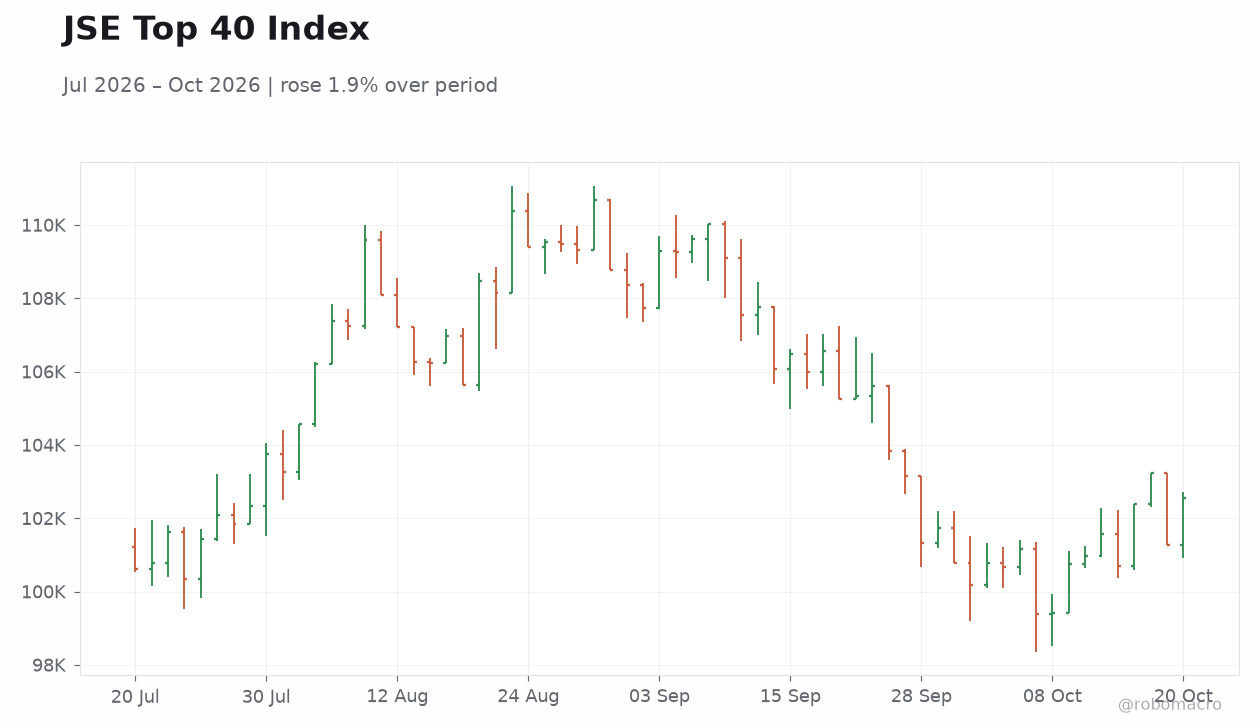
| JSE Top 40 | 102,553.50 | +1.27% |
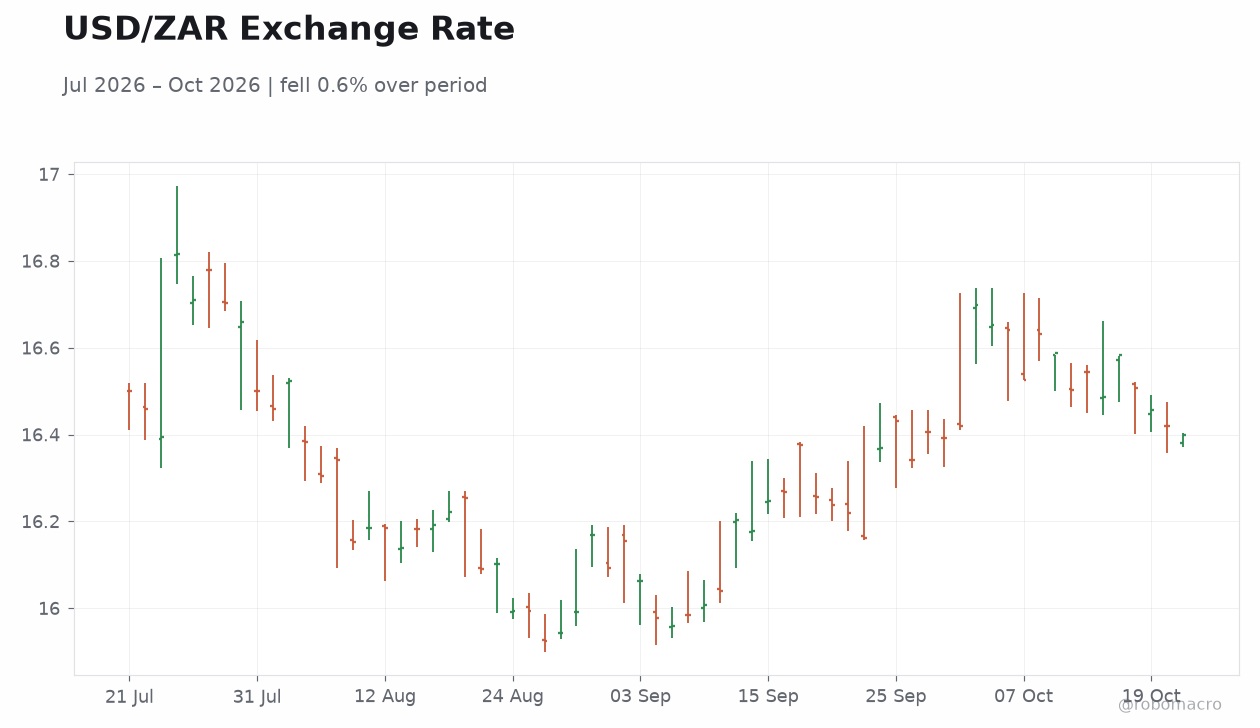
| USD/ZAR | 16.40 | -0.12% |
| EUR/ZAR | 18.41 | +0.00% |
| Platinum | 1,646.60 | +0.48% |
| Gold | 4,142.60 | -0.42% |
| Brent Crude | 108.79 | -0.69% |
| Naspers | 70,702.00 | +0.87% |
| Bitcoin | 82,650.76 | +0.97% |
| South Africa 5Y Govt Yield | - | - |
| South Africa 10Y Govt Yield | - | - |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
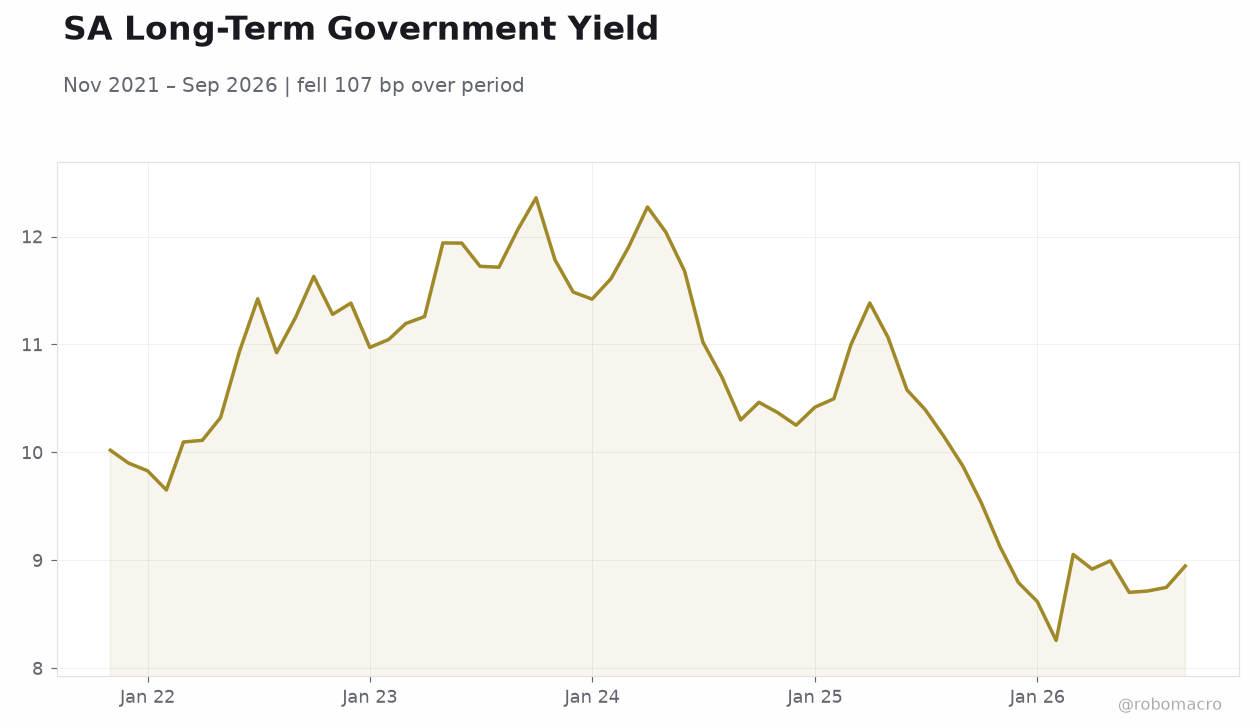 SA Long-Term Government Yield | Type: macro_line | 10Y yield %: 8.947 (2026-09-01) | Range: 8.257–12.36 | Trend(6pt): 10.02,10.97,11.9,11.07,8.715,8.947
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- JSE Top 40 surges 1.27% to 102,553.50 as risk appetite improves across SA equities
- Rand firms modestly to 16.40/USD; platinum gains 0.48% while gold slips 0.42%
- Finance Minister Godongwana set to unveil fiscal anchor to entrench public finance repair
Yesterday's Recap
South African markets delivered a strong risk-on session yesterday, with the JSE Top 40 climbing 1.27% to close at 102,553.50, led by index heavyweight Naspers which added 0.87% to 70,702.00. The rand strengthened marginally against the dollar, with USD/ZAR easing 0.12% to 16.40, while EUR/ZAR held flat at 18.41. Commodity-linked names found support as platinum rose 0.48% to $1,646.60 an ounce, though gold retreated 0.42% to $4,142.60.
Brent crude slipped 0.69% to $108.79 a barrel, offering modest relief on the imported inflation front. Bitcoin traded 0.97% higher at $82,650.76, reflecting broadly constructive global risk sentiment. Notably, South African 5Y and 10Y government bond yields were not reported in the supplied data, so no yield commentary is possible today.
No scheduled domestic data releases were recorded for the session.
The Day Ahead
The domestic calendar is empty for today, with no tier-one South African data releases scheduled and no events carried over from tomorrow. Market direction will therefore be driven by offshore cues and positioning ahead of the Medium-Term Budget Policy Statement, where Finance Minister Enoch Godongwana is expected to unveil a new fiscal anchor. Traders will watch the rand closely for any pre-budget volatility, particularly given the currency's sensitivity to fiscal credibility signals.
JSE liquidity should remain concentrated in large-cap industrials and mining counters, with platinum-group names likely to outperform if the metal's recent bid persists. With no local catalysts, US session developments and global risk appetite will dominate the afternoon.
Other Economic Notes
The upcoming fiscal anchor represents a structural shift in Treasury's approach, aiming to entrench the progress made in repairing public finances and reduce debt-sustainability risk premia over time. News flow flagged mounting pressures from the Iran war, which could complicate the fiscal arithmetic through higher energy costs and slower global demand. On the social front, residents east of Pretoria have been warned not to drink tap water after more than 400 people, mostly children, fell ill from contamination — a reminder of municipal infrastructure gaps that weigh on service delivery credibility.
↓ p.2