South Africa Macro Daily(Beta Mode)
JSE Rises as Yields Ease on HSBC Exit
Market Snapshot
| Asset | Level | Change |
|---|---|---|
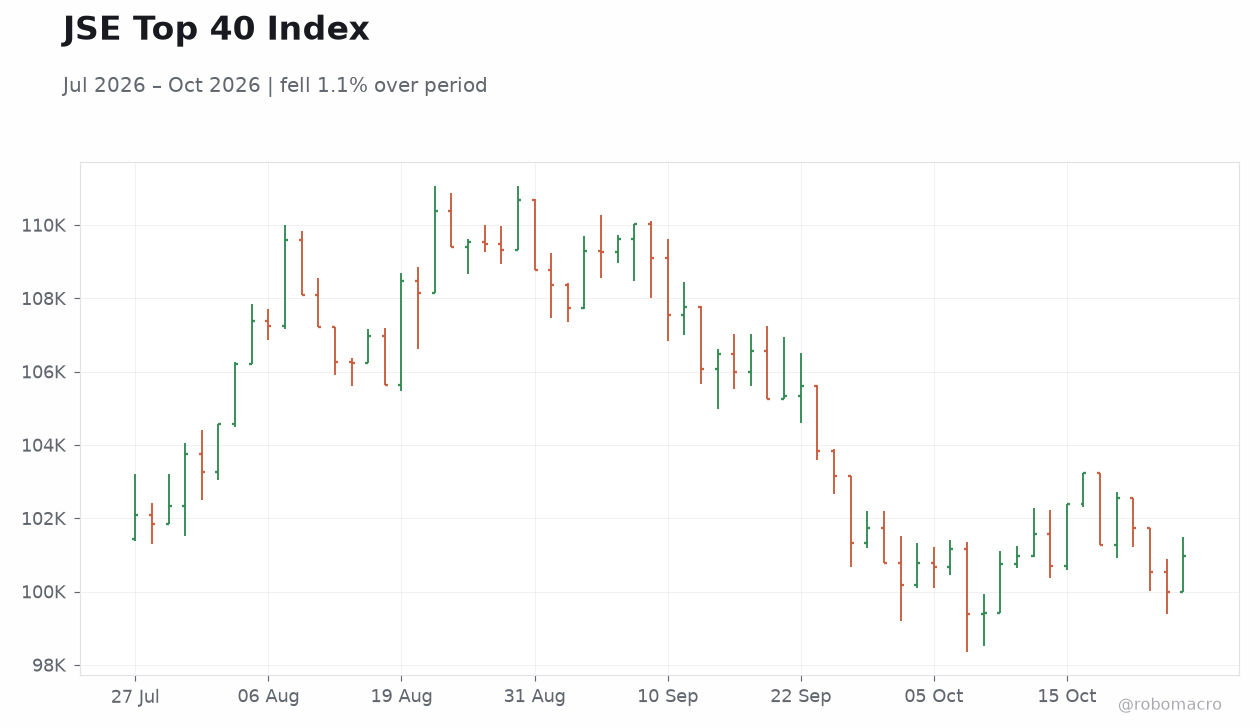
| JSE Top 40 | 100,977.00 | +0.99% |
| USD/ZAR | 16.62 | -0.01% |
| EUR/ZAR | 18.57 | -0.41% |
| Platinum | 1,536.70 | -1.13% |
| Gold | 4,038.40 | +0.76% |
| Brent Crude | 115.81 | -0.78% |
| Naspers | 68,430.00 | +0.78% |
| Bitcoin | 79,678.35 | -0.43% |
| South Africa 5Y Govt Yield | 8.59% | -10 bp |
| South Africa 10Y Govt Yield | 8.82% | -7 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
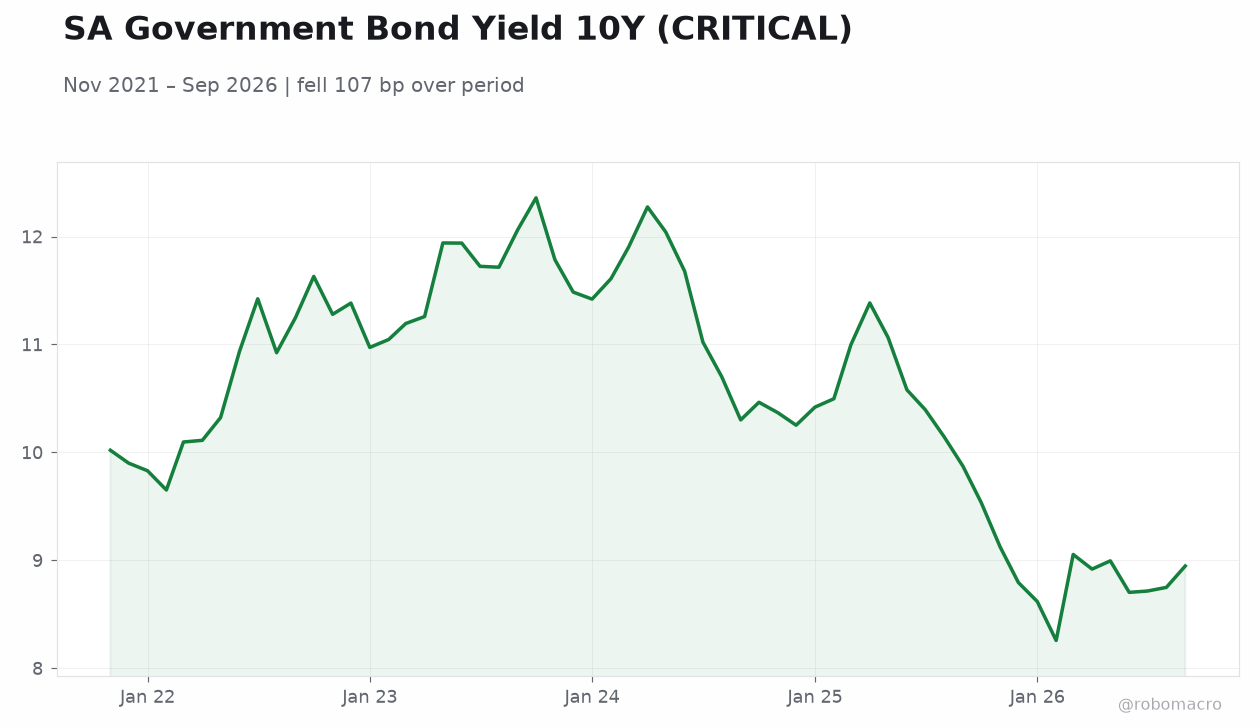
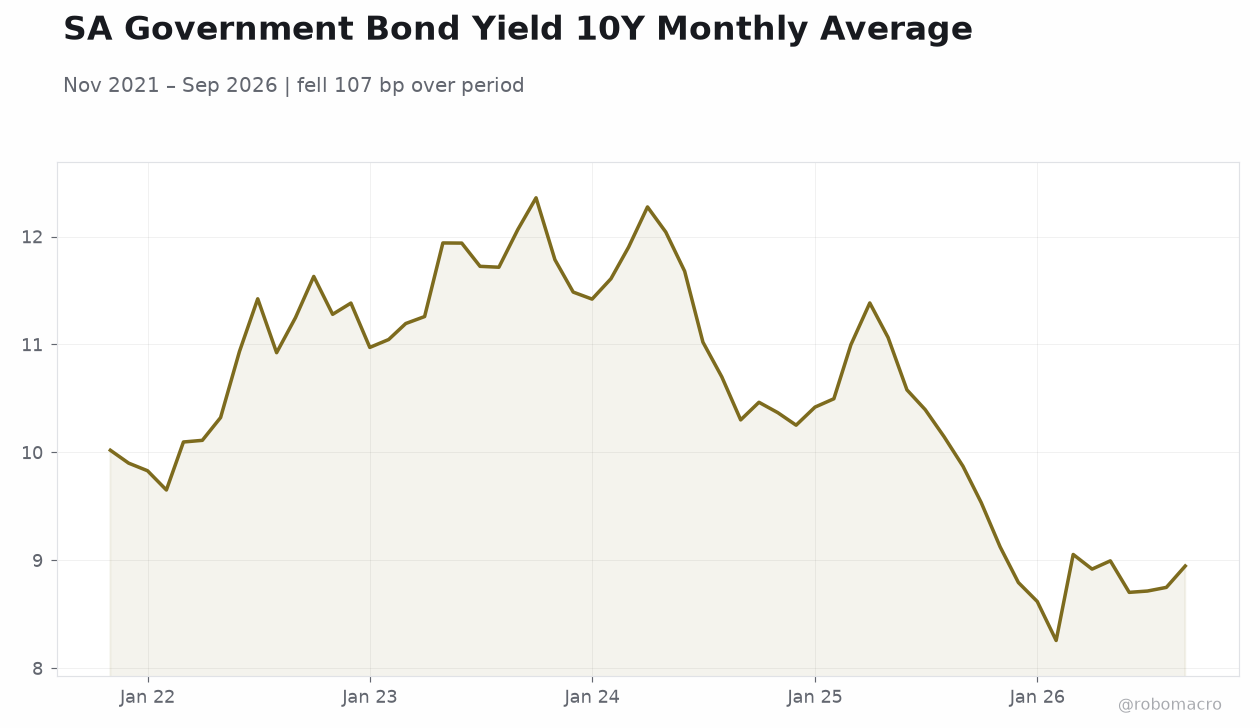
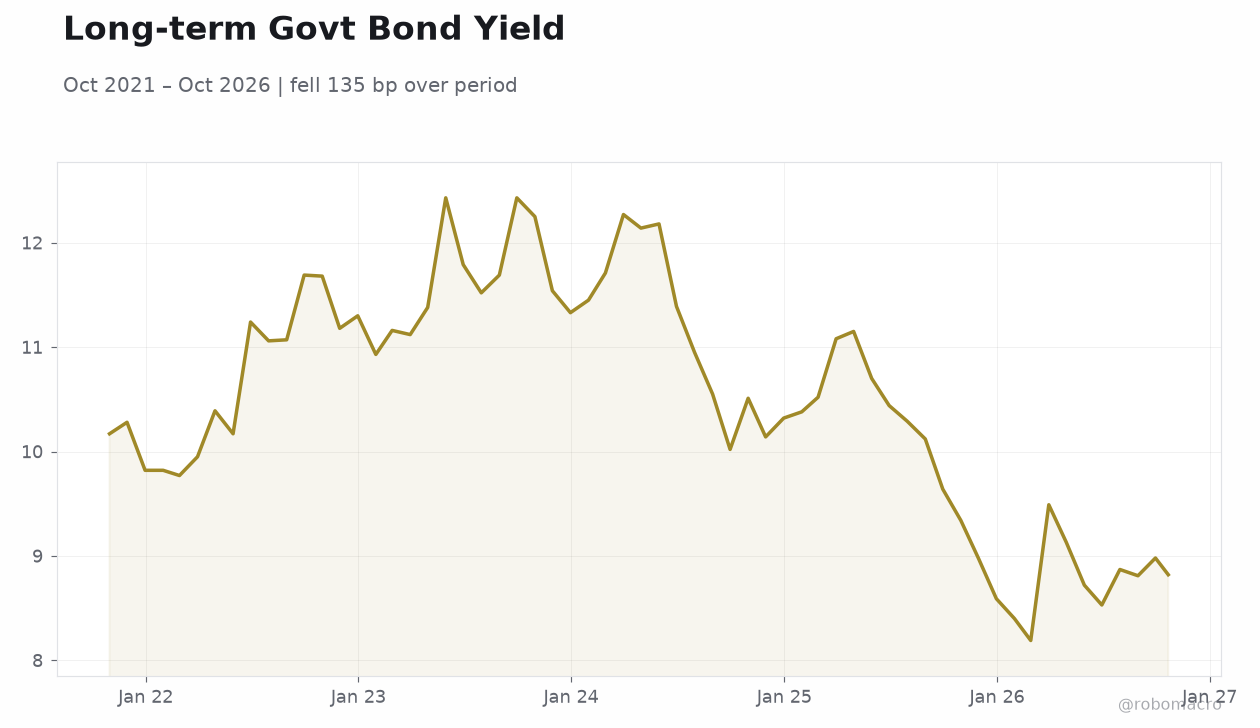 Long-term Govt Bond Yield | Type: macro_line | 10Y Yield %: 8.82 (2026-10-22) | Range: 8.19–12.43 | Trend(5pt): 10.17,10.93,12.14,10.29,8.82
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Friday (2026-10-30) | |||
| Trade Balance | 20,470m | - | 08:00 |
- JSE Top 40 gains 0.99% to 100,977 while rand holds near 16.62
- 10-year yield falls 7 bp to 8.82% and 5-year yield drops 10 bp
- Trade balance print due Friday; no data releases yesterday
Yesterday's Recap
South African markets recorded a solid equity advance with the JSE Top 40 index climbing 0.99% to close at 100,977. The rand traded in a narrow range, posting a 0.01% decline versus the dollar at 16.62 while the euro-zar cross eased 0.41%. Gold rose 0.76% to 4,038.40, offsetting a 1.13% decline in platinum prices.
Brent crude slipped 0.78% to 115.81 amid softer global demand signals. Government bonds rallied, driving the 5-year yield 10 bp lower to 8.59% and the 10-year yield 7 bp lower to 8.82%. Naspers shares added 0.78%, contributing to the broad market lift.
No economic data prints occurred on the session. Bitcoin eased 0.43% to 79,678.35, reflecting cautious global risk appetite that left emerging-market assets mixed.
The Day Ahead
Attention turns to the October trade balance release scheduled for Friday at 08:00. The prior print recorded a 20.47 billion rand surplus. Market participants will assess whether mining and manufacturing exports maintained momentum.
The figure arrives ahead of the November 19 monetary policy meeting and could shape near-term rand positioning. Broader focus remains on any signals around external demand and commodity price trends. Load-shedding developments and fiscal updates will also draw scrutiny through the week.
Investors will monitor any follow-through from the regulatory changes allowing full offshore allocation by local fund managers.
Other Economic Notes
South Africa revoked HSBC’s banking licence after 31 years, ending the lender’s local operations. Regulators are finalising rules that will permit fund managers to allocate up to 100% of assets offshore, aiming to deepen domestic capital markets and attract inflows. Fitch Ratings projects the debt-to-GDP ratio resuming an upward path by the fiscal year ending March 2029, diverging from Treasury forecasts.
An expected El Niño episode threatens agricultural output and could intensify food insecurity across southern Africa in 2027. Officials continue promoting Johannesburg as a regional financial centre through targeted regulatory reforms. Nigeria’s new High Commissioner pledged to strengthen bilateral ties and protect Nigerian nationals.