South Africa Macro Daily(Beta Mode)
Rand Firm, Bonds Steady Ahead of Trade Data
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| JSE Top 40 | 101,609.00 | +0.63% |
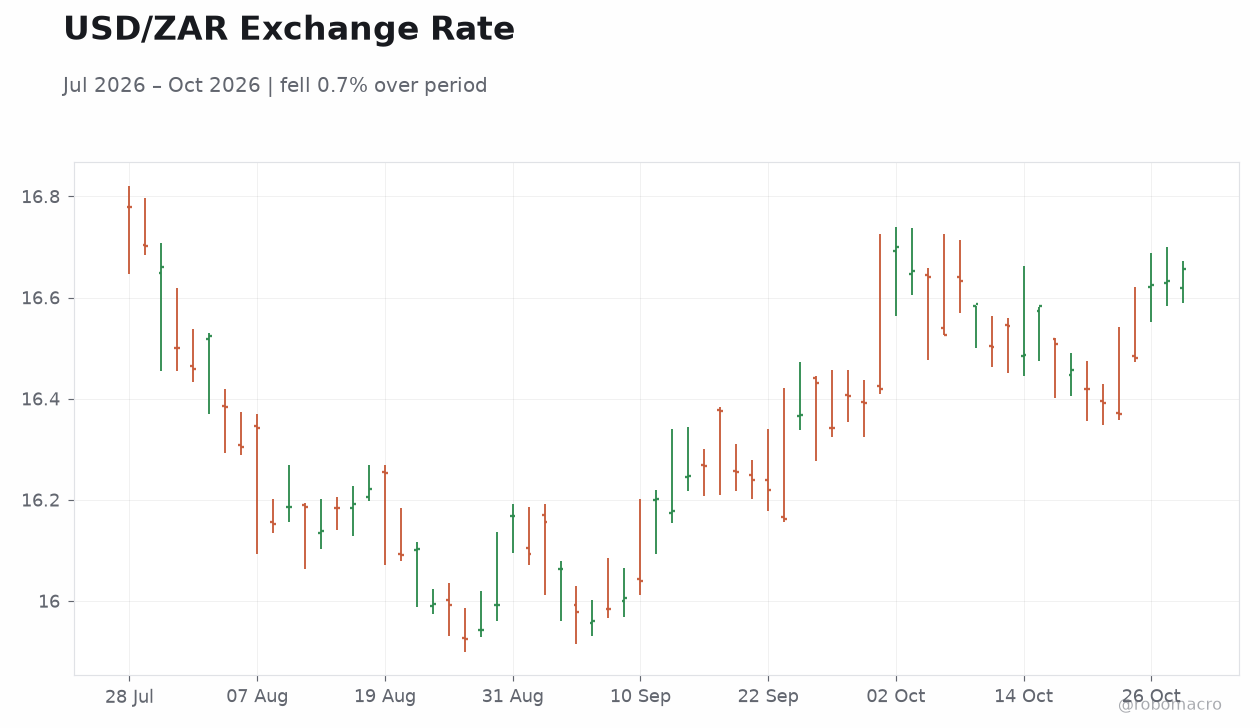
| USD/ZAR | 16.66 | +0.15% |
| EUR/ZAR | 18.53 | -0.31% |
| Platinum | 1,535.00 | -0.11% |
| Gold | 4,074.60 | +0.90% |
| Brent Crude | 113.88 | -1.67% |
| Naspers | 69,400.00 | +2.48% |
| Bitcoin | 81,017.34 | +1.26% |
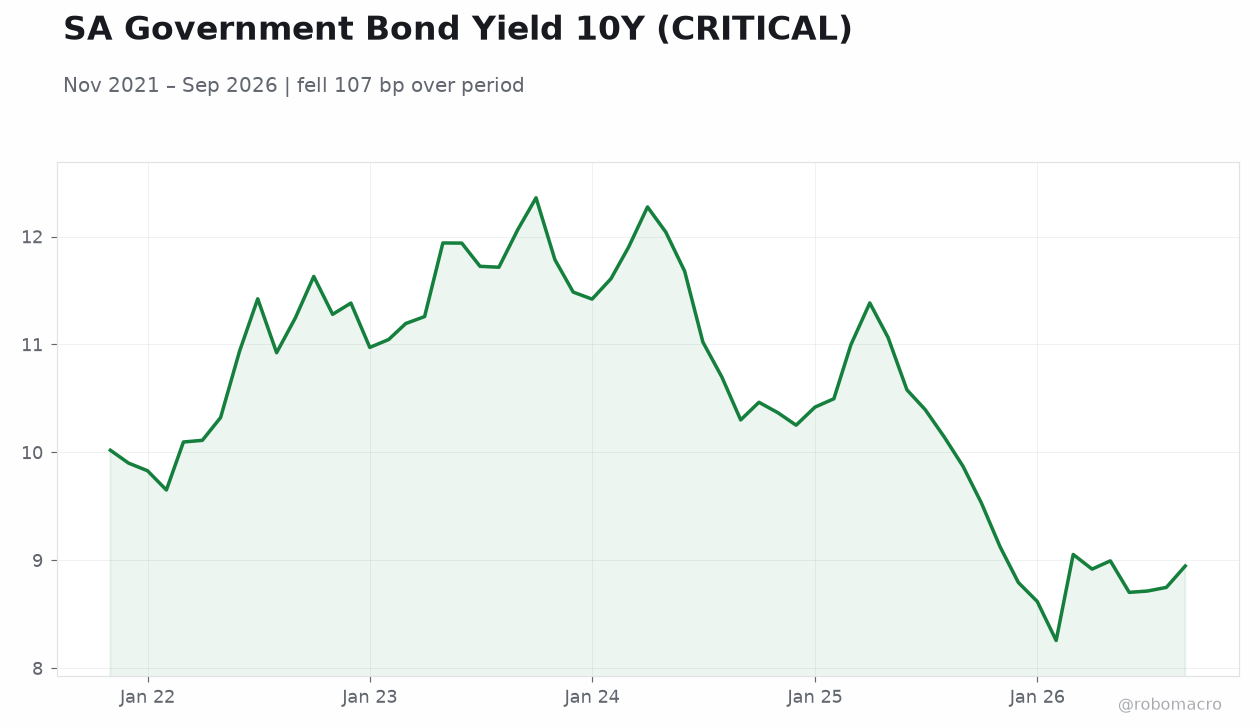
| South Africa 5Y Govt Yield | 8.62% | +3 bp |
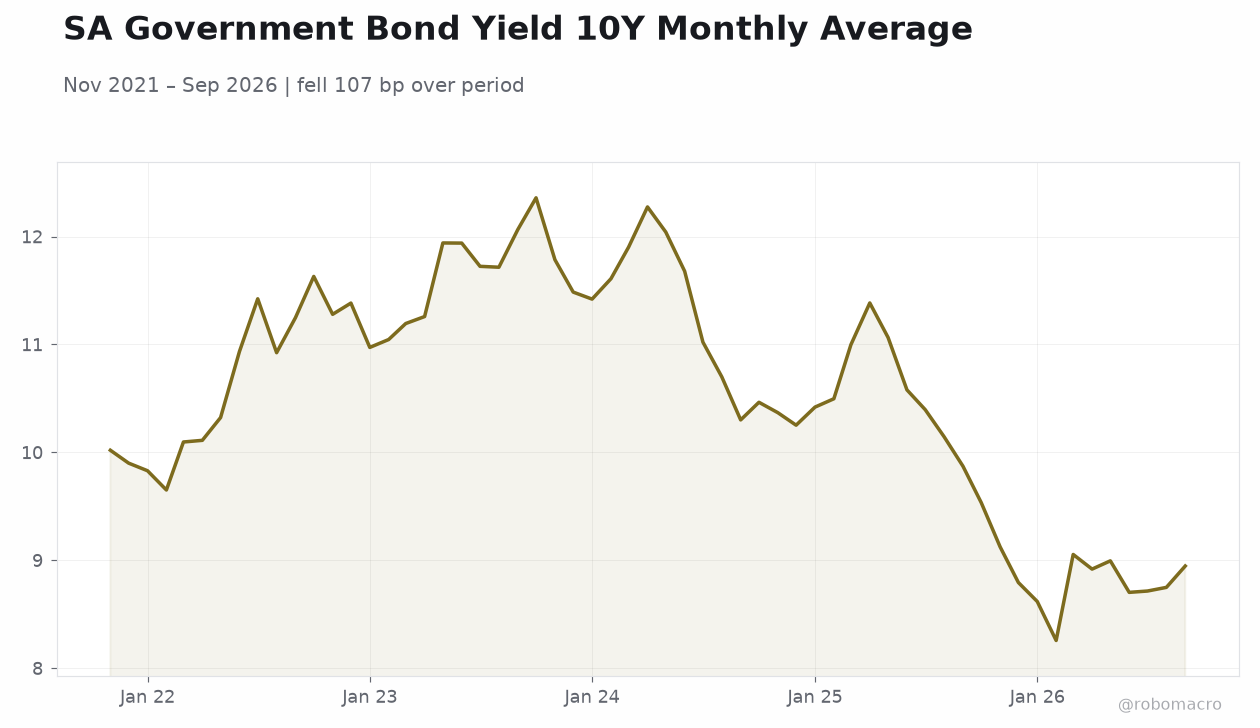
| South Africa 10Y Govt Yield | 8.84% | 0 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
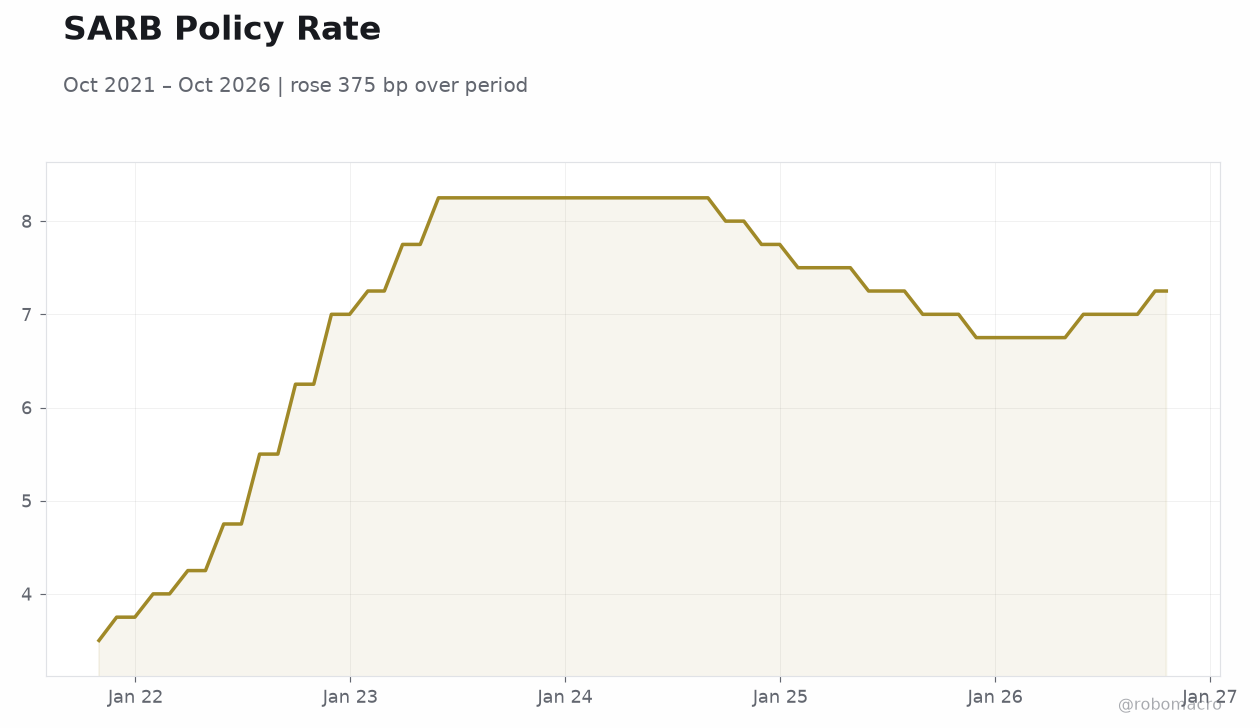 SARB Policy Rate | Type: macro_line | Policy Rate (%): 7.25 (2026-10-19) | Range: 3.5–8.25 | Trend(5pt): 3.5,7.25,8.25,7.25,7.25
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Friday (2026-10-30) | |||
| Trade Balance | 20,470m | - | 08:00 |
- USD/ZAR held near 16.66 (+0.15%) as the rand consolidated ahead of Friday's trade balance release and the 19 November SARB MPC.
- JSE Top 40 gained 0.63% to 101,609, led by Naspers (+2.48%) on Tencent strength; gold rose 0.90% to $4,074.60/oz.
- The 5-year yield added 3 bp to 8.62% while the 10-year held at 8.84%, steepening the front end modestly.
Yesterday's Recap
South African markets traded a quiet, range-bound session Tuesday with no domestic data releases on the calendar. The rand held steady around 16.66 against the dollar, with Reuters and CNBC Africa noting positioning ahead of leading indicator data and the looming Federal Reserve decision. The JSE Top 40 advanced 0.63% to 101,609, with Naspers up 2.48% to R69,400 as its Tencent stake tracked Asian tech strength.
Precious metals offered support, with gold up 0.90% to $4,074.60/oz, though platinum slipped 0.11% to $1,535.00. Brent crude fell 1.67% to $113.88/bbl, a modest positive for fuel-import costs. In fixed income, the 5-year yield rose 3 bp to 8.62% while the 10-year held at 8.84%, a mild front-end steepening that signals fiscal and term-premium caution rather than disorderly selling.
The Day Ahead
The domestic calendar is empty for Wednesday, leaving the rand and JSE to take direction from offshore risk sentiment and commodity prices. Attention turns to Friday's trade balance release (08:00 ET), where the prior print showed a surplus of R20.47 billion; consensus is not yet published. With gold near record highs and platinum firm, the trade account remains a key rand support channel, though softer Brent cuts both ways for import costs.
Traders will also watch the Fed decision overnight for dollar direction into Thursday. Locally, positioning ahead of the 19 November SARB MPC is likely to keep bond volumes light.
Other Economic Notes
South Africa's external position remains a relative bright spot, with the trade surplus and elevated gold prices underpinning the current account and rand resilience. However, the front-end steepening in the curve points to lingering concerns over fiscal consolidation and Treasury's borrowing trajectory. Energy supply remains a structural drag: load shedding risk and grid constraints continue to weigh on mining and manufacturing output, though platinum and gold producers benefit from strong dollar-denominated prices.
The Moneyweb narrative around South Africa's ambition to become a global financial centre is gaining traction, with reform of exchange controls and market infrastructure a potential medium-term tailwind for capital inflows. Inflation at 4.55% sits comfortably within the SARB's target band, giving the MPC room to hold rather than hike.