South Africa Macro Daily(Beta Mode)
SARB Signals 3% Inflation Goal Within Reach as Metals Slide
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| JSE Top 40 | 101,875.90 | +0.30% |
| USD/ZAR | 16.61 | -0.00% |
| EUR/ZAR | 18.60 | +0.37% |
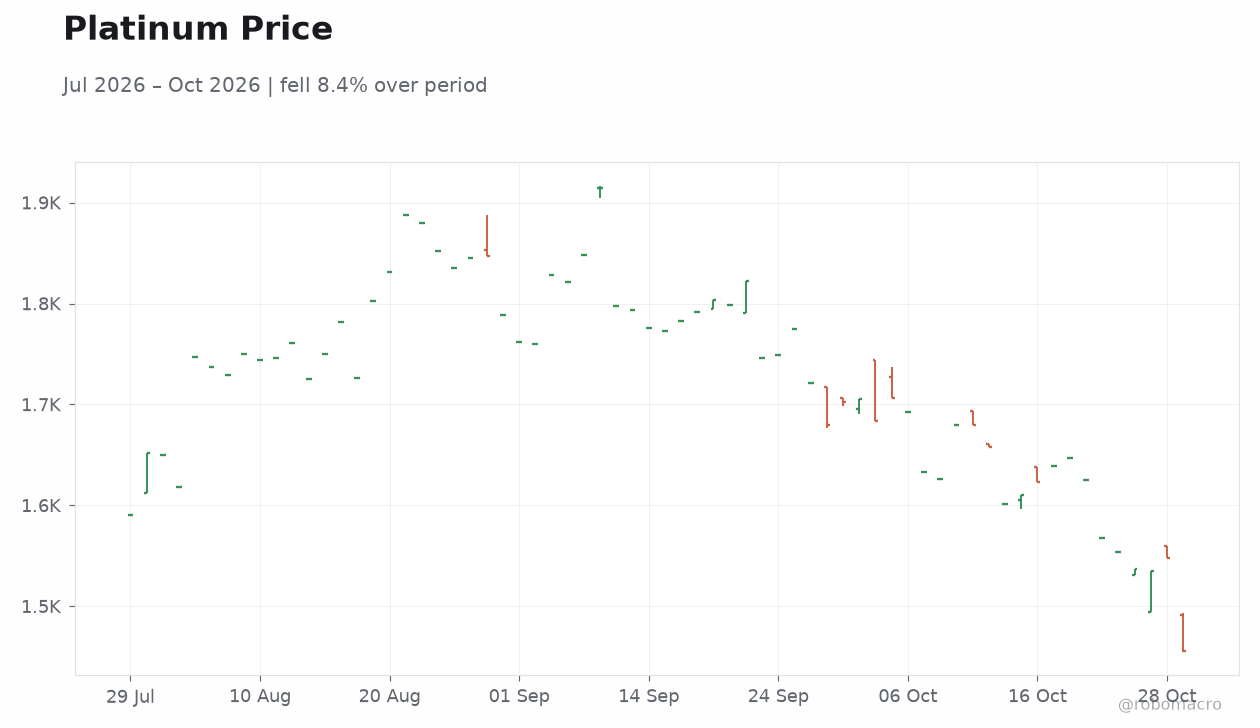
| Platinum | 1,456.50 | -5.90% |
| Gold | 4,003.20 | -1.19% |
| Brent Crude | 112.35 | -2.58% |
| Naspers | 68,971.00 | -0.16% |
| Bitcoin | 77,242.73 | -4.95% |
| South Africa 5Y Govt Yield | 8.58% | -2 bp |
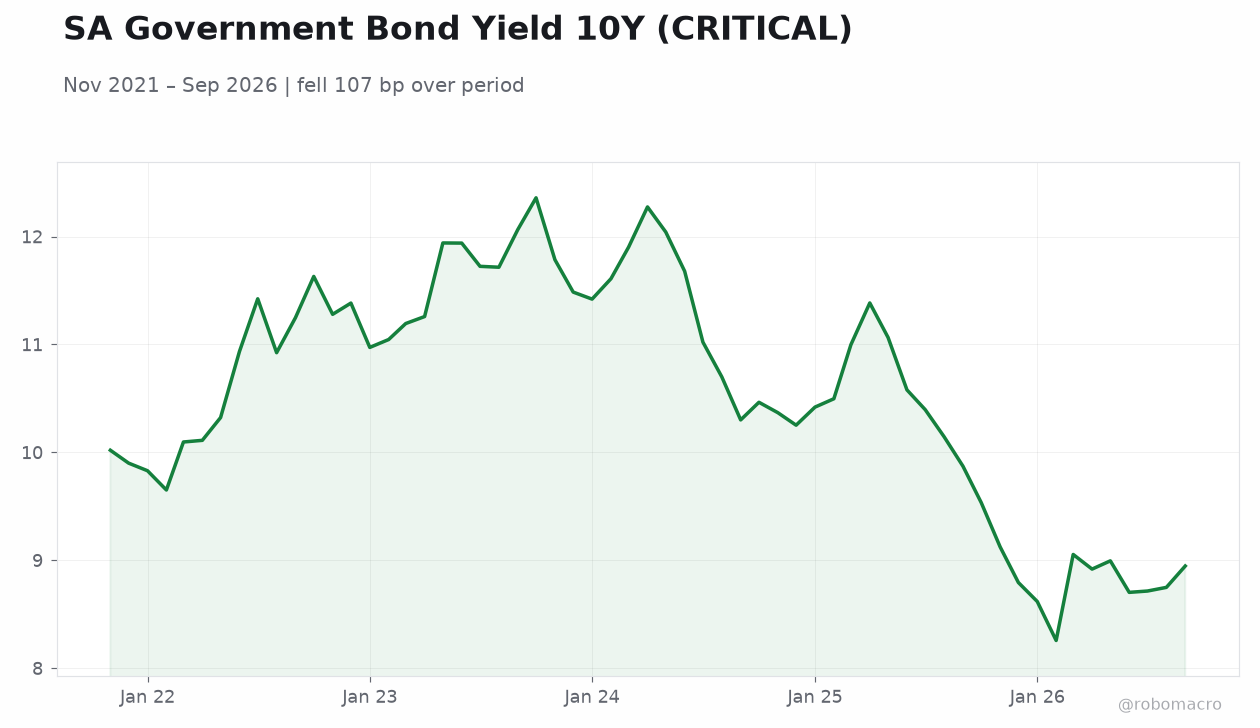
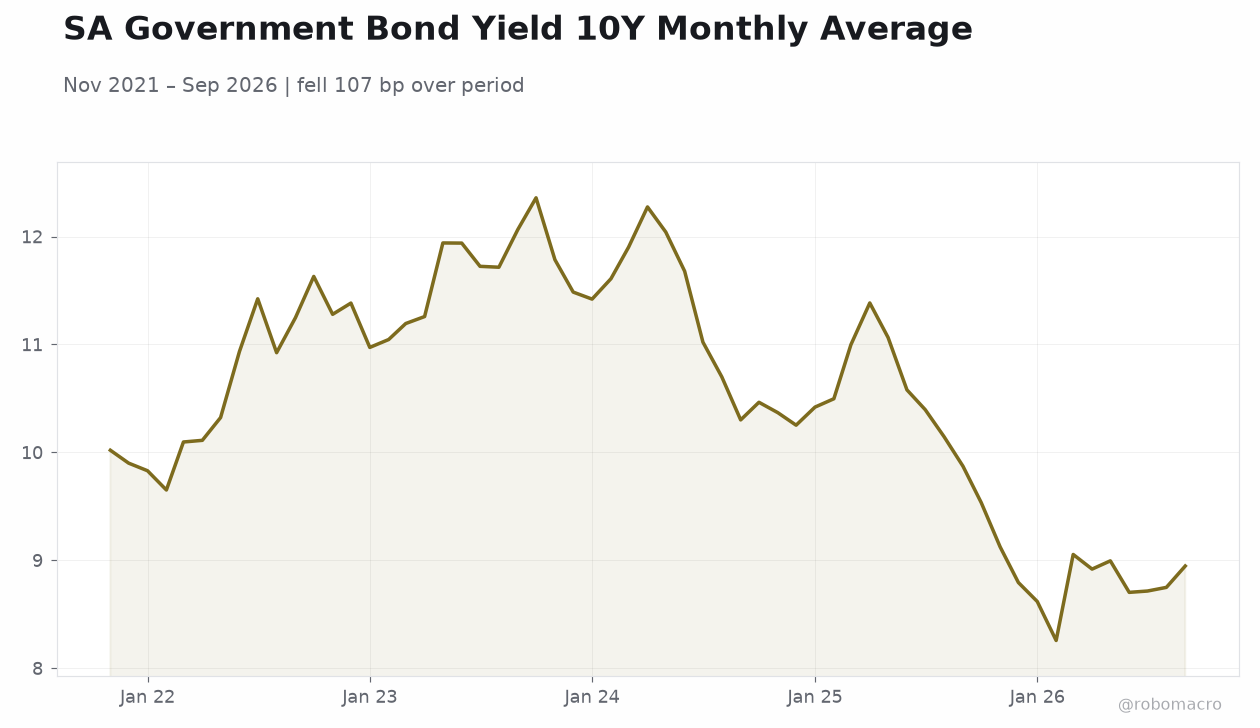
| South Africa 10Y Govt Yield | 8.79% | -2 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
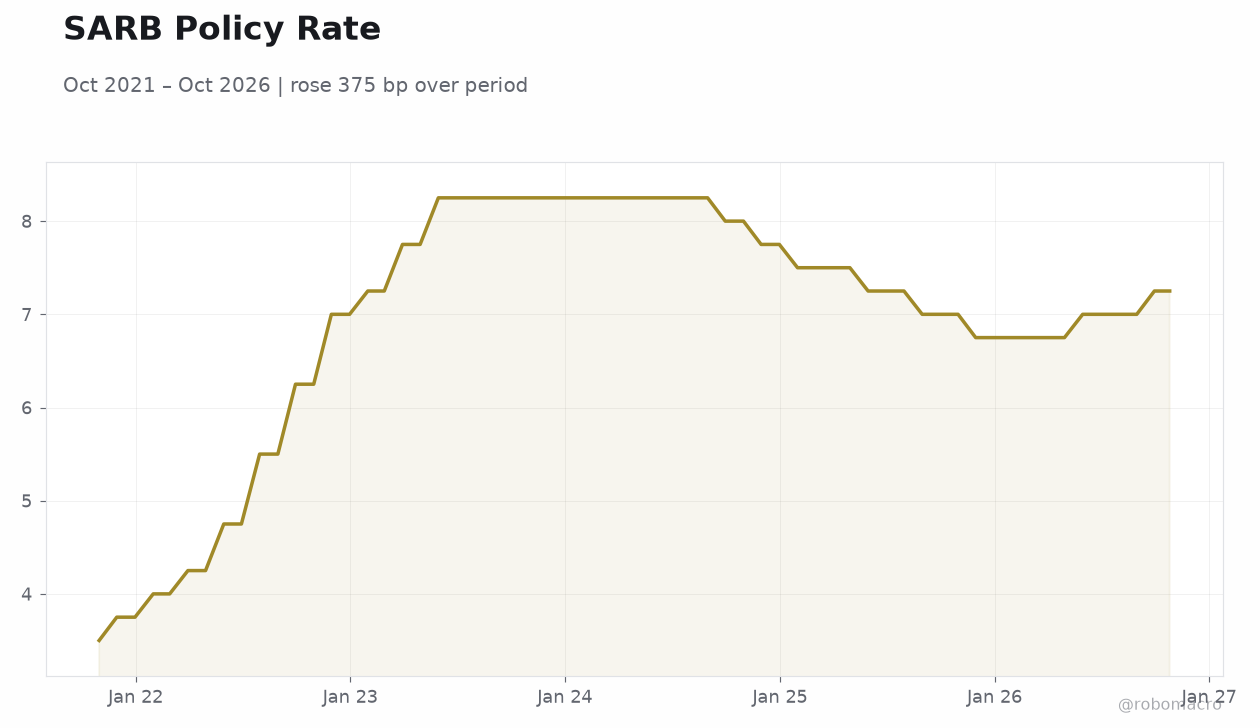 SARB Policy Rate | Type: macro_line | Policy Rate %: 7.25 (2026-10-26) | Range: 3.5–8.25 | Trend(5pt): 3.5,7.25,8.25,7.25,7.25
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Trade Balance | 20,470m | - | 08:00 |
- SARB Governor confident current policy stance can deliver inflation to the 3% target, reinforcing expectations of an extended hold at 7.25% ahead of the 19 November MPC.
- Rand flat near 16.61/USD but softer against the euro at 18.60 as gold (-1.19%) and platinum (-5.90%) sell off sharply, pressuring the trade balance outlook.
- JSE Top 40 edges up 0.30% while Naspers slips 0.16%; bond yields ease 2 bp across the curve, with the 10-year at 8.79% and 5-year at 8.58%.
Yesterday's Recap
No South African data releases were scheduled for Thursday, leaving markets to trade on global risk sentiment and commodity flows. The rand held essentially unchanged against the dollar at 16.61 but weakened 0.37% versus the euro to 18.60, reflecting broad dollar resilience rather than idiosyncratic ZAR stress. Precious metals drove the domestic narrative: platinum collapsed 5.90% to $1,456.50/oz and gold fell 1.19% to $4,003.20/oz, a combination that historically weighs on the rand and mining-sector earnings.
Brent crude dropped 2.58% to $112.35/bbl, offering modest relief to fuel-import costs. Onshore, the JSE Top 40 gained 0.30% to 101,875.90, with Naspers easing 0.16% to R68,971.00 as the tech proxy tracked softer global peers. Fixed income firmed, with the 5-year yield down 2 bp to 8.58% and the 10-year down 2 bp to 8.79%, suggesting investors remain comfortable with the disinflation trajectory.
The Day Ahead
The sole scheduled domestic release is the October trade balance at 08:00 ET, with the prior print at R20.47bn surplus and no consensus published. Given the sharp slide in platinum and gold prices during the week, the trade print will be scrutinised for early signs of export-revenue erosion, though customs data typically lags spot moves by a month. No other tier-one South African data is due, so rand direction will be dictated by offshore risk appetite and metals pricing.
Traders will also keep one eye on the benchmark rate law delay, where Treasury is reportedly preparing a backup plan — a story that could inject modest volatility into swap and bond curves. Liquidity should thin into the weekend, amplifying moves on any surprise in the trade number.
Other Economic Notes
The SARB's public confidence that its models can deliver 4.55% inflation marks a meaningful shift in the policy narrative, effectively pre-announcing a prolonged hold rather than a near-term cut. Civil society pushback on hyperscale AI data centres highlights a growing tension between the government's investment drive and Eskom's fragile grid, with water and power intensity a live constraint on new capex. ↓ p.2