South Africa Macro Daily(Beta Mode)
Rand, Bonds Slip as ANC Support Crumbles
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| JSE Top 40 | 105,225.90 | +3.99% |
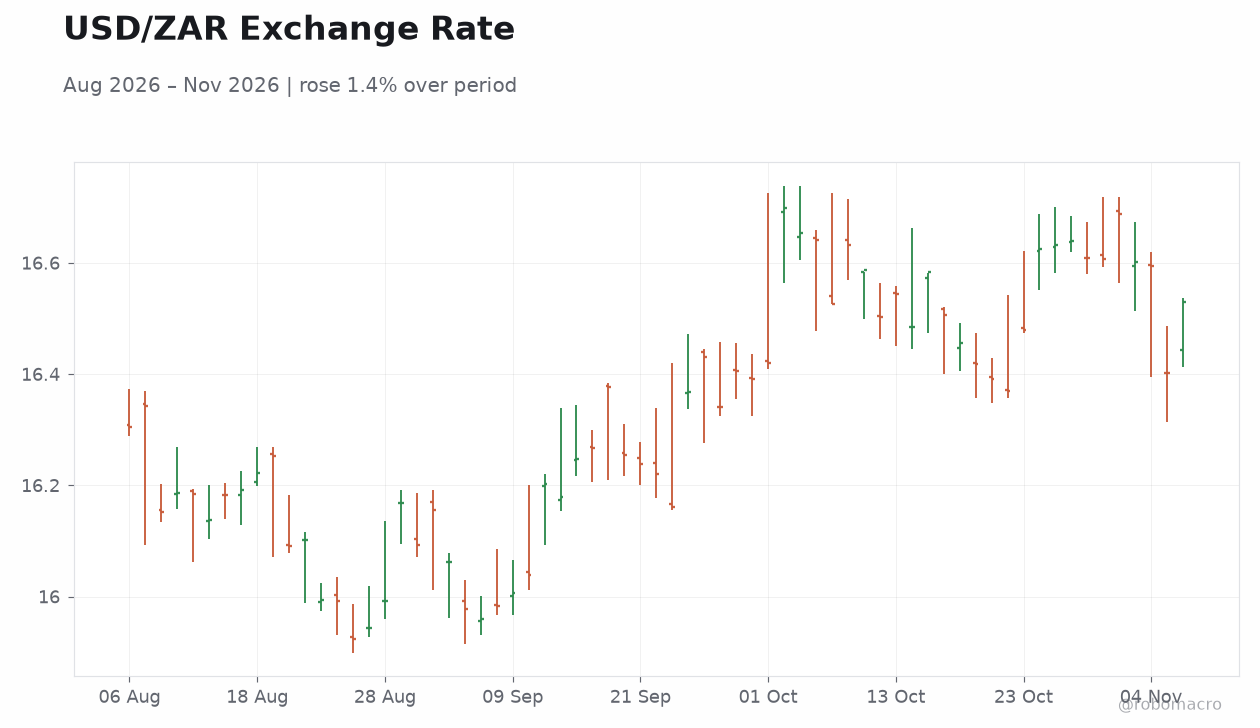
| USD/ZAR | 16.53 | +0.79% |
| EUR/ZAR | 18.50 | +0.46% |
| Platinum | 1,512.00 | +0.73% |
| Gold | 4,048.90 | -0.59% |
| Brent Crude | 100.02 | +5.71% |
| Naspers | 77,712.00 | +10.36% |
| Bitcoin | 75,538.87 | -6.05% |
| South Africa 5Y Govt Yield | 8.55% | +1 bp |
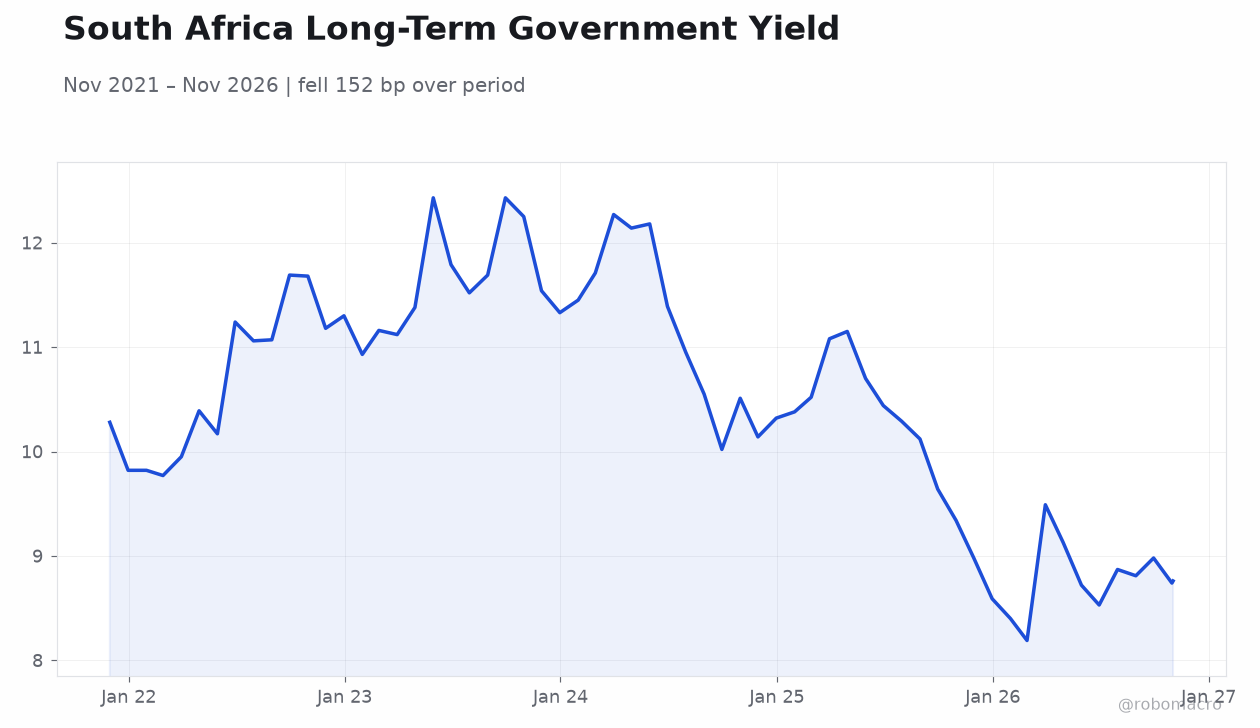
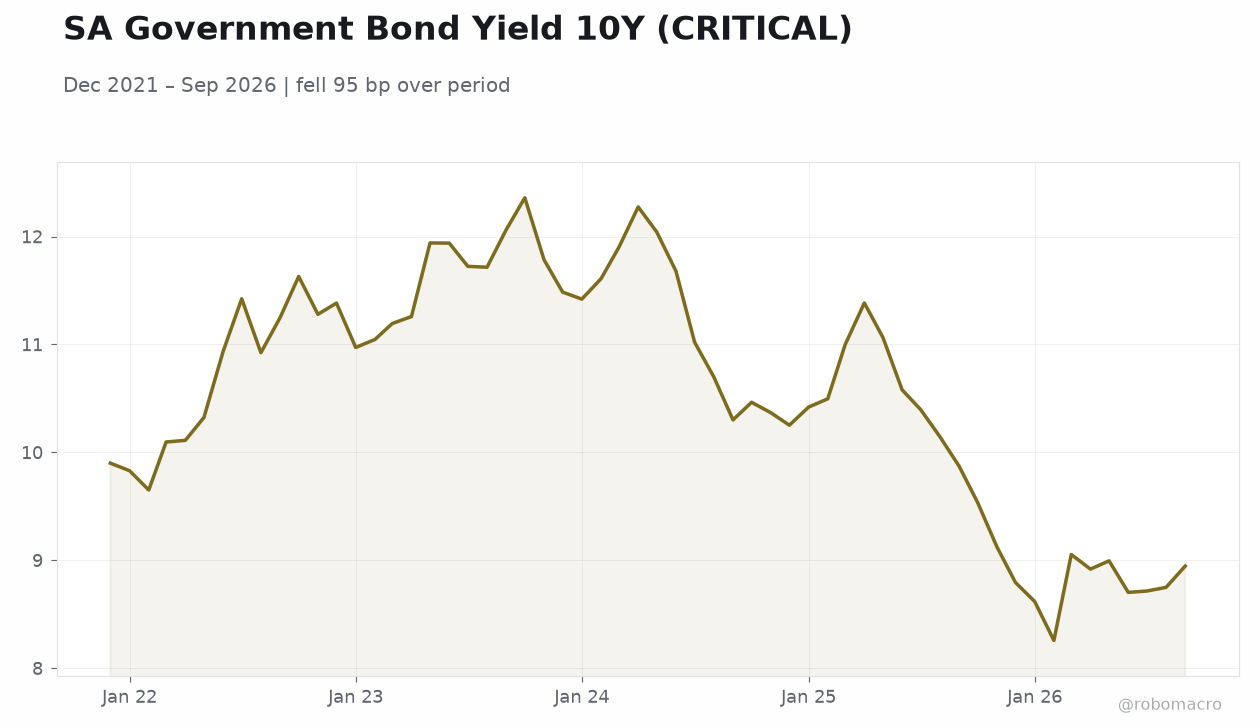
| South Africa 10Y Govt Yield | 8.76% | +2 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
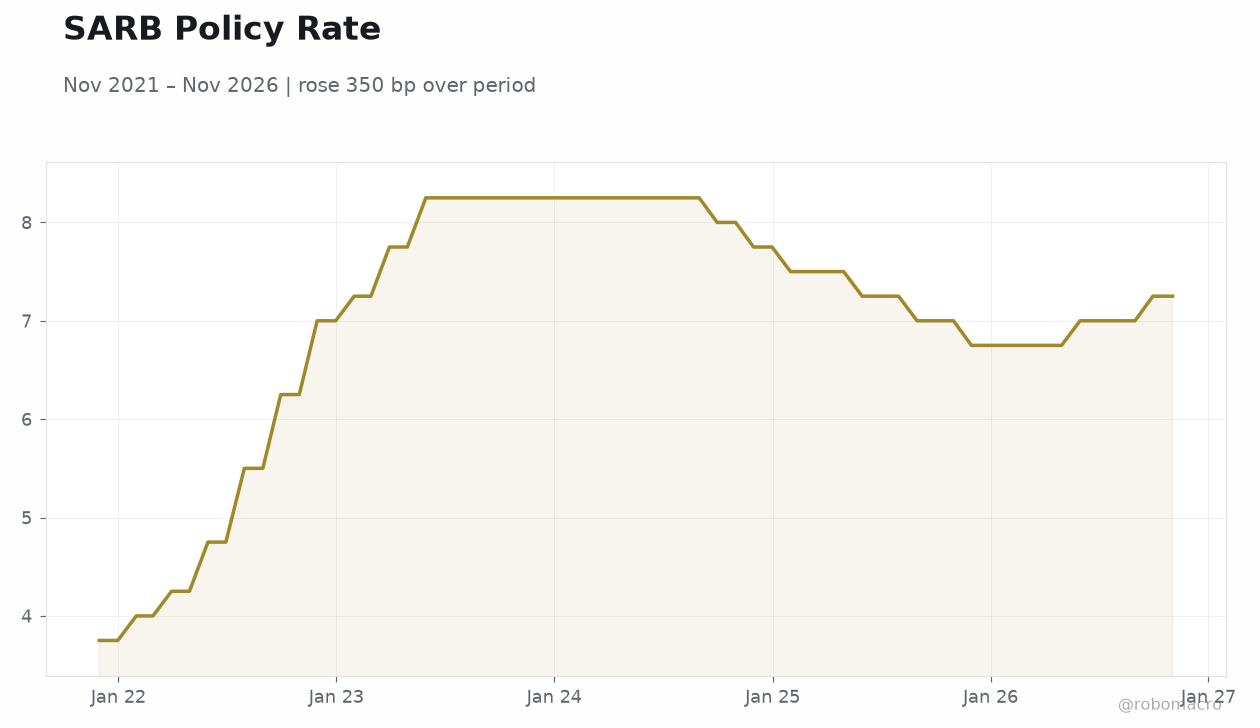 SARB Policy Rate | Type: macro_line | Policy Rate %: 7.25 (2026-11-02) | Range: 3.75–8.25 | Trend(5pt): 3.75,7.25,8.25,7,7.25
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- ANC on course for under a third of the vote in local elections, raising coalition and policy-continuity risk
- JSE Top 40 surges 3.99% on Naspers' 10.36% jump; USD/ZAR weakens 0.79% to 16.53
- Brent crude spikes 5.71% to $100.02, stoking imported inflation and SARB caution ahead of the 19 November MPC
Yesterday's Recap
South Africans voted in local government elections on 5 November, with the ANC expected to fall below a third of the national vote amid anger over water outages and power cuts, per Guardian and BBC reporting. Counting began immediately after polls closed, with final results due by Sunday, and more than 100 municipalities could end up under coalition control. Markets delivered a split verdict: the JSE Top 40 jumped 3.99% to 105,225.90, driven almost entirely by Naspers' 10.36% surge to R77,712, while the rand weakened 0.79% to 16.53 per dollar and EUR/ZAR rose 0.46% to 18.50.
Bond yields edged higher, with the 10-year up 2 bp to 8.76% and the 5-year up 1 bp to 8.55%, a modest backup consistent with stable-to-slightly-hawkish rate expectations rather than aggressive easing. Platinum gained 0.73% to $1,512 while gold slipped 0.59% to $4,048.90, and Brent crude spiked 5.71% to $100.02. Bitcoin fell 6.05% to $75,538.87, reflecting broader risk-asset volatility.
No scheduled South African data releases were recorded for the session.
The Day Ahead
No South African tier-one data releases are scheduled for Friday, 6 November, leaving markets to trade the election count and global risk sentiment. Attention centres on the pace of results from the municipal vote, with coalition arithmetic in the major metros likely to drive rand and bond direction into the weekend. Final results are due by Sunday, so positioning may stay cautious ahead of that outcome.
Traders will also watch Brent crude's push above $100 for second-round inflation implications. With the SARB MPC due 19 November, next week's data flow will matter more than today's empty calendar.
Other Economic Notes
The election result carries real macro weight: coalition fragmentation in key metros could slow service delivery and municipal investment, reinforcing the growth drag from water and electricity failures. Trade policy is a parallel concern — experts note only about 10% of South Africa's exports to the US fall under AGOA, roughly 1% of total global exports, so exclusion would not be catastrophic but would hit specific agricultural and manufacturing lines. South Africa is meanwhile eyeing China to diversify farm exports, a sensible hedge as US trade preferences wobble.
↓ p.2