South Africa Macro Daily(Beta Mode)
ANC Election Setback Clouds Policy Outlook
Market Snapshot
| Asset | Level | Change |
|---|---|---|
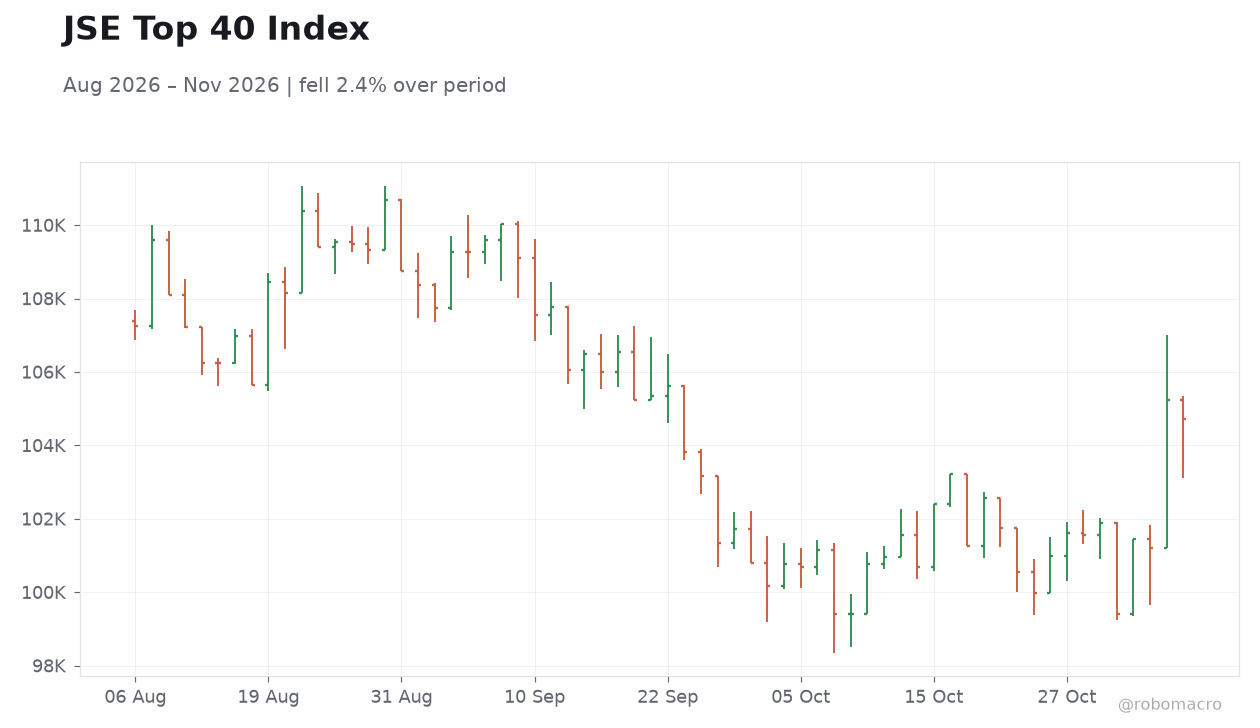
| JSE Top 40 | 104,714.00 | -0.49% |
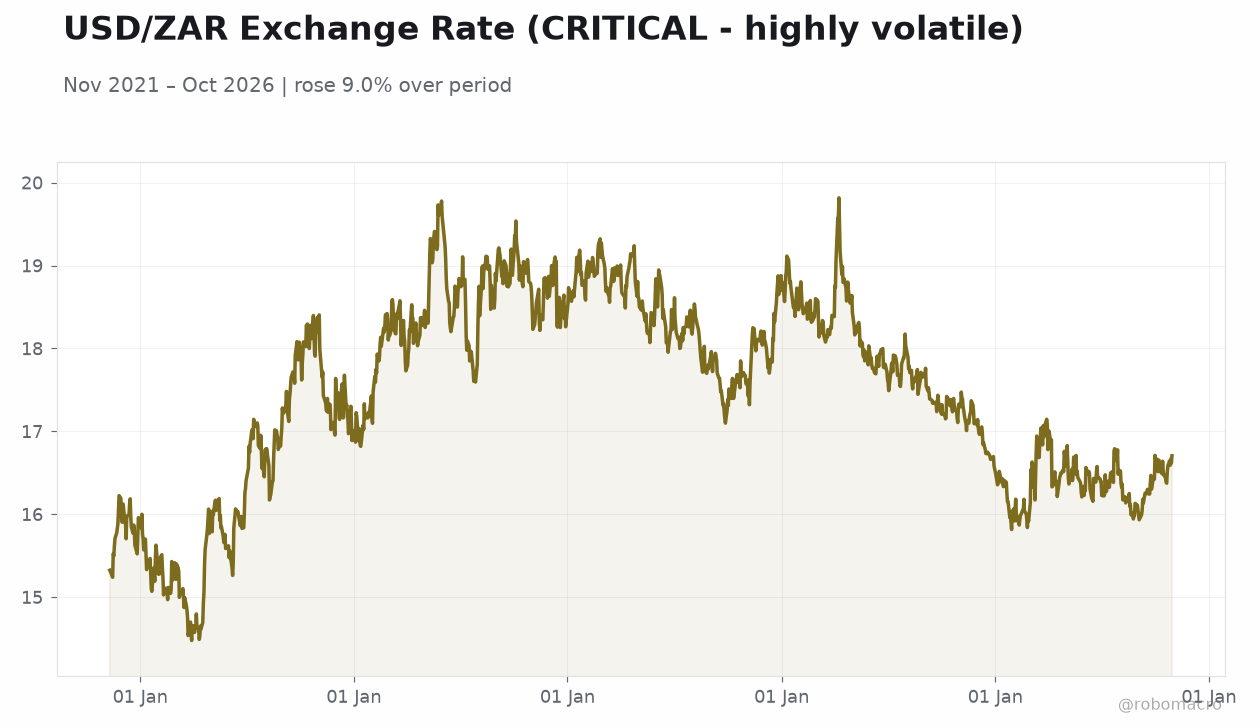
| USD/ZAR | 16.49 | +0.08% |
| EUR/ZAR | 18.40 | -0.48% |
| Platinum | 1,552.50 | +0.93% |
| Gold | 4,128.50 | +1.32% |
| Brent Crude | 98.28 | -0.04% |
| Naspers | 75,725.00 | -2.56% |
| Bitcoin | 74,889.47 | -1.13% |
| South Africa 5Y Govt Yield | 8.31% | -22 bp |
| South Africa 10Y Govt Yield | 8.54% | -19 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
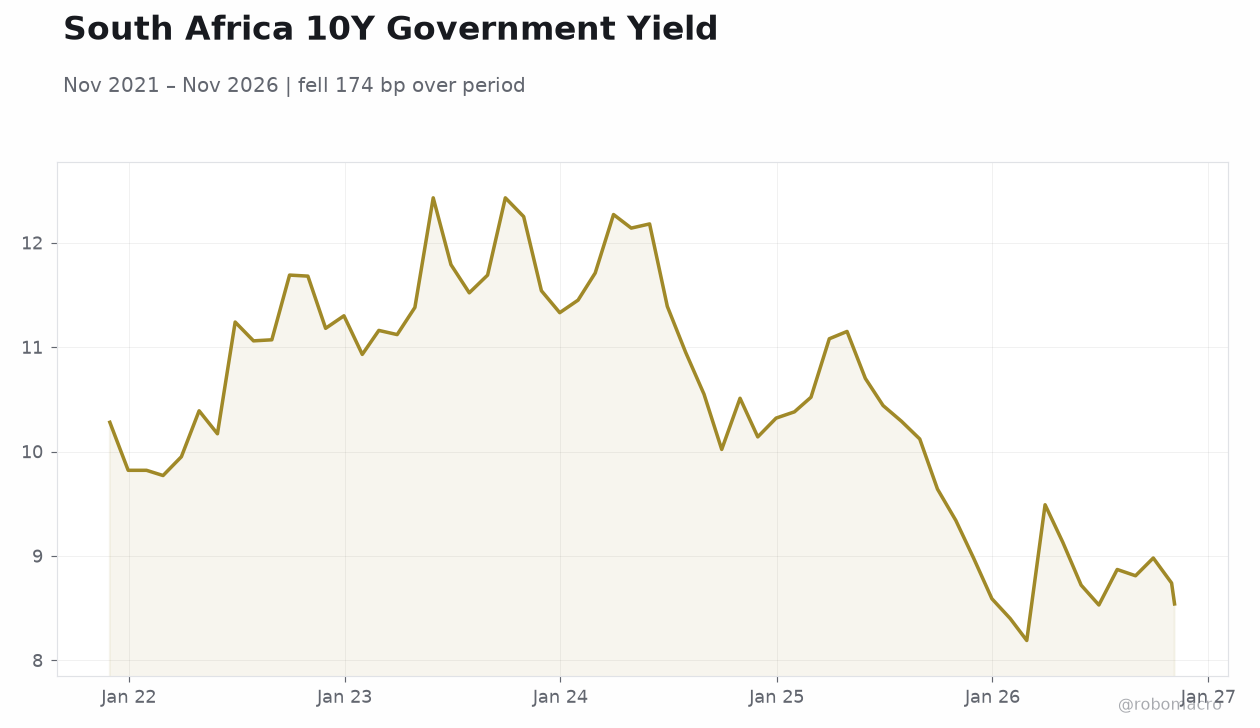 South Africa 10Y Government Yield | Type: macro_line | 10Y Yield (%): 8.54 (2026-11-05) | Range: 8.19–12.43 | Trend(5pt): 10.28,11.16,12.18,10.12,8.54
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Tuesday (2026-11-10) | |||
| Headline Unemployment Rate | 33.60 | - | 04:00 |
- ANC records worst-ever local election result, raising coalition and policy continuity risk
- JSE Top 40 slips 0.49% as Naspers drops 2.56%; rand steady near 16.49
- Bond yields fall sharply, 10Y down 19 bp to 8.54%, 5Y down 22 bp to 8.31%
Yesterday's Recap
South African markets closed Friday with equities under pressure as the JSE Top 40 fell 0.49%, weighed by a 2.56% decline in Naspers. The rand was broadly stable, with USD/ZAR edging up 0.08% to 16.49 while EUR/ZAR slipped 0.48% to 18.40. Fixed income rallied notably, with the 10-year government yield easing 19 bp to 8.54% and the 5-year dropping 22 bp to 8.31%, reflecting demand for duration amid political uncertainty.
Precious metals outperformed, with gold up 1.32% to $4,128.50/oz and platinum gaining 0.93% to $1,552.50/oz, supporting the mining complex. Brent crude was essentially flat at $98.28. No South African data releases were scheduled for the session, leaving markets to digest the ANC's historic electoral setback and its implications for coalition governance in key metros.
The Day Ahead
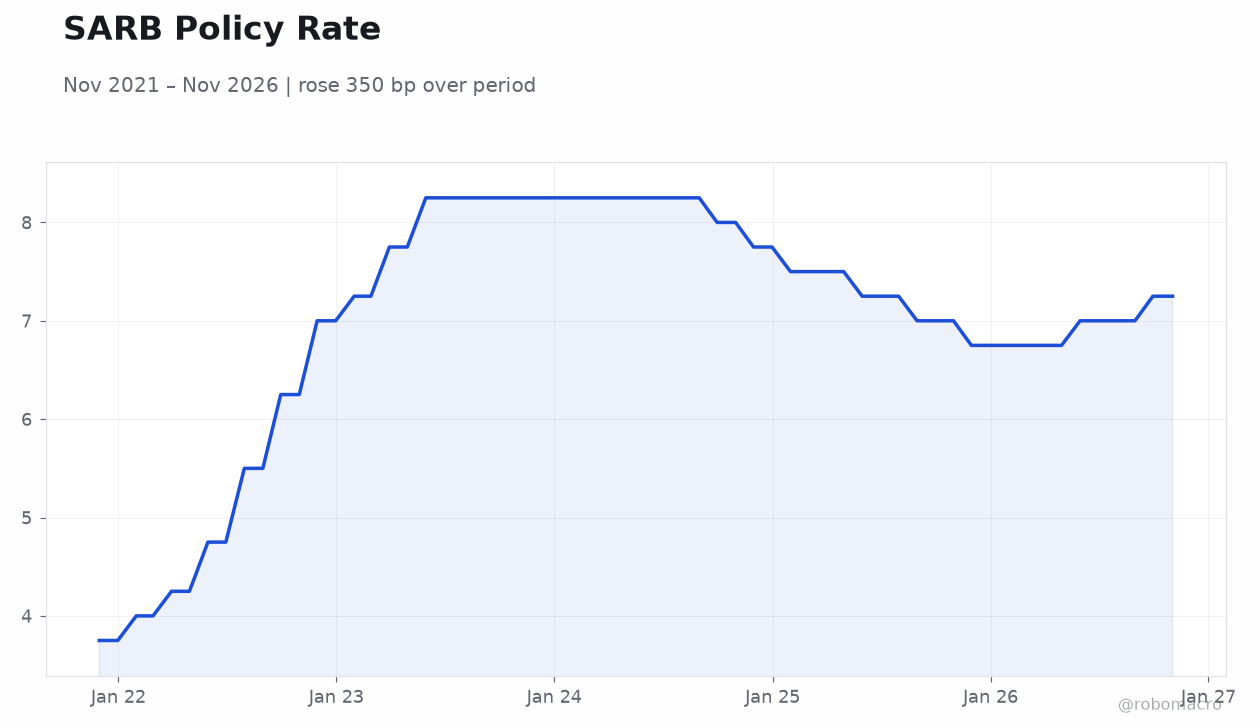
The focus turns to Tuesday's release of the headline unemployment rate at 04:00 ET, with the previous print at 33.6%. No consensus figure is available, so the market will watch for any deviation from the stubbornly high level that has characterised South African labour dynamics. The print carries medium impact and will be scrutinised for signs of cyclical improvement ahead of the SARB's November 19 MPC decision.
With no other domestic releases scheduled, trading will likely remain driven by election-related headlines and global risk sentiment. Liquidity may be thinner given the absence of major catalysts.
Other Economic Notes
The ANC's worst-ever local election performance — finishing first but with a sharply reduced share — sets the stage for difficult coalition negotiations in Johannesburg, Tshwane and eThekwini. Coalition fragmentation raises questions over municipal service delivery, infrastructure spending and the pace of reform, all of which feed into the sovereign credit narrative. Encouragingly, South Africa's exports to China have risen 25%, underscoring deepening trade ties with the world's second-largest economy and providing a partial offset to sluggish domestic demand.
The mining sector remains a key swing factor, with gold and platinum prices firm. Food security and diet-related health themes are gaining policy attention, though near-term macro relevance is limited.