South Africa Macro Daily(Beta Mode)
Rand Slides to Seven-Month Low Before SARB
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| JSE Top 40 | 104,486.60 | -0.47% |
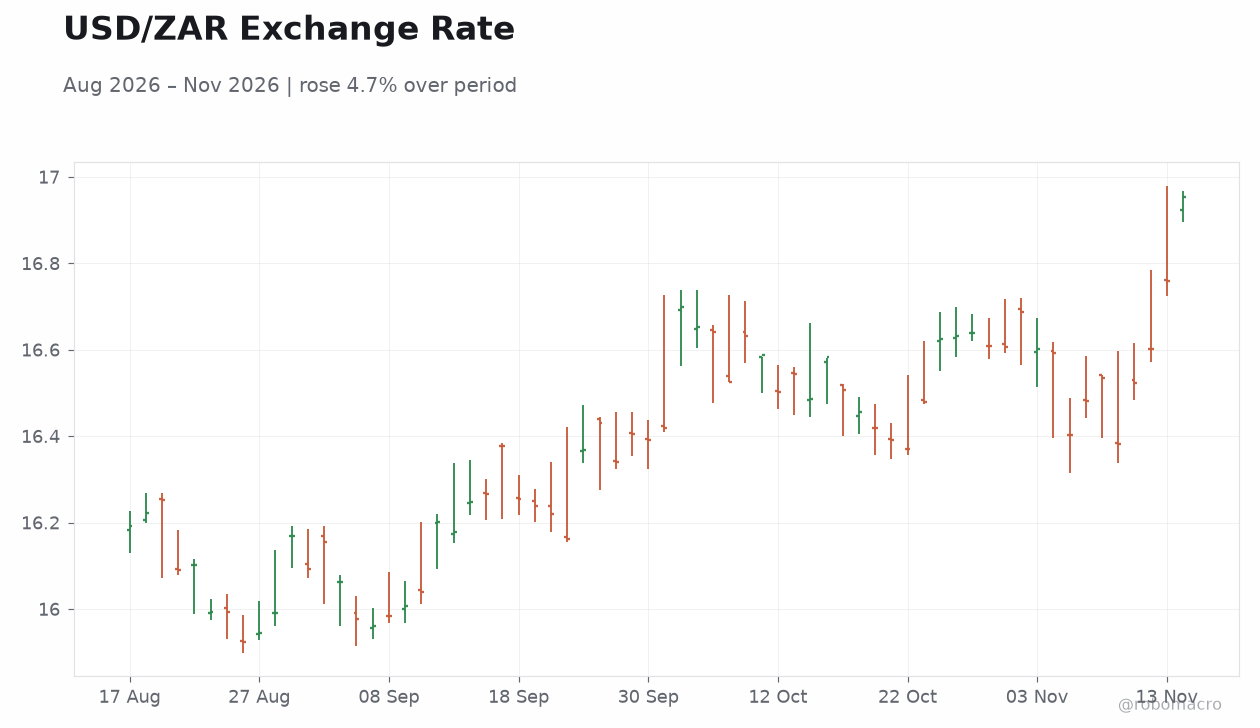
| USD/ZAR | 16.96 | +1.19% |
| EUR/ZAR | 18.67 | +0.87% |
| Platinum | 1,478.00 | -0.71% |
| Gold | 3,874.70 | -0.30% |
| Brent Crude | 95.39 | -0.47% |
| Naspers | 72,537.00 | -1.42% |
| Bitcoin | 65,000.28 | +1.36% |
| South Africa 5Y Govt Yield | 8.21% | -17 bp |
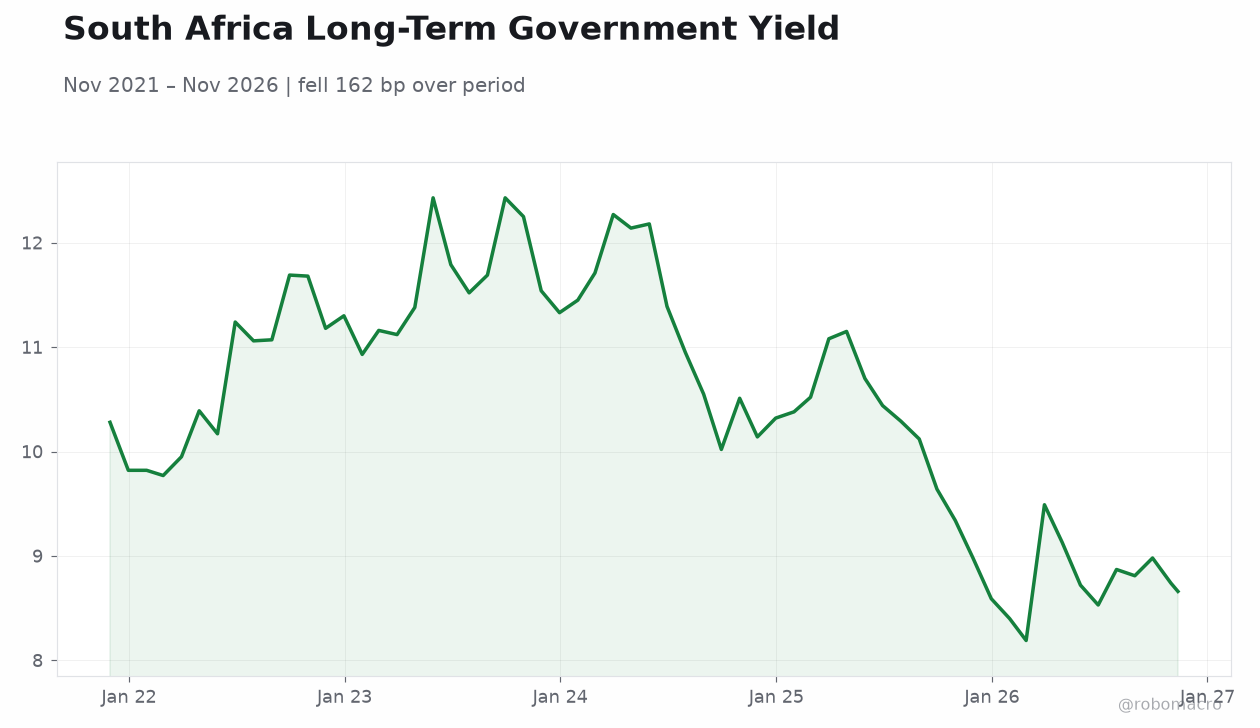
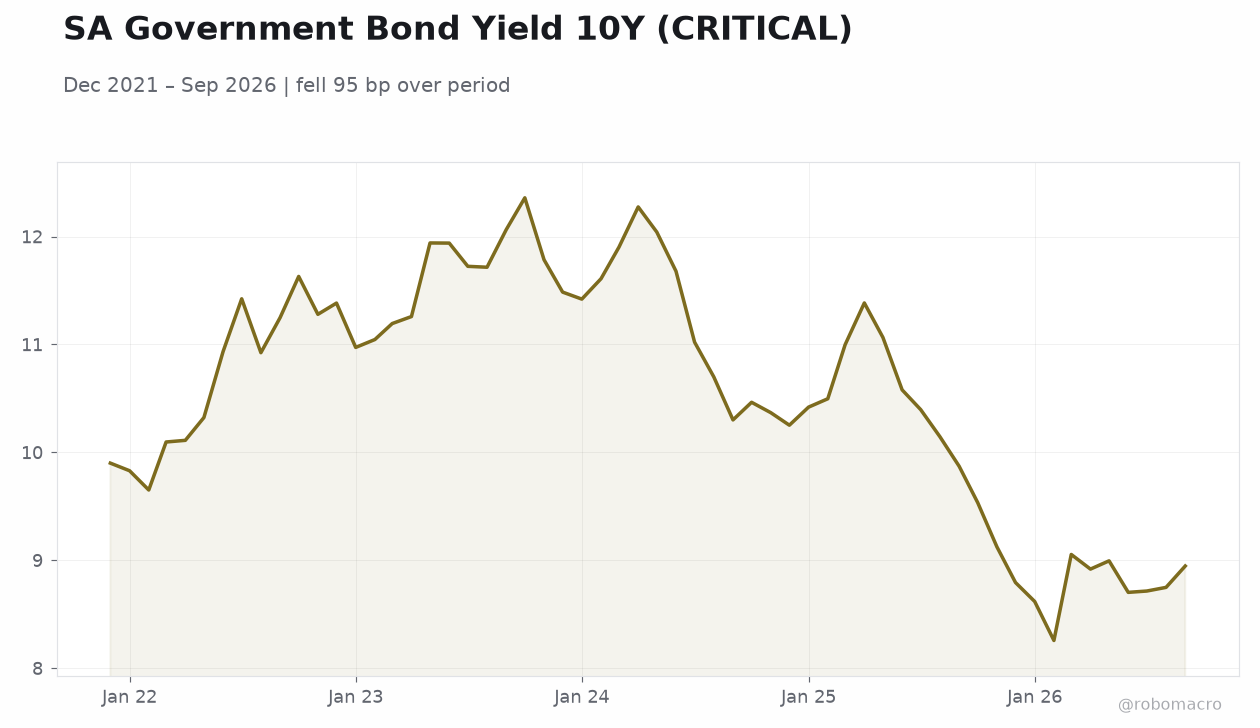
| South Africa 10Y Govt Yield | 8.66% | +8 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
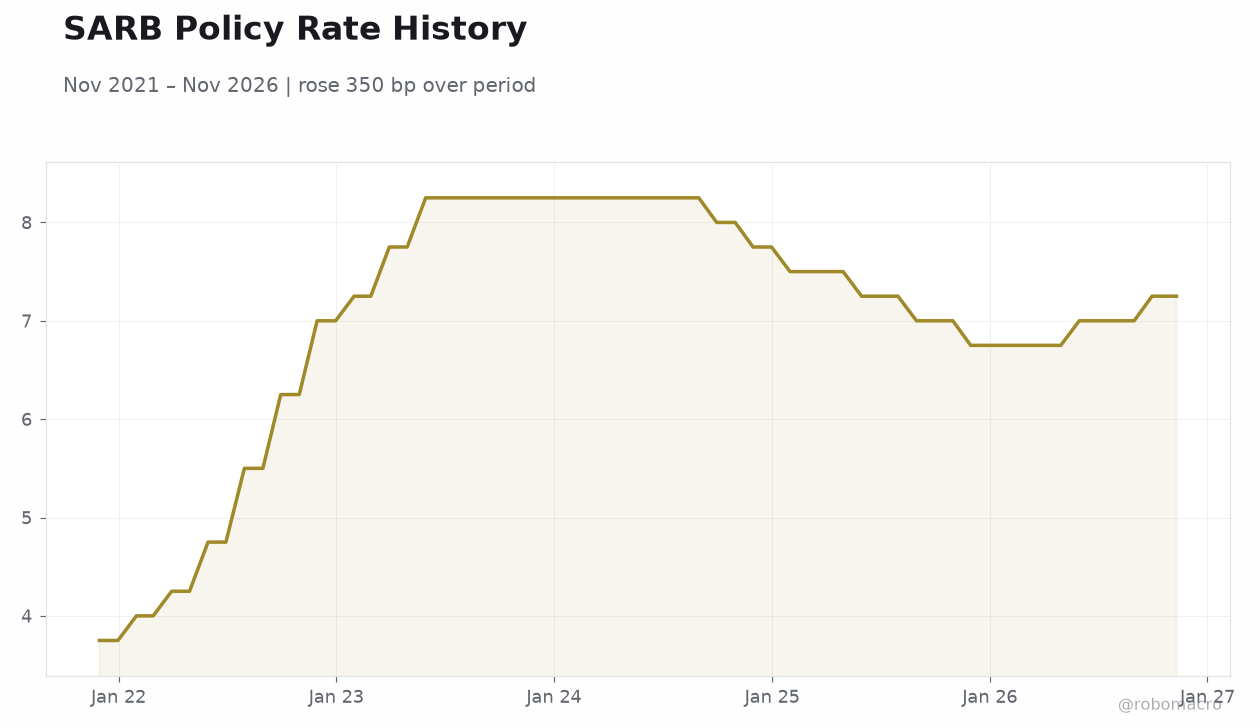 SARB Policy Rate History | Type: macro_line | Policy Rate %: 7.25 (2026-11-10) | Range: 3.75–8.25 | Trend(5pt): 3.75,7.25,8.25,7,7.25
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- USD/ZAR jumped 1.19% to 16.96, sliding toward a seven-month low as markets brace for Wednesday's CPI print and Thursday's SARB decision.
- JSE Top 40 fell 0.47% to 104,486.60, with Naspers down 1.42%; the 10-year yield rose 8 bp to 8.66% while the 5-year eased 17 bp to 8.21%.
- Economists widely expect the SARB to hold the repo rate at 7.25% on 19 November despite rising inflation pressures.
Yesterday's Recap
Friday's session was dominated by rand weakness, with USD/ZAR climbing 1.19% to 16.96 and EUR/ZAR rising 0.87% to 18.67 — the currency sliding toward a seven-month low per Reuters and Finimize reporting. The JSE Top 40 shed 0.47% to 104,486.60, led lower by Naspers, which fell 1.42% to 72,537.00. The bond curve dislocated: the 10-year yield rose 8 bp to 8.66% while the 5-year eased 17 bp to 8.21%, a steepening move suggesting duration risk premium building into the SARB meeting.
Commodity-linked names faced headwinds as platinum dropped 0.71% to 1,478.00 and gold slipped 0.30% to 3,874.70. Brent crude fell 0.47% to 95.39, offering limited relief to fuel-price dynamics. No official South African data releases were scheduled, leaving FX and rates positioning ahead of the SARB call as the dominant driver.
The Day Ahead
Monday's domestic calendar is empty, so attention shifts to the week's pivotal events: September CPI data on Wednesday and the SARB's final MPC decision of 2026 on Thursday. Markets will watch the rand closely after its slide toward 17.00, with FXLeaders flagging USD/ZAR heading toward that psychological level. Bond traders will monitor whether the 10-year yield's 8 bp rise extends, given the 5s10s steepening seen Friday.
Mining equities remain sensitive to platinum and gold price action amid global risk-off sentiment. With no local prints, offshore cues — particularly US rates and dollar direction — will set the tone for JSE and ZAR trading.
Other Economic Notes
The rand's slide to a seven-month low reflects a confluence of domestic political noise and external dollar strength. The ANC's national leadership backed President Ramaphosa despite last week's local election losses, removing immediate political uncertainty but underscoring the party's weakening electoral position. South Africa's gambling sector continues to expand rapidly — R1.76 trillion wagered last year, mostly via mobile — drawing regulatory and tax attention.
Mining remains a swing factor for both GDP and the trade balance, with platinum-group metal prices soft. Fiscal consolidation pressures persist as the state balances social spending against debt-service costs, keeping the bond curve steep.