South Africa Macro Daily(Beta Mode)
Rand Slides as CPI Surges, SARB Decision Looms
Market Snapshot
| Asset | Level | Change |
|---|---|---|
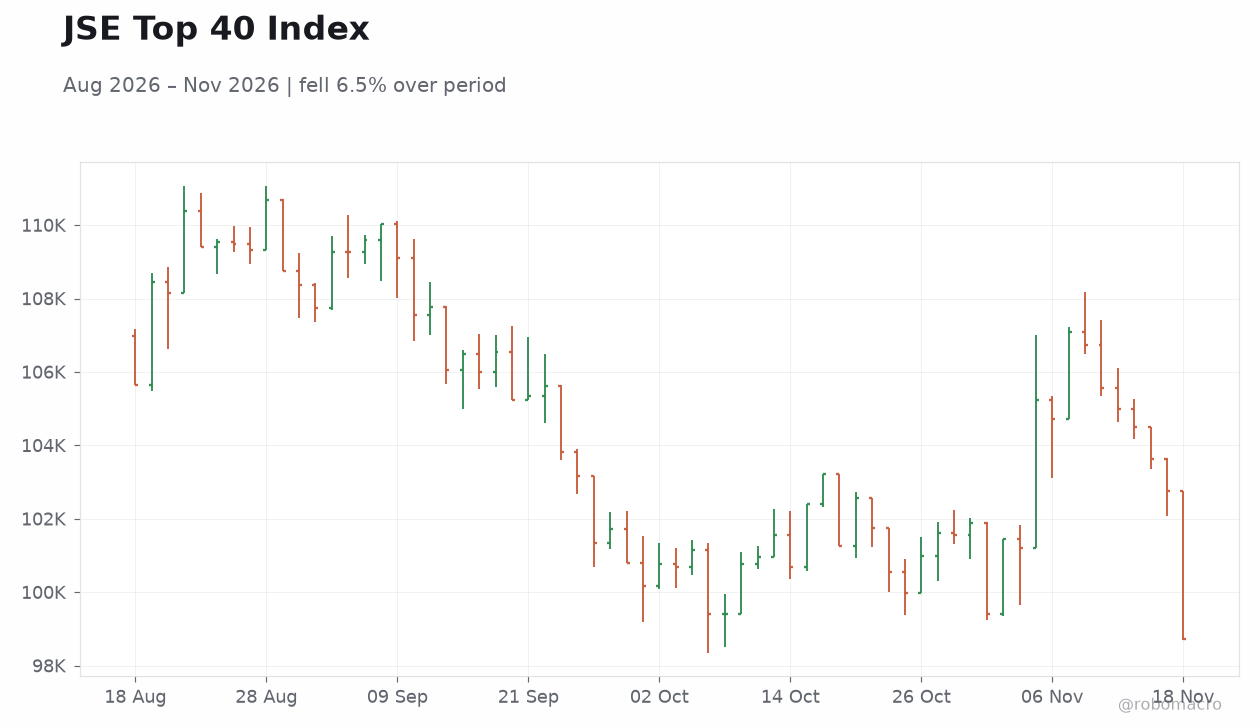
| JSE Top 40 | 98,732.70 | -3.91% |
| USD/ZAR | 17.34 | +2.56% |
| EUR/ZAR | 19.01 | +2.30% |
| Platinum | 1,364.40 | -4.33% |
| Gold | 3,726.30 | -3.57% |
| Brent Crude | 89.23 | -4.20% |
| Naspers | 67,579.00 | -5.80% |
| Bitcoin | 63,211.35 | -2.59% |
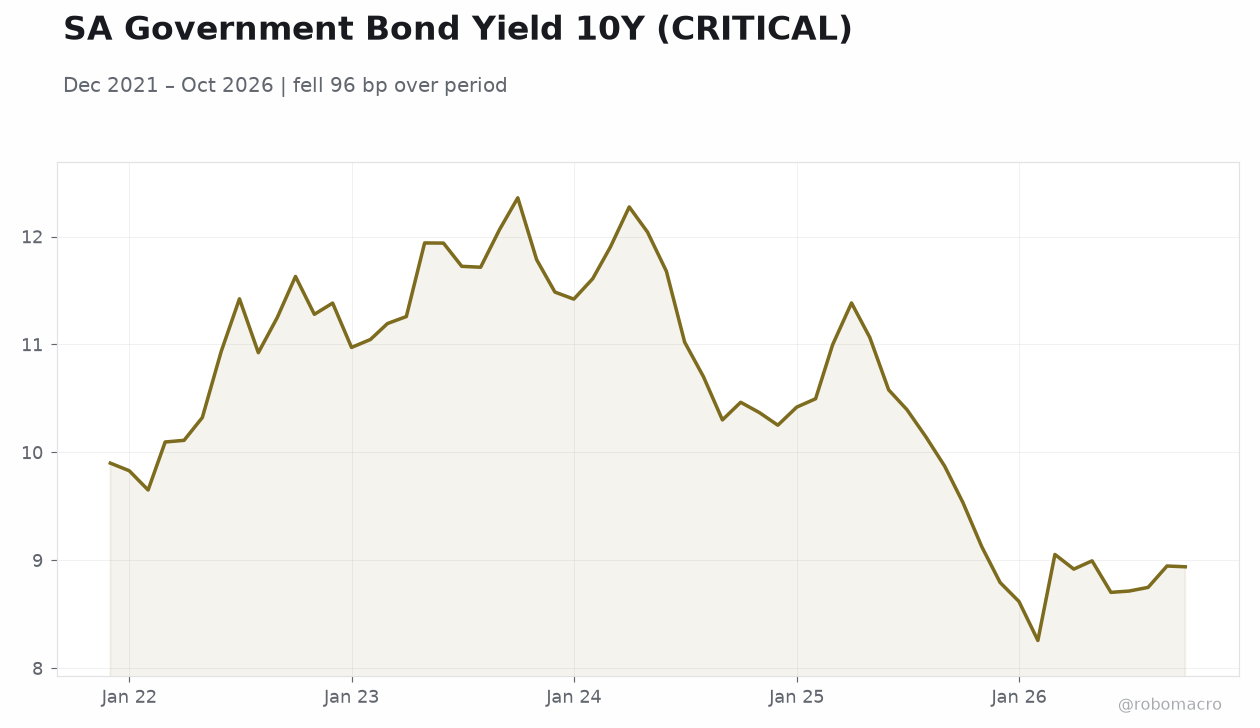
| South Africa 5Y Govt Yield | 8.57% | +3 bp |
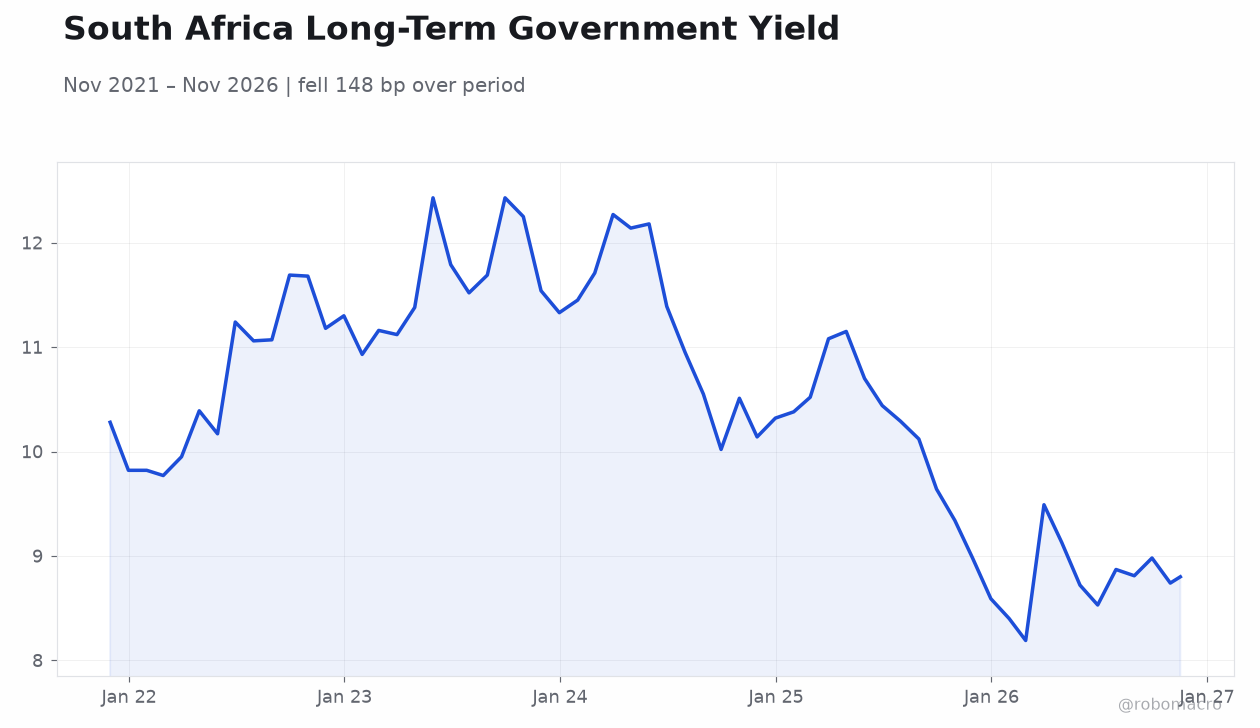
| South Africa 10Y Govt Yield | 8.80% | +4 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| Inflation Rate Month-over-Month | 0.40 | - | 0.70 |
| Inflation Rate Year-over-Year | 4.50 | 5.20 | 5.20 |
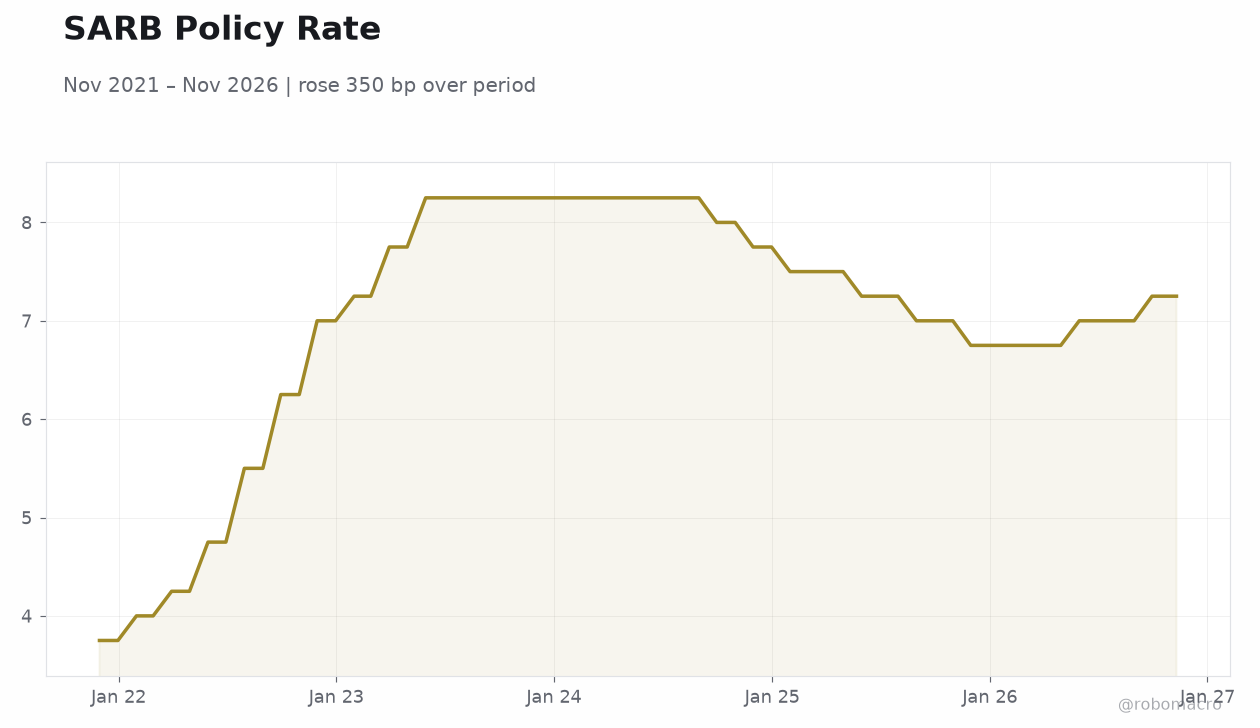 SARB Policy Rate | Type: macro_line | Policy Rate (%): 7.25 (2026-11-10) | Range: 3.75–8.25 | Trend(5pt): 3.75,7.25,8.25,7,7.25
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Central Bank Interest Rate Decision | 7.25 | 7.25 | 08:00 |
- October CPI accelerated to 5.2% y/y (0.7% m/m), matching consensus and marking the fastest pace since 2024, keeping the SARB firmly on hold at today's MPC decision.
- The rand weakened past 17.34/USD (+2.56% d/d) to a seven-month low as risk-off swept global markets, with the JSE Top 40 down 3.91% and Naspers off 5.80%.
- The SARB is widely expected to hold the repo rate at 7.25% today, with markets focused on forward guidance after September's 25bp hike.
Yesterday's Recap
South Africa's October CPI printed at 5.2% y/y, in line with consensus and up from 4.5% previously, while month-over-month inflation accelerated to 0.7% from 0.4%. The outcome confirms the inflation upswing that prompted the SARB's 25bp hike to 7.25% in September and leaves real rates compressed ahead of today's decision. Markets were decisively risk-off: the rand weakened 2.56% to 17.34/USD, touching a seven-month low, and EUR/ZAR rose 2.30% to 19.01.
The JSE Top 40 fell 3.91% to 98,732.70, with Naspers down 5.80% at R67,579 as global tech sentiment soured. Commodity-linked names bore the brunt of the selloff — platinum dropped 4.33% to $1,364.40 and gold fell 3.57% to $3,726.30, while Brent crude slid 4.20% to $89.23. Domestic bond yields edged higher, with the 10-year up 4bp to 8.80% and the 5-year up 3bp to 8.57%, reflecting both the inflation print and global duration pressure.
The Day Ahead
All eyes are on the SARB's central bank interest rate decision at 08:00 ET (14:00 SAST), with consensus firmly anchored at a hold at 7.25% following September's hike. The statement and press conference will be scrutinised for guidance on whether the September move marked the peak of this tightening cycle or whether further action is possible should inflation expectations de-anchor. Given October CPI at 5.2% sits above the 4.5% midpoint of the 3-6% target range, the committee faces a delicate communication challenge.
No other tier-one South African data is scheduled for today or tomorrow, so the MPC outcome and accompanying rhetoric will dominate domestic price action into the weekend. Rand reaction function will hinge on the tone of the guidance rather than the decision itself.
Other Economic Notes
The inflation acceleration to 5.2% y/y — the fastest since 2024 — narrows the SARB's room for manoeuvre and complicates the fiscal backdrop, with debt-service costs sensitive to the 8.80% 10-year yield. Mining-sector pressure is evident in platinum's 4.33% slide, with PGM producers facing both weaker prices and rand-cost inflation. The rand's slide to a seven-month low injects imported inflation risk into the goods basket, a channel the MPC will weigh carefully.
↓ p.2