UK Macro Daily(Beta Mode)
Labour Data Tests BoE Hold View
Market Snapshot
| Asset | Level | Change |
|---|---|---|
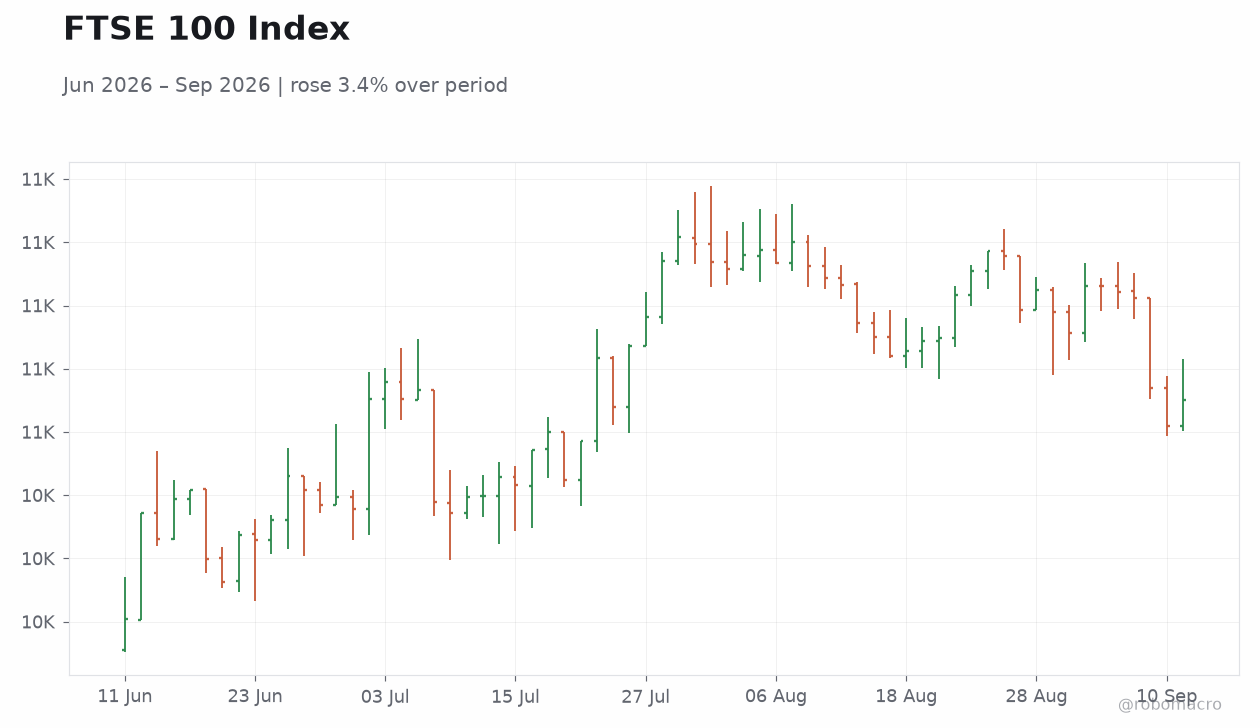
| FTSE 100 | 10,650.40 | +0.39% |
| FTSE 250 | 23,975.70 | +0.38% |
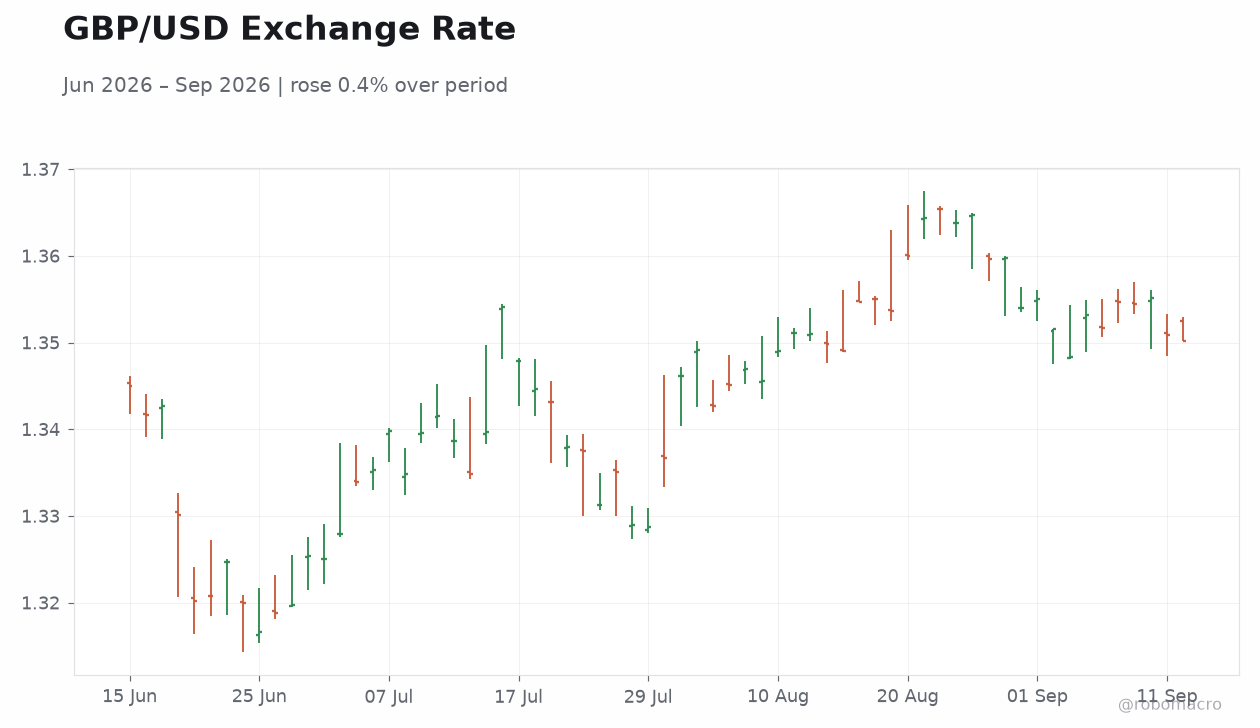
| GBP/USD | 1.35 | -0.04% |
| GBP/EUR | 1.17 | +0.28% |
| GBP/JPY | 208.02 | -0.32% |
| Brent Crude | 106.99 | +2.28% |
| Gold | 4,369.50 | +0.08% |
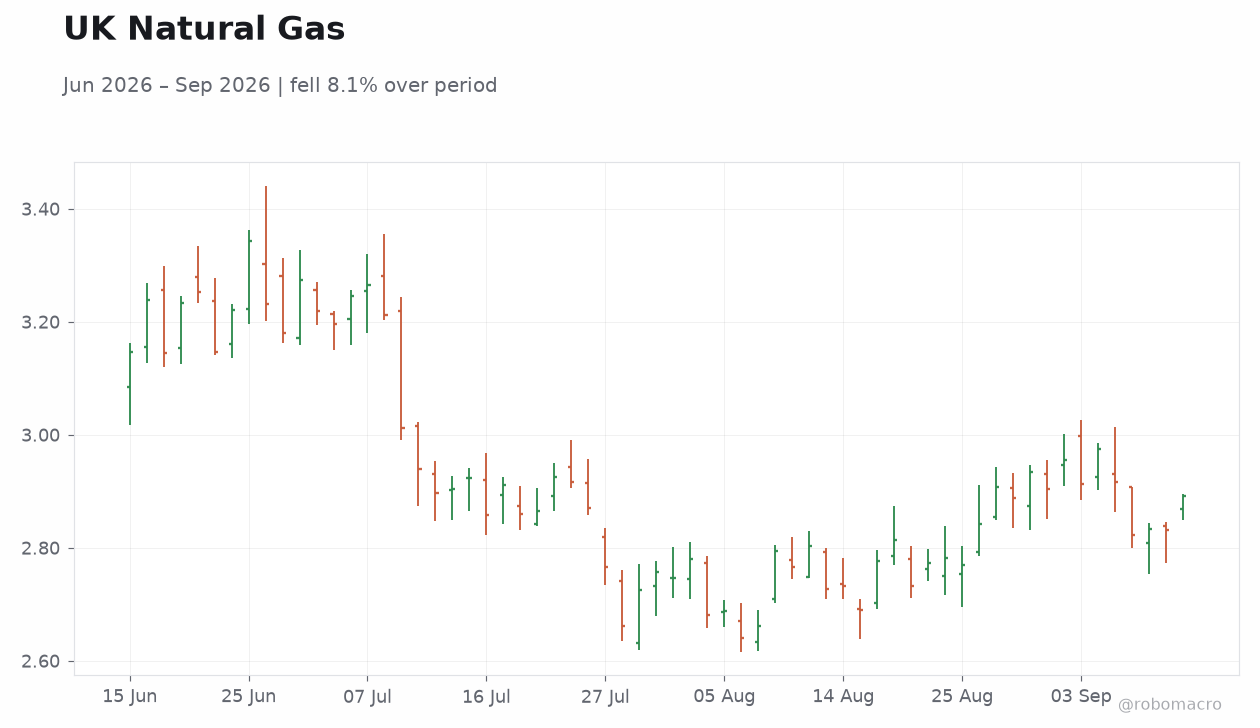
| UK Nat Gas | 2.89 | +2.08% |
| Bitcoin | 77,631.16 | +0.47% |
| UK 2Y Gilt | - | - |
| UK 10Y Gilt | 4.80% | -2.95% |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
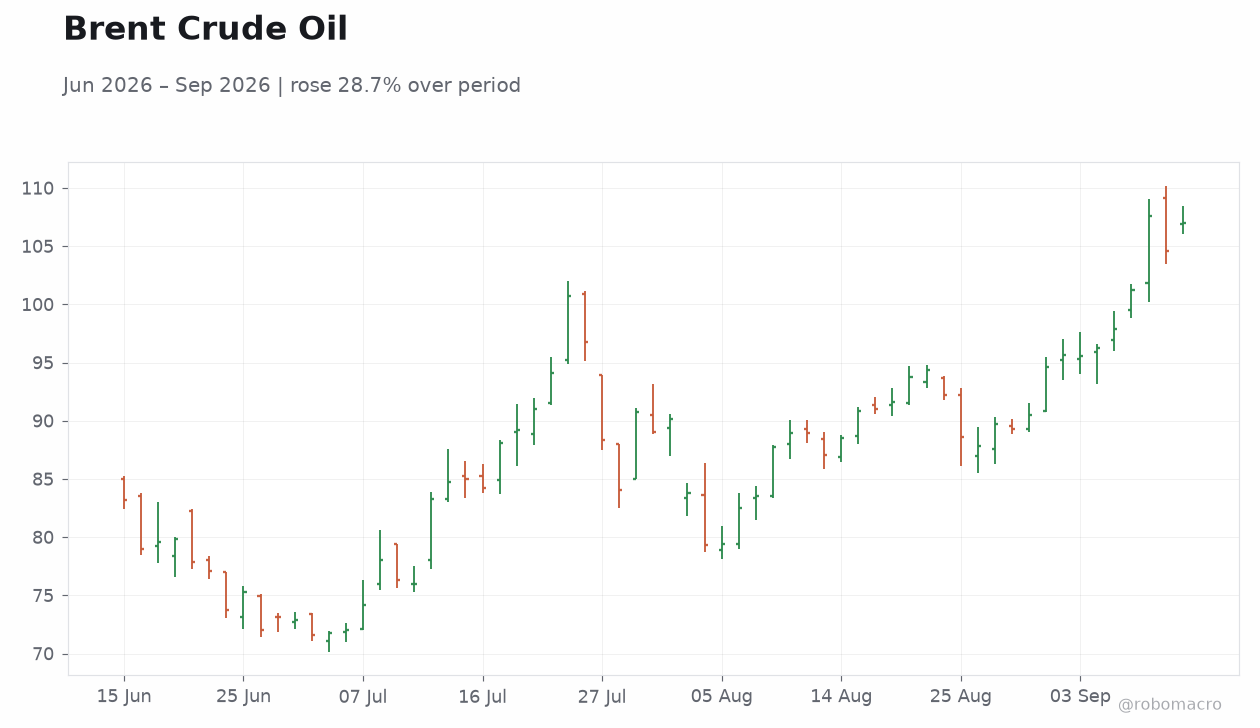 Brent Crude Oil | Type: market_hloc | Price USD/bbl: 107 (2026-09-14) | Range: 71.57–107.6 | Trend(6pt): 83.17,78.02,90.74,91.62,107.6,107
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Tuesday (2026-09-15) | |||
| Unemployment Rate | 4.90 | 5 | 22:00 |
| Average Earnings Incl. Bonus (3Mo/Yr) | 4.10 | 3.90 | 22:00 |
| Employment Change | 83,000 | - | 22:00 |
| BoE Wilkins Speech | - | - | 07:00 |
| Wednesday (2026-09-16) | |||
| Inflation Rate Year-over-Year | 2.90 | 3.10 | 22:00 |
| Core Inflation Rate Year-over-Year | 2.60 | 2.70 | 22:00 |
| Inflation Rate Month-over-Month | 0.30 | - | 22:00 |
| Thursday (2026-09-17) | |||
- UK labour releases tonight test wage pressures before 17 September decision
- July GDP beat at 0.4% lifts growth forecasts while gilt yields ease
- Markets price later BoE hikes as oil surge and sterling stay range-bound
Yesterday's Recap
No UK data prints occurred on 13 September, leaving market pricing for the Bank of England unchanged. The FTSE 100 rose 0.39% to 10,650.40 while the FTSE 250 gained 0.38% to 23,975.70. Sterling showed limited movement, with GBP/USD at 1.35 and GBP/EUR at 1.17.
UK 10-year gilt yields fell 2.95% to 5.19%. Brent crude climbed 2.28% to 106.99 on the Saudi pipeline incident, lifting UK natural gas 2.08% to 2.89. News that the economy expanded 0.4% in July reinforced expectations of steady policy at the upcoming meeting.
Inflation expectations declined after the Bank changed its survey provider, trimming near-term rate-hike odds.
The Day Ahead
Tonight’s 22:00 releases cover the unemployment rate, expected at 5.0% versus 4.9% prior, average earnings growth forecast at 3.9% and employment change. These prints arrive ahead of the 15 September BoE Wilkins speech and 16 September CPI figures, where headline inflation is seen rising to 3.1% from 2.9%. Attention centres on earnings as a signal of persistent wage inflation.
The 17 September BoE decision carries a consensus for no change at 3.75%, with markets watching for any shift in forward guidance. MPC minutes will clarify whether recent growth data alter the balance toward later tightening. Sterling crosses and gilt futures will react immediately to any surprise in the labour numbers.
Other Economic Notes
July’s 0.4% GDP outturn exceeded forecasts and coincided with AI-related investment gains that supported services output. Lower inflation expectations after the survey change reduce the urgency for near-term rate cuts. Persistent oil-price strength revives the case for at least one BoE hike later this year even if the committee holds this week.
Gilt-market participants continue to debate whether ongoing quantitative tightening should pause while 10-year yields remain elevated near 5.19%. These themes frame the data flow into the September meeting and the autumn Budget.