UK Macro Daily(Beta Mode)
Soft UK Jobs Data Eases BoE Pressure
Market Snapshot
| Asset | Level | Change |
|---|---|---|
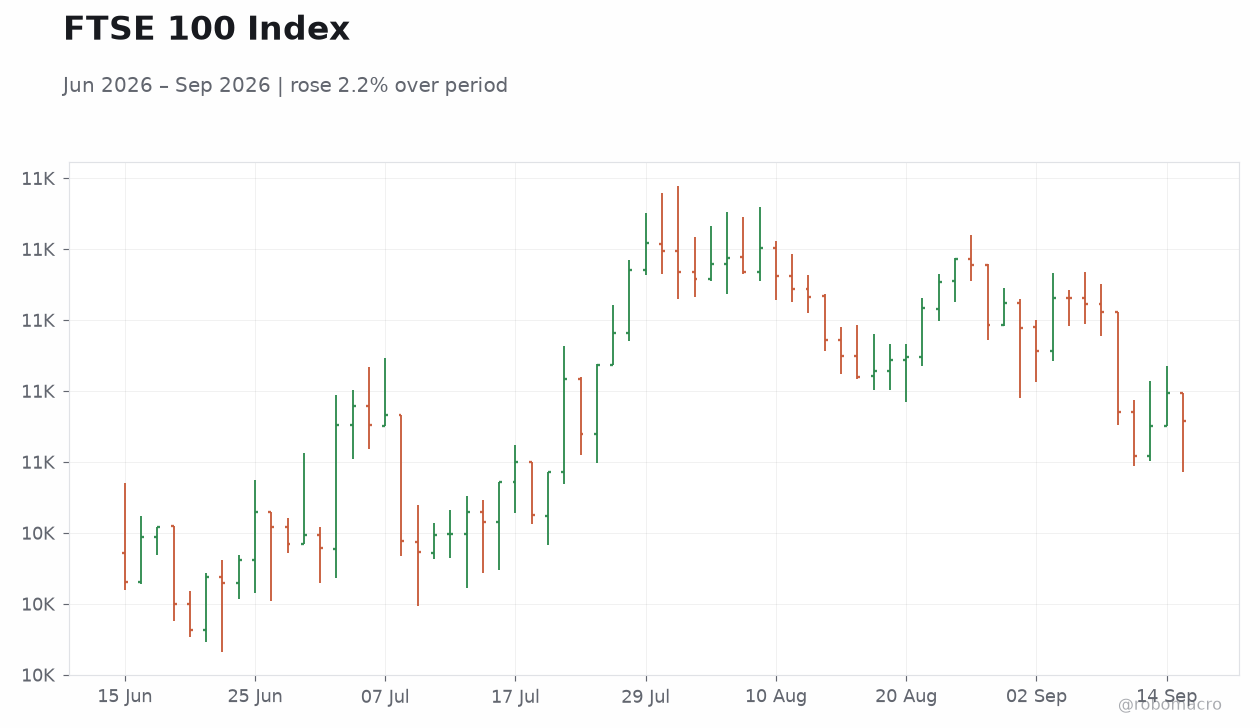
| FTSE 100 | 10,653.96 | -0.41% |
| FTSE 250 | 23,818.74 | -0.07% |
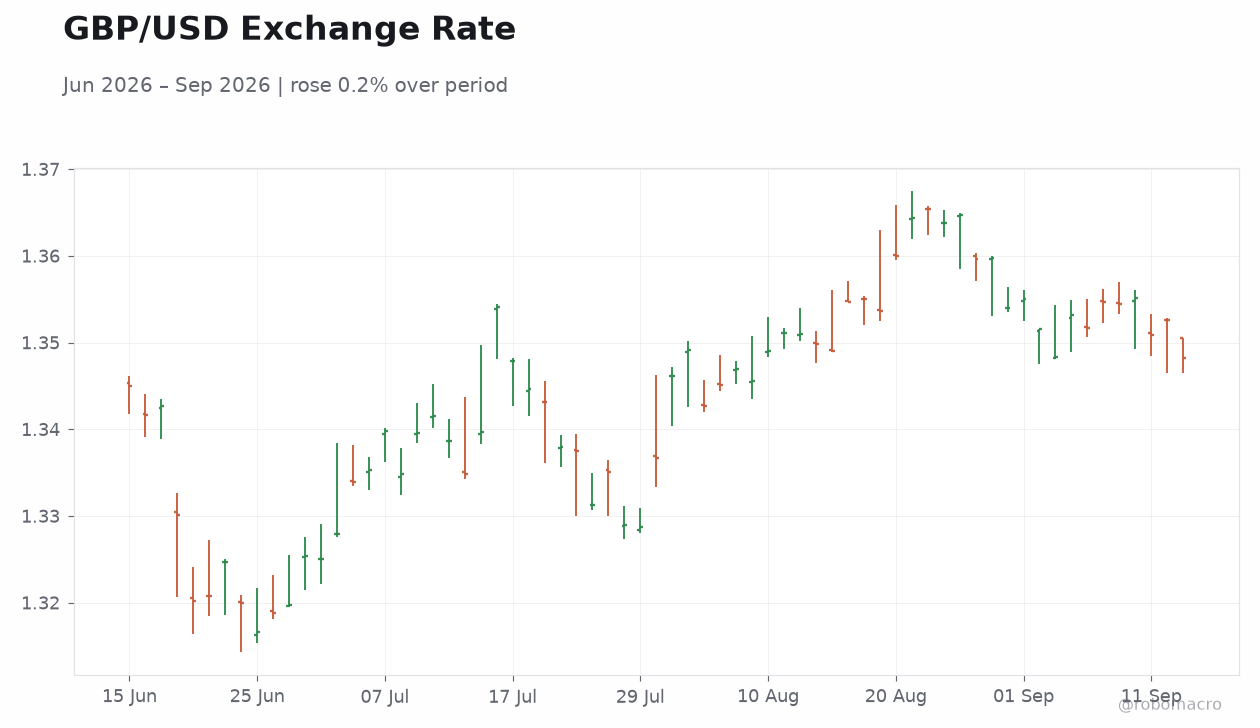
| GBP/USD | 1.35 | -0.34% |
| GBP/EUR | 1.17 | +0.06% |
| GBP/JPY | 209.07 | +0.75% |
| Brent Crude | 109.02 | +3.16% |
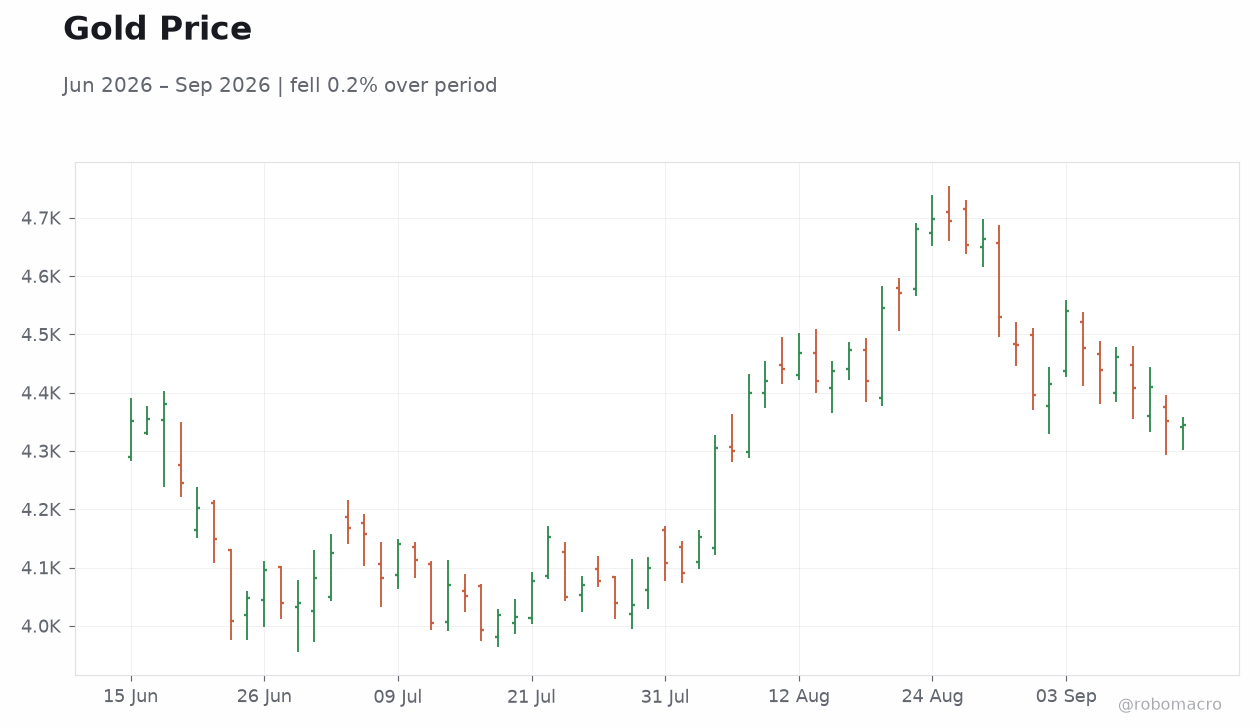
| Gold | 4,343.00 | -0.20% |
| UK Nat Gas | 2.91 | +0.52% |
| Bitcoin | 76,560.59 | -2.05% |
| UK 2Y Gilt | 4.62% | -3 bp |
| UK 10Y Gilt | 5.35% | -1 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| Unemployment Rate | 4.90 | 5 | 4.90 |
| Average Earnings Incl. Bonus (3Mo/Yr) | 4.20 | 3.90 | 3.90 |
| Employment Change | 83,000 | - | 67,000 |
| BoE Wilkins Speech | - | - | - |
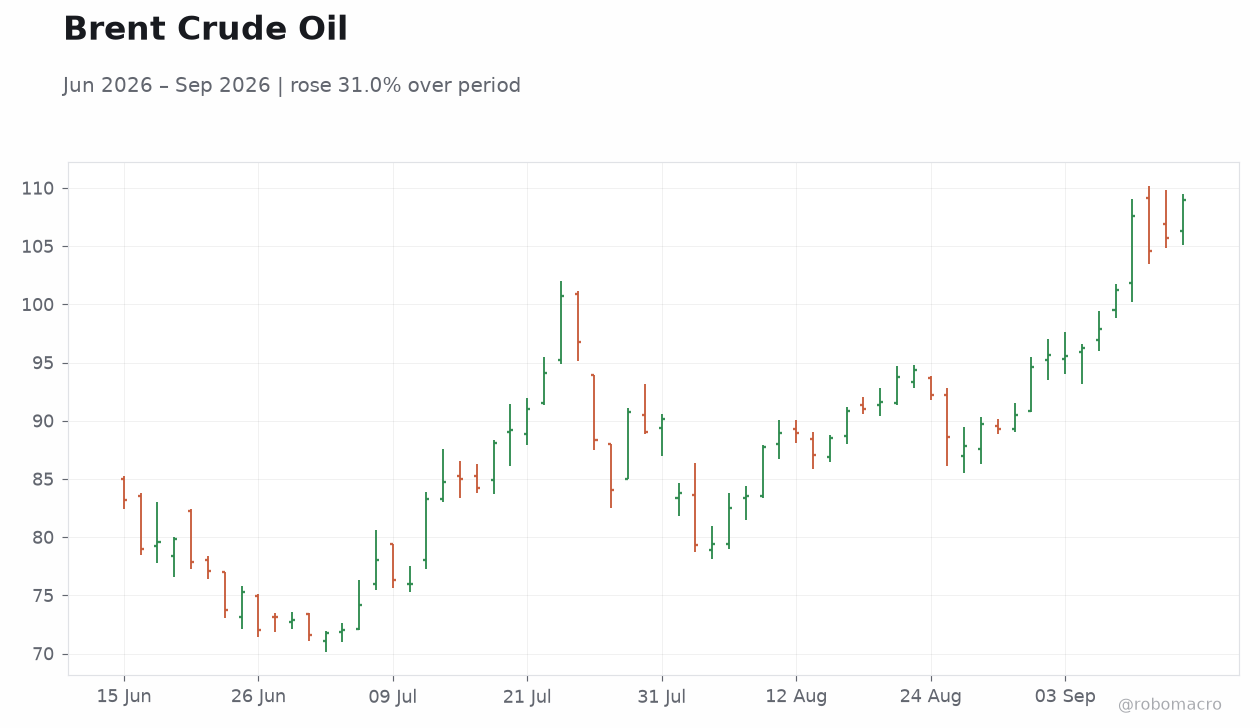 Brent Crude Oil | Type: market_hloc | Brent (USD/bbl): 109 (2026-09-15) | Range: 71.57–109 | Trend(5pt): 83.17,76.3,90.12,92.17,109
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Wednesday (2026-09-16) | |||
| Inflation Rate Year-over-Year | 2.90 | 3.10 | 22:00 |
| Core Inflation Rate Year-over-Year | 2.60 | 2.70 | 22:00 |
| Inflation Rate Month-over-Month | 0.30 | 0.50 | 22:00 |
| Thursday (2026-09-17) | |||
| BoE Interest Rate Decision | 3.75 | 3.75 | 03:00 |
| BoE MPC Vote Cut | 0 | 0 | 03:00 |
| BoE MPC Vote Hike | 3 | - | 03:00 |
| BoE MPC Vote Unchanged | 6 | - | 03:00 |
| MPC Meeting Minutes | - | - | 03:00 |
- Unemployment holds at 4.9% while earnings growth slows to 3.9%
- FTSE 100 falls 0.41% as Brent jumps 3.16% on Saudi pipeline outage
- Markets expect BoE to hold at 3.75% and slow long-term gilt sales
Yesterday's Recap
UK labour-market data released at 22:00 showed the unemployment rate unchanged at 4.9% against a 5.0% consensus. Average earnings growth including bonuses eased to 3.9% from 4.2%, matching forecasts and signalling cooling wage pressures. Employment rose by 67,000, below the prior 83,000 gain.
The softer prints reduced immediate inflation concerns ahead of the Bank of England decision. FTSE 100 declined 0.41% to 10,653.96 while the FTSE 250 slipped 0.07%. Sterling weakened, with GBP/USD falling 0.34% to 1.35.
Gilt yields eased modestly, the 2-year falling 3 bp to 4.62% and the 10-year declining 1 bp to 5.35%. Brent crude surged 3.16% to 109.02 on the Saudi East-West pipeline shutdown.
The Day Ahead
UK inflation figures due at 22:00 are expected to show headline CPI rising to 3.1% y/y from 2.9% and core CPI at 2.7% from 2.6%. Month-on-month CPI is forecast at 0.5% versus 0.3% previously. These prints will shape positioning ahead of the 17 September BoE rate decision, where markets anticipate no change at 3.75%.
Retail sales data follow on 17 September. The inflation release is likely to drive immediate moves in gilts, sterling and rate-sensitive equities. BoE Wilkins is scheduled to speak today with limited scope for new signals.
Other Economic Notes
Leaders of Wales, Scotland and Northern Ireland signed a pact seeking closer EU ties and constitutional reform, raising questions over UK internal cohesion. Mortgage rates have climbed in anticipation of the BoE meeting, adding pressure on households. The combination of steady unemployment and slower wage growth supports the case for unchanged policy while inflation remains above target.
Broader UK data flow remains light outside the inflation and retail sales prints. Markets continue to monitor gilt-market functioning after recent volatility.
Global Macro News
Brent crude rose sharply after Saudi Arabia’s East-West pipeline shutdown, lifting energy prices and feeding into UK inflation risks. Gold eased 0.20% to 4,343.00 while Bitcoin fell 2.05%. UK natural gas edged 0.52% higher.
↓ p.2