UK Macro Daily(Beta Mode)
Soft UK Jobs Data Precede BoE Meeting
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| FTSE 100 | 10,653.96 | -0.41% |
| FTSE 250 | 23,818.70 | -0.07% |
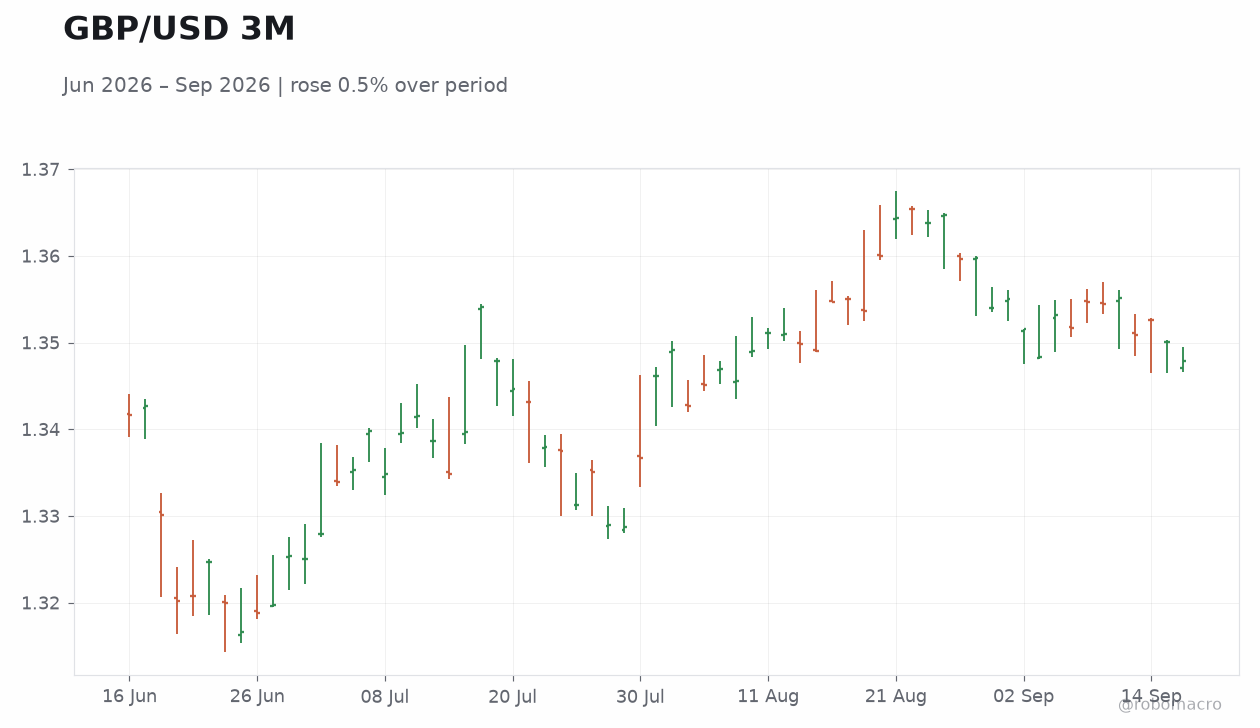
| GBP/USD | 1.35 | -0.15% |
| GBP/EUR | 1.17 | -0.18% |
| GBP/JPY | 208.90 | +0.23% |
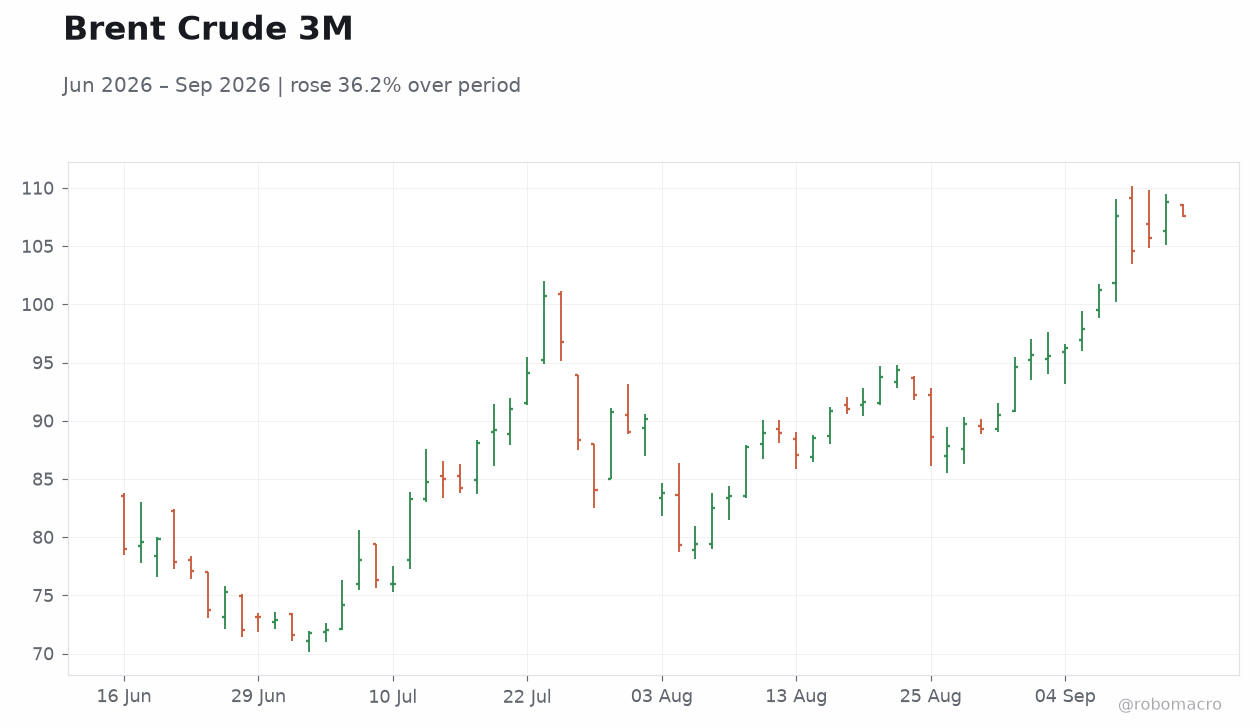
| Brent Crude | 107.59 | -1.07% |
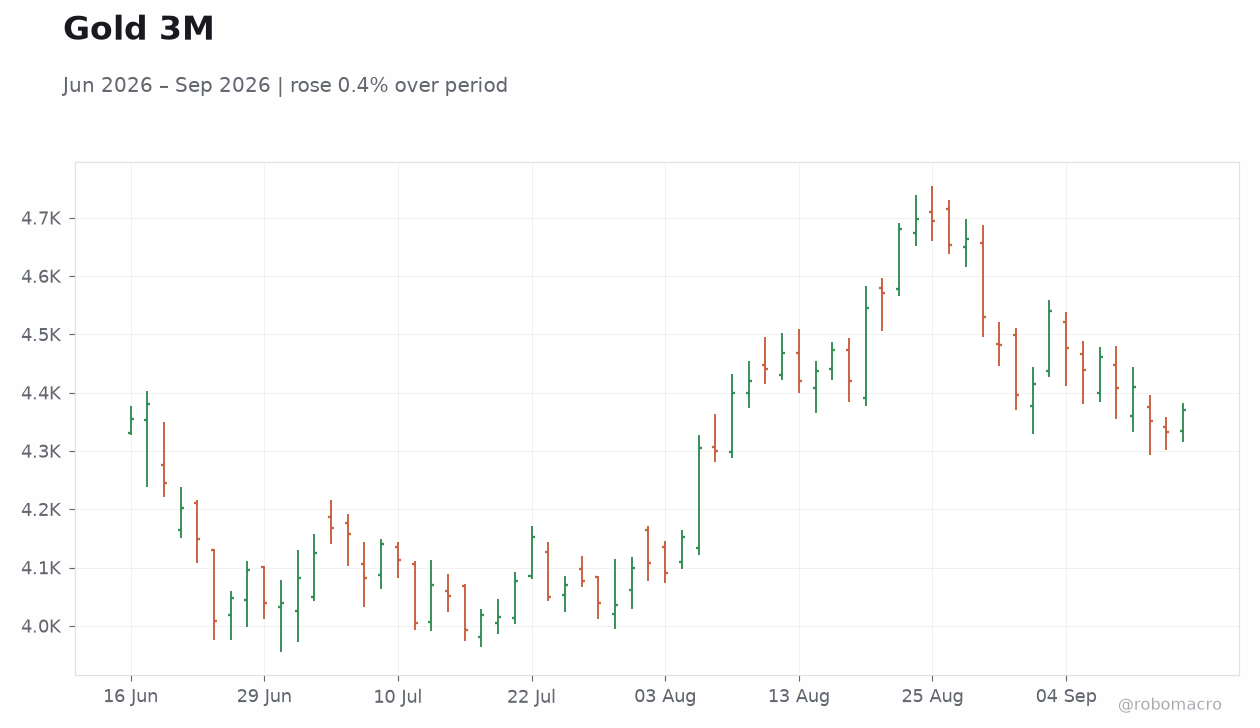
| Gold | 4,367.70 | +0.81% |
| UK Nat Gas | 2.91 | -0.17% |
| Bitcoin | 75,946.74 | -2.84% |
| UK 2Y Gilt | 4.72% | +10 bp |
| UK 10Y Gilt | 5.39% | +4 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| Unemployment Rate | 4.90 | 5 | 4.90 |
| Average Earnings Incl. Bonus (3Mo/Yr) | 4.20 | 3.90 | 3.90 |
| Employment Change | 83,000 | - | 67,000 |
| BoE Wilkins Speech | - | - | - |
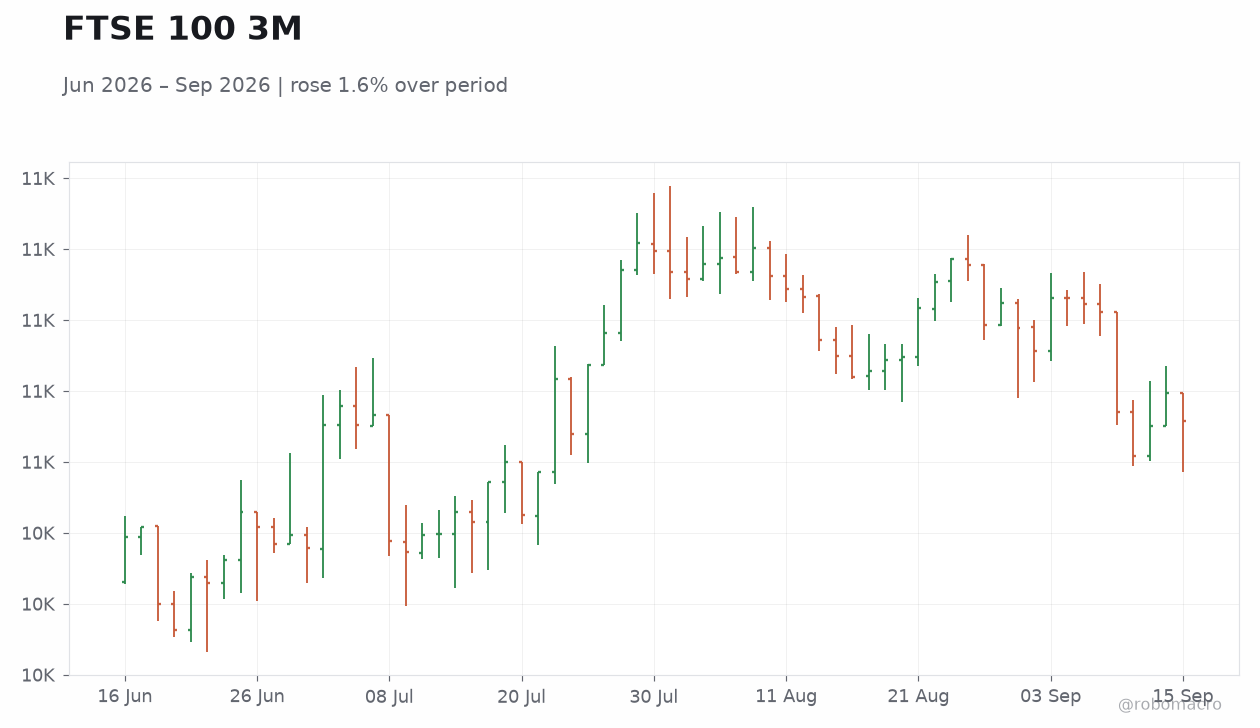 FTSE 100 3M | Type: market_hloc | FTSE 100: 1.066e+04 (2026-09-15) | Range: 1.036e+04–1.091e+04 | Trend(5pt): 1.049e+04,1.049e+04,1.09e+04,1.082e+04,1.066e+04
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Wednesday (2026-09-16) | |||
| Inflation Rate Year-over-Year | 2.90 | 3.10 | 22:00 |
| Core Inflation Rate Year-over-Year | 2.60 | 2.70 | 22:00 |
| Inflation Rate Month-over-Month | 0.30 | 0.50 | 22:00 |
| Thursday (2026-09-17) | |||
| BoE Interest Rate Decision | 3.75 | 3.75 | 03:00 |
| BoE MPC Vote Cut | 0 | 0 | 03:00 |
| BoE MPC Vote Hike | 3 | - | 03:00 |
| BoE MPC Vote Unchanged | 6 | - | 03:00 |
| MPC Meeting Minutes | - | - | 03:00 |
- Unemployment holds at 4.9% while earnings growth slows to 3.9%
- FTSE 100 falls 0.41% as 2-year gilt yields rise 10 bp
- Markets await CPI prints and 17 September BoE decision
Yesterday's Recap
UK labour data released on 14 September showed the unemployment rate steady at 4.9% against a 5.0% consensus, while average earnings including bonuses rose 3.9% year-over-year in line with forecasts. Employment change printed 67,000, below the prior 83,000. The combination of contained wage growth and a lower unemployment rate than forecast left BoE expectations largely unchanged.
FTSE 100 declined 0.41% to 10,653.96 and FTSE 250 eased 0.07%. The 2-year gilt yield climbed 10 bp to 4.72% and the 10-year yield added 4 bp to 5.39%. Sterling was mixed, with GBP/USD falling 0.15% to 1.35 and GBP/EUR declining 0.18% to 1.17.
BoE Deputy Governor Wilkins spoke without shifting policy signals. Recent labour-market weakness, including vacancies at four-year lows, reinforces the case for steady policy amid subdued demand.
The Day Ahead
UK inflation data due at 22:00 on 15 September will show headline CPI year-over-year expected at 3.1% versus the prior 2.9%, with core CPI forecast at 2.7%. Month-over-month inflation is projected at 0.5%. These prints feed directly into the 17 September Bank of England meeting, where the policy rate is expected to remain at 3.73%.
MPC votes and minutes will accompany the decision. Retail sales for August follow on 17 September evening, with month-over-month consensus at -0.2%. Markets will monitor any shift in forward guidance on quantitative tightening.
Reports indicate the Bank of England plans to halt sales of long-dated gilts, potentially easing pressure on the 10-year sector.
Other Economic Notes
Shadow MPC members have urged rates to stay on hold despite upside inflation risks. Broader fiscal-monetary overlap from quantitative tightening continues to draw scrutiny over accountability for gilt-market outcomes. These developments keep focus on the September inflation release as the key near-term driver for gilt yields and sterling.
UK employers cut jobs as the labour market remained weak over summer, with the latest snapshot on employment arriving ahead of the Bank of England meeting this week.