UK Macro Daily(Beta Mode)
BoE Set to Hold After CPI Rise
Market Snapshot
| Asset | Level | Change |
|---|---|---|
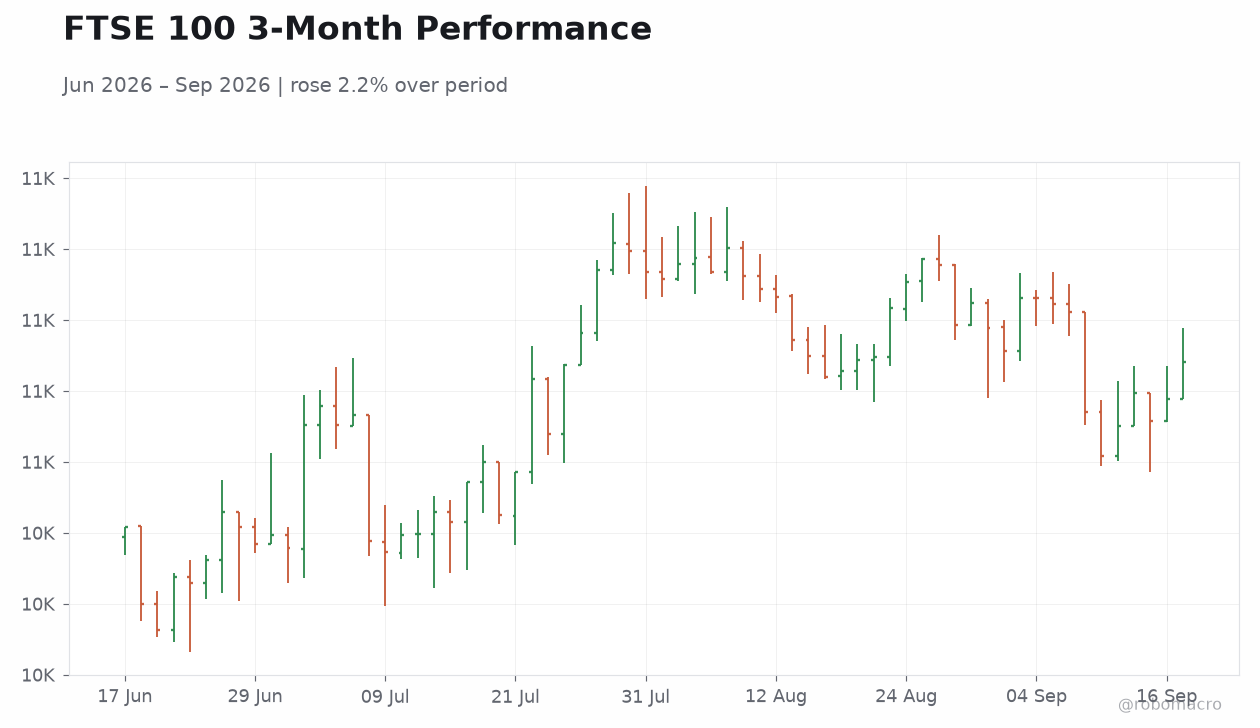
| FTSE 100 | 10,694.73 | +0.34% |
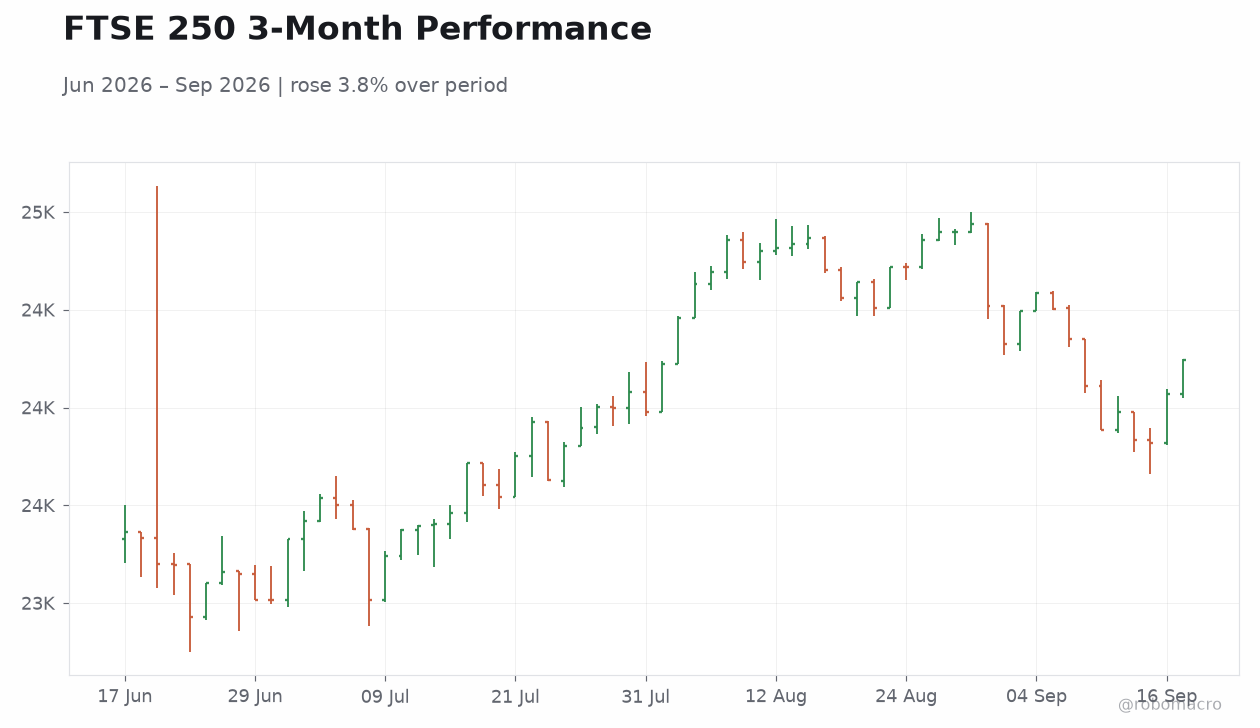
| FTSE 250 | 24,243.98 | +0.72% |
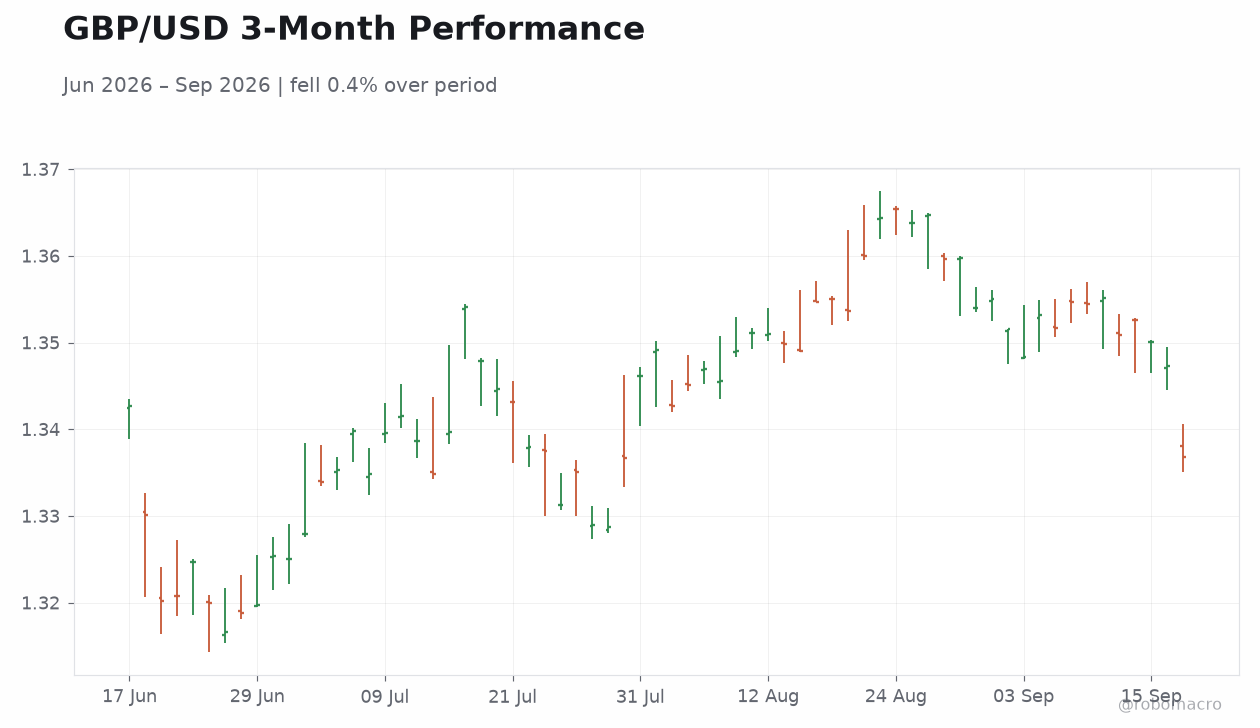
| GBP/USD | 1.34 | -0.79% |
| GBP/EUR | 1.16 | -0.23% |
| GBP/JPY | 208.27 | -0.43% |
| Brent Crude | 99.24 | -6.23% |
| Gold | 4,368.00 | -0.44% |
| UK Nat Gas | 2.89 | -0.10% |
| Bitcoin | 76,133.51 | -0.02% |
| UK 2Y Gilt | 4.72% | +10 bp |
| UK 10Y Gilt | 5.39% | +4 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| Inflation Rate Year-over-Year | 2.90 | 3.10 | 3.10 |
| Core Inflation Rate Year-over-Year | 2.60 | 2.60 | 2.60 |
| Inflation Rate Month-over-Month | 0.30 | 0.50 | 0.50 |
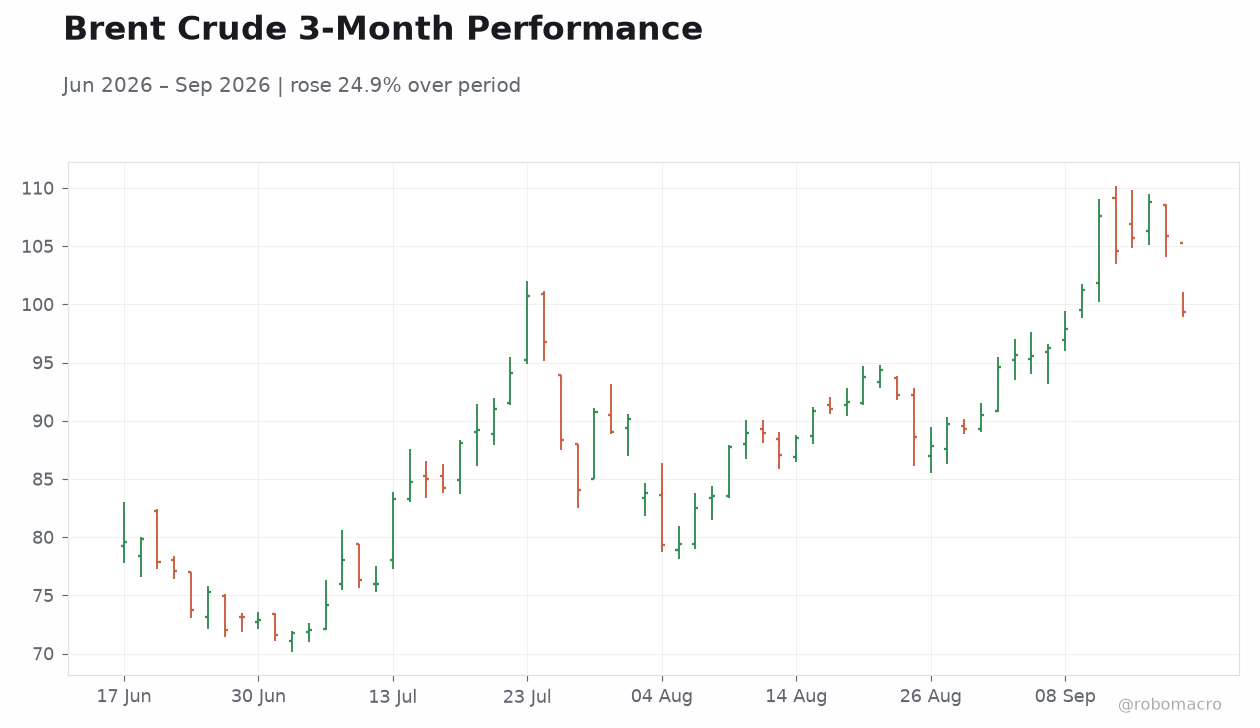 Brent Crude 3-Month Performance | Type: market_hloc | Price USD: 99.38 (2026-09-17) | Range: 71.57–108.8 | Trend(5pt): 79.55,83.3,79.36,87.84,99.38
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| BoE Interest Rate Decision | 3.75 | 3.75 | 07:00 |
| BoE MPC Vote Cut | 0 | 0 | 07:00 |
| BoE MPC Vote Hike | 3 | - | 07:00 |
| BoE MPC Vote Unchanged | 6 | - | 07:00 |
| MPC Meeting Minutes | - | - | 07:00 |
- UK headline CPI rose to 3.1% y/y in August, matching consensus and lifting the five-month high.
- BoE expected to keep Bank Rate unchanged at 3.75% with minutes due at 07:00 ET.
- FTSE 100 rose 0.34% while 2-year gilt yields climbed 10 bp to 4.72%.
Yesterday's Recap
UK inflation data for August printed at 02:00 ET, with headline CPI advancing 3.1% y/y against a 2.9% prior and 3.1% consensus. Core CPI held steady at 2.6% y/y while the monthly rate reached 0.5%, aligning with forecasts. Equity markets responded positively, lifting the FTSE 100 to 10,694.73 and the FTSE 250 to 24,243.98.
Sterling weakened, with GBP/USD falling to 1.34, GBP/EUR to 1.16 and GBP/JPY to 208.27. Brent crude dropped sharply to 99.24 amid global supply concerns. Gilt yields rose across the curve, taking the 2-year to 4.72% and the 10-year to 5.39%.
No MPC speeches occurred to alter positioning ahead of today’s decision.
The Day Ahead
The Bank of England will announce its interest-rate decision at 07:00 ET, with the MPC vote breakdown and meeting minutes also released. Markets price no change to the 3.75% Bank Rate. Attention will centre on any updated language regarding inflation persistence and the balance of risks.
Retail sales figures are scheduled for tomorrow rather than today. No other high-impact UK releases appear on the calendar. The outcome and accompanying guidance will shape sterling, gilt and equity moves through the session.
Other Economic Notes
Chancellor appointments to the Bank of England Court of Directors introduce new non-executive oversight without immediate policy implications. UK unemployment stands at 4.9%, providing a stable labour backdrop against the recent CPI uptick. Mortgage rates have reached their highest level since 2023, reflecting the cumulative effect of prior tightening.
Broader commentary continues to highlight the tension between sticky inflation and growth concerns for the MPC.
Global Macro News
Brent crude’s 6.23% decline to 99.24 signals easing energy-price pressures that could feed into UK inflation later this year. Saudi Arabia’s efforts to reroute oil shipments around the Strait of Hormuz underscore ongoing Middle East supply risks that remain relevant for UK energy costs. ↓ p.2