UK Macro Daily(Beta Mode)
BoE Holds at 3.73% as CPI Climbs to 3.1%
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| FTSE 100 | 10,816.49 | +1.20% |
| FTSE 250 | 24,352.10 | +1.17% |
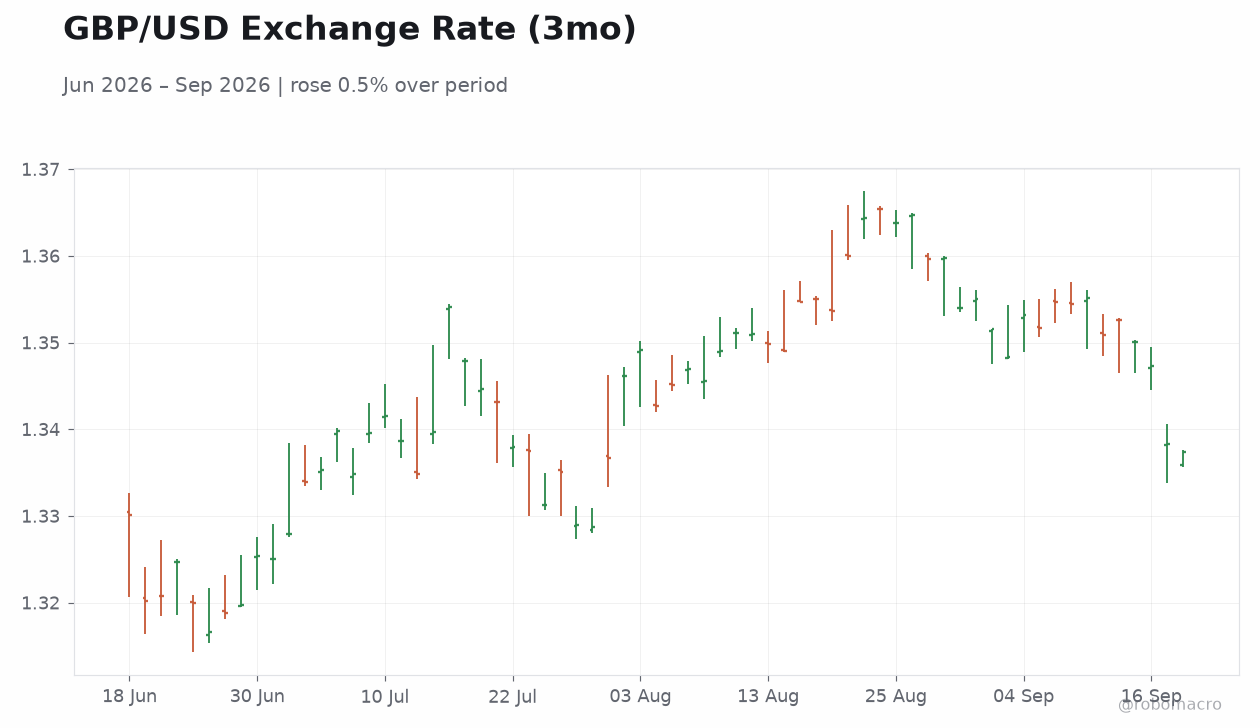
| GBP/USD | 1.34 | -0.08% |
| GBP/EUR | 1.16 | -0.23% |
| GBP/JPY | 210.07 | +0.61% |
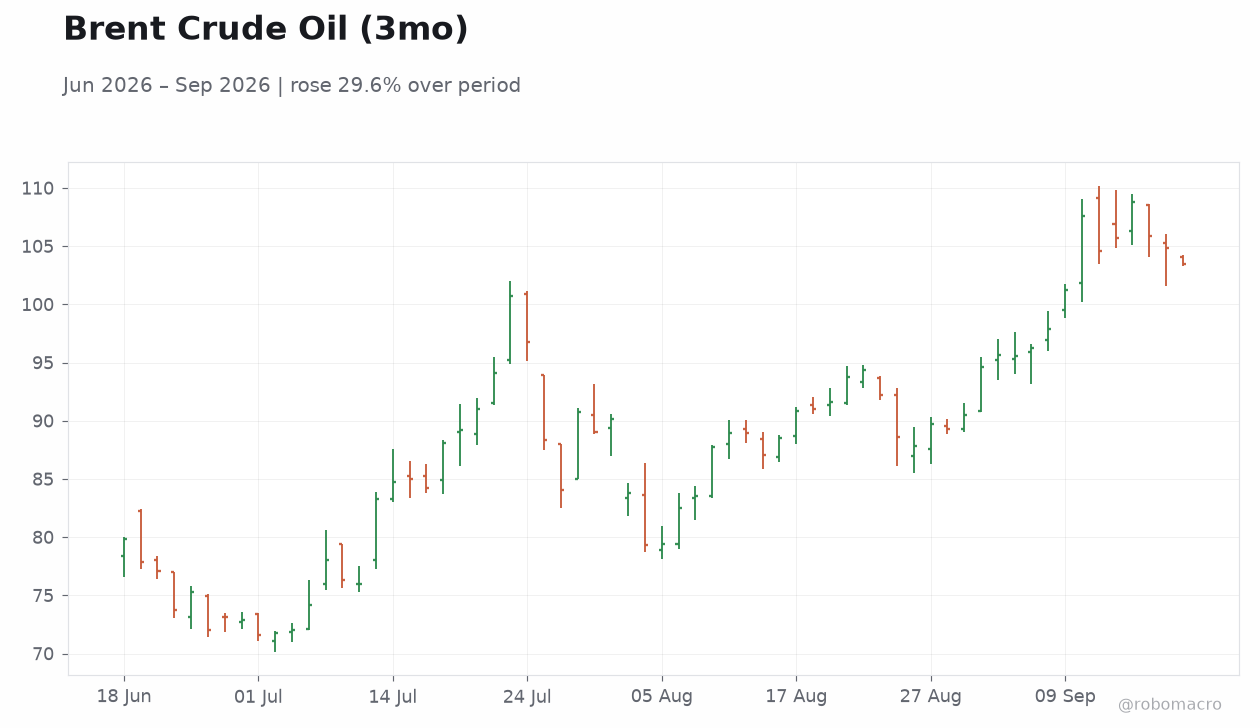
| Brent Crude | 103.56 | -1.20% |
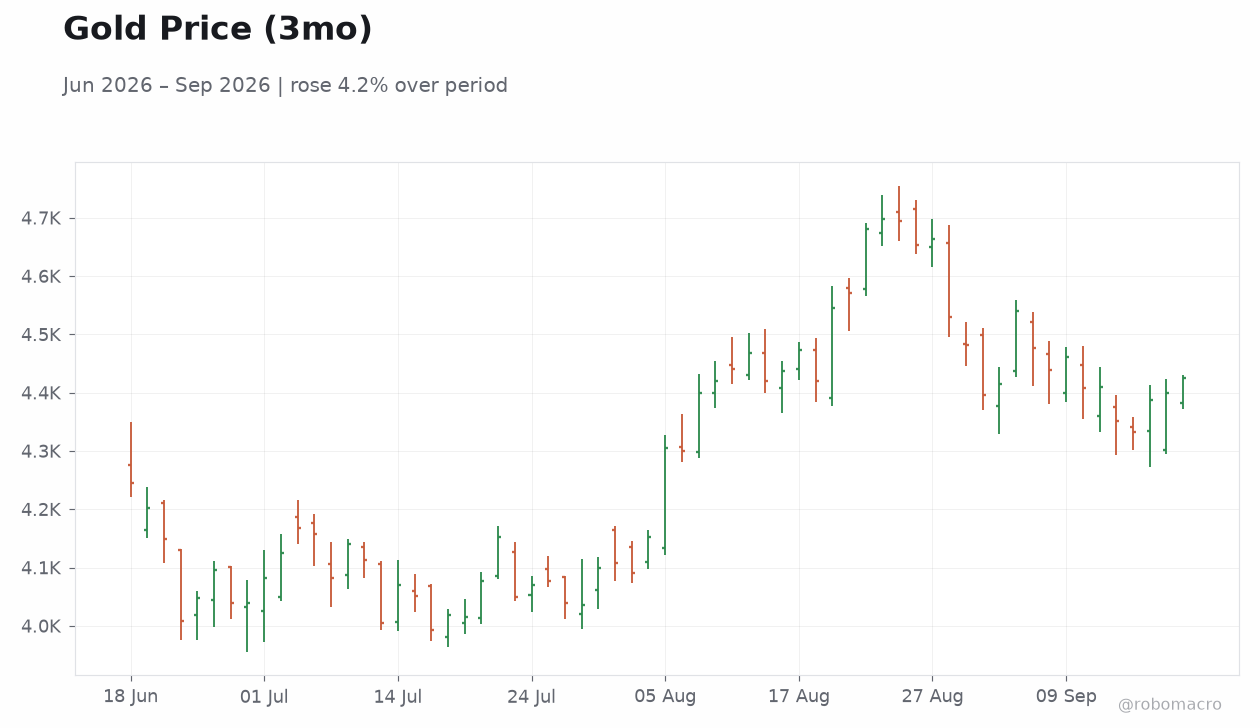
| Gold | 4,423.80 | +0.55% |
| UK Nat Gas | 2.86 | -1.34% |
| Bitcoin | 77,485.89 | +1.75% |
| UK 2Y Gilt | - | - |
| UK 10Y Gilt | 5.29% | -10 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| Unemployment Rate | 4.90 | 5 | 4.90 |
| Average Earnings Incl. Bonus (3Mo/Yr) | 4.20 | 3.90 | 3.90 |
| Employment Change | 83,000 | - | 67,000 |
| BoE Wilkins Speech | - | - | - |
| Inflation Rate Year-over-Year | 2.90 | 3.10 | 3.10 |
| Core Inflation Rate Year-over-Year | 2.60 | 2.60 | 2.60 |
| Inflation Rate Month-over-Month | 0.30 | 0.50 | 0.50 |
| BoE Interest Rate Decision | 3.75 | 3.75 | - |
| BoE MPC Vote Cut | 0 | 0 | - |
| BoE MPC Vote Hike | 3 | - | - |
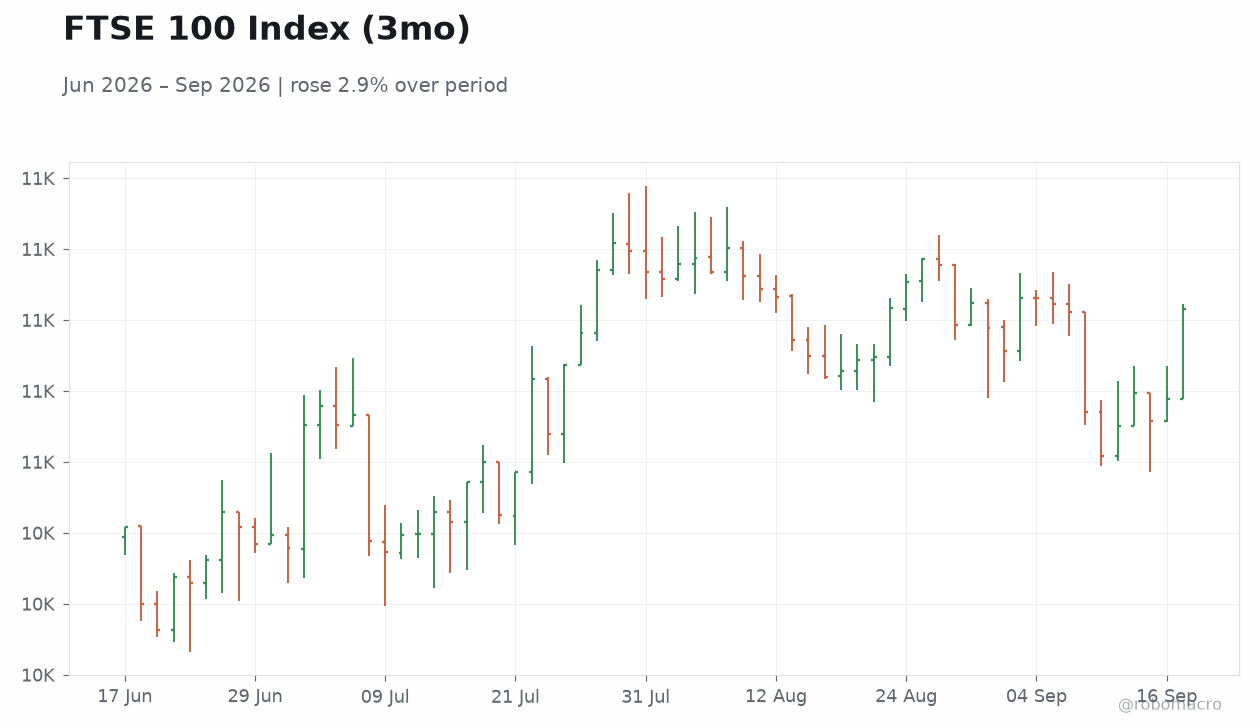 FTSE 100 Index (3mo) | Type: market_hloc | FTSE 100: 1.082e+04 (2026-09-17) | Range: 1.036e+04–1.091e+04 | Trend(6pt): 1.051e+04,1.047e+04,1.087e+04,1.085e+04,1.069e+04,1.082e+04
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- BoE keeps Bank Rate unchanged at 3.75% amid 6-3 MPC split
- UK headline CPI rises to 3.1% y/y while unemployment holds at 4.9%
- FTSE 100 advances 1.2% and 10-year gilt yield falls 10 bp to 5.29%
Yesterday's Recap
UK labour data released on 14 September showed the unemployment rate steady at 4.9% while average earnings growth slowed to 3.9% and employment rose by 67,000. Inflation figures published the following day matched expectations, with headline CPI climbing 3.1% year-over-year, core CPI steady at 2.6% and the monthly rate at 0.5%. The Bank of England left the policy rate at 3.75% on 17 September, with the MPC voting 6-3 to hold and publishing accompanying minutes.
Retail-sales prints scheduled for the same day were not released. Equity markets responded positively, with the FTSE 100 closing at 10,816.49 and the FTSE 250 at 24,352.10. Sterling posted modest declines against the dollar and euro while the 10-year gilt yield eased 10 bp to 5.29%.
The Day Ahead
No high-impact UK data releases or Bank of England speeches are scheduled for 18 September. Markets will therefore focus on follow-through from the MPC minutes and any commentary from officials on the inflation outlook. Attention may also turn to retail-sales trends after the missed print and to gilt-market reaction to the BoE’s updated bond-sales guidance.
Sterling crosses and FTSE futures are expected to trade in narrow ranges absent fresh catalysts.
Other Economic Notes
UK and Canadian officials agreed to deepen cooperation on trade, defence and artificial intelligence, potentially supporting longer-term growth prospects. Labour-market softening alongside on-target inflation readings has reinforced expectations that policy easing will remain gradual. Gilt yields declined after the BoE outlined plans to wind down the asset-purchase scheme, easing near-term borrowing costs for the government.
Global Macro News
Brent crude fell 1.2% to $103.56 as Saudi Arabia explored alternative export routes amid Red Sea tensions. Gold rose 0.55% to $4,423.80, reflecting safe-haven demand linked to geopolitical risks. UK natural gas prices dropped 1.34% while Bitcoin gained 1.75%.
Broader equity sentiment improved on the absence of immediate escalation in Middle East conflict. Sterling’s modest losses reflected the BoE’s measured tone relative to other major central banks.