UK Macro Daily(Beta Mode)
BoE Holds as UK Inflation Hits 3.1%
Market Snapshot
| Asset | Level | Change |
|---|---|---|
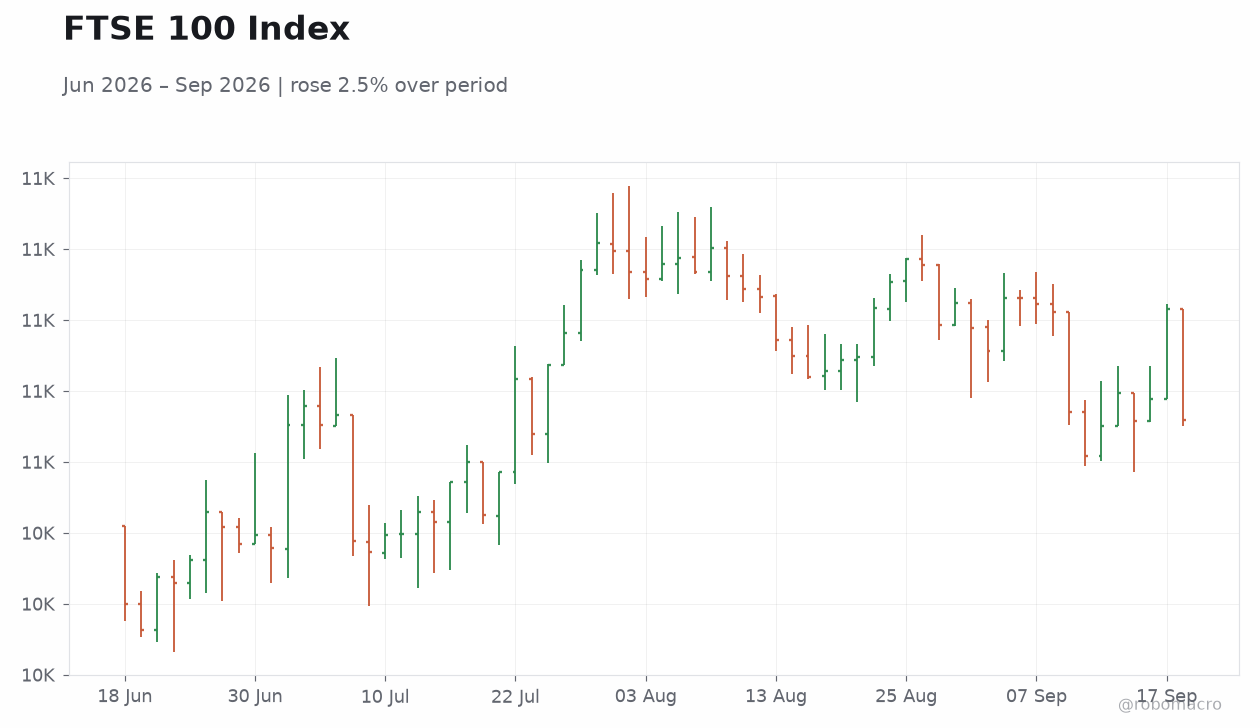
| FTSE 100 | 10,659.10 | -1.45% |
| FTSE 250 | 24,205.40 | -0.60% |
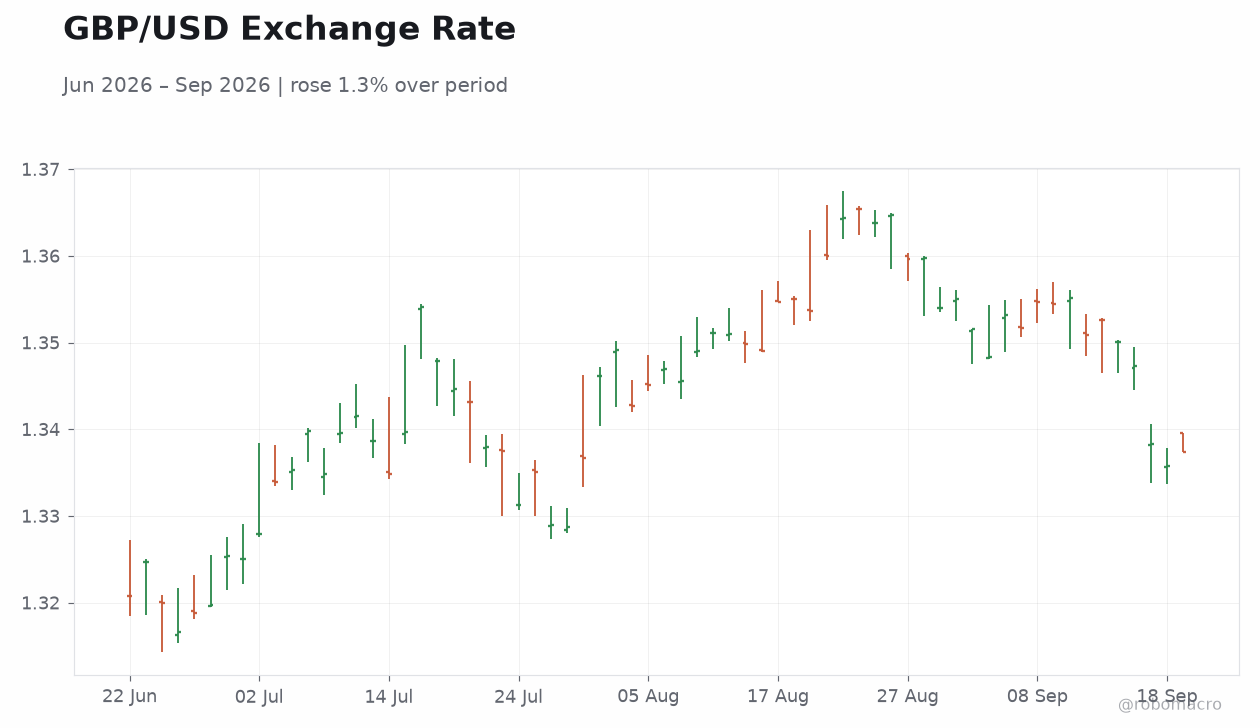
| GBP/USD | 1.34 | +0.12% |
| GBP/EUR | 1.17 | +0.13% |
| GBP/JPY | 210.02 | +0.71% |
| Brent Crude | 98.15 | -5.51% |
| Gold | 4,389.20 | -0.81% |
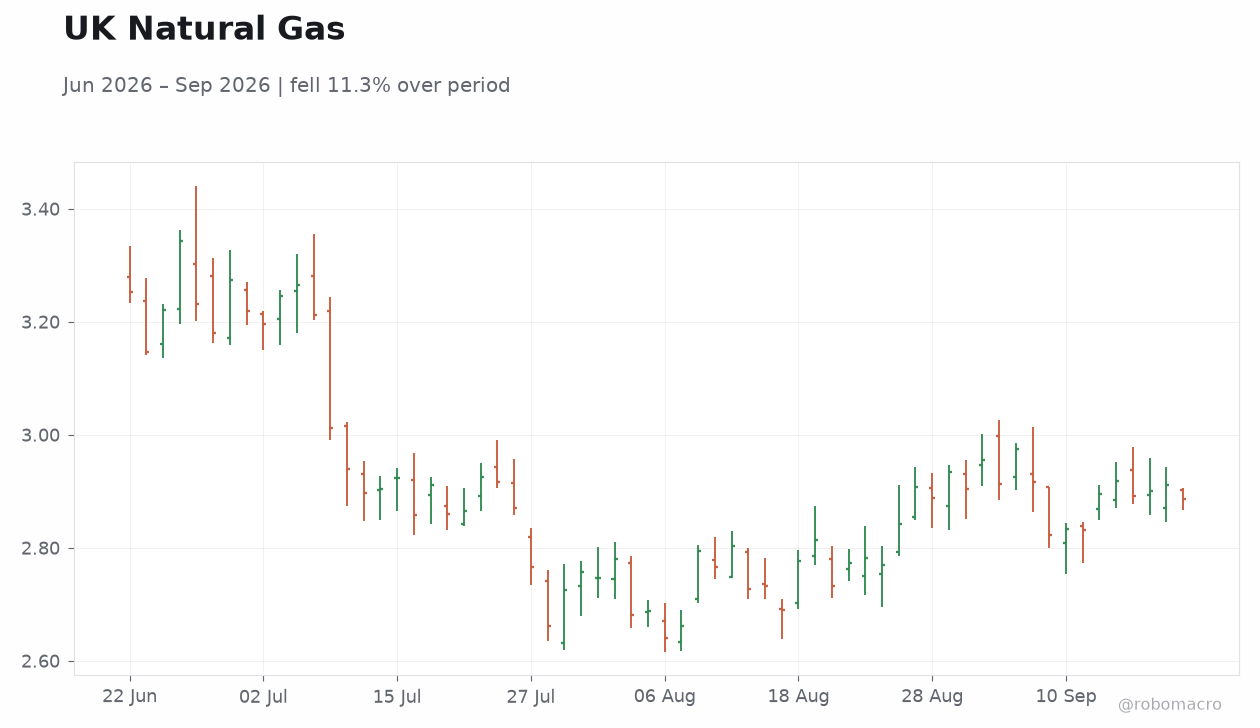
| UK Nat Gas | 2.88 | -0.96% |
| Bitcoin | 81,603.94 | +0.46% |
| UK 2Y Gilt | 4.54% | -1 bp |
| UK 10Y Gilt | 5.21% | -8 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
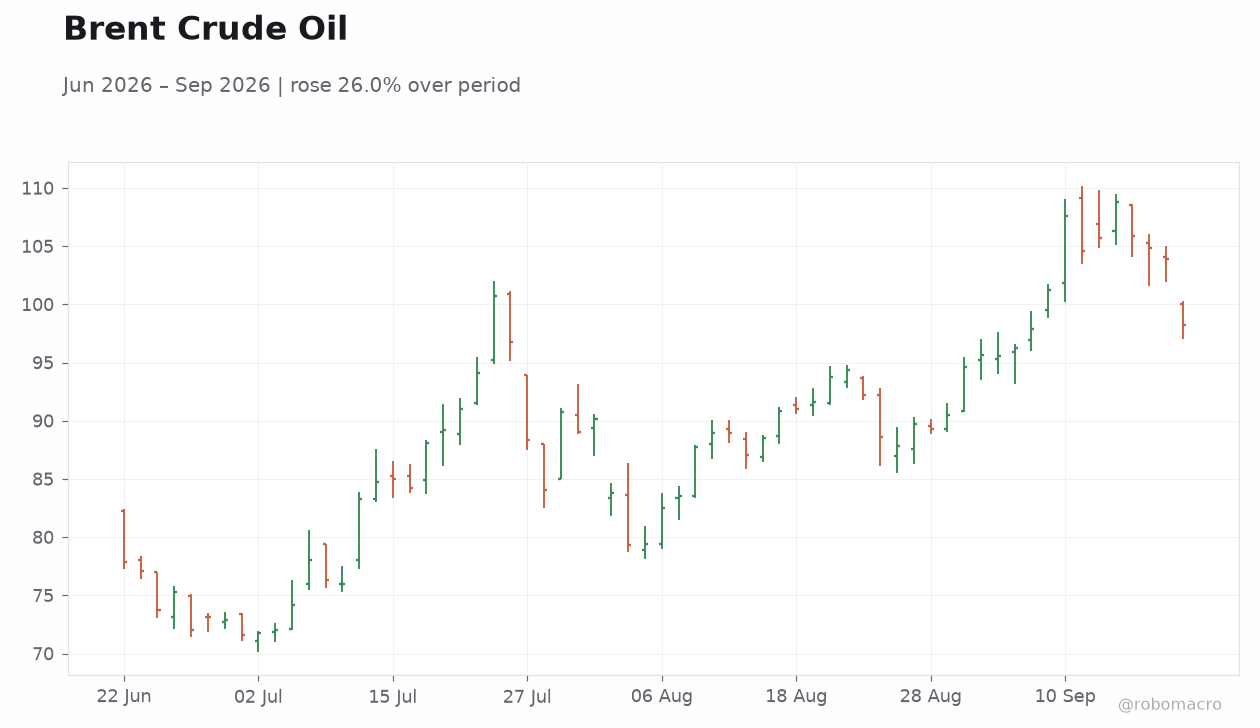 Brent Crude Oil | Type: market_hloc | Brent $/bbl: 98.19 (2026-09-21) | Range: 71.57–108.8 | Trend(5pt): 77.9,84.95,82.49,89.31,98.19
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Tuesday (2026-09-22) | |||
| CBI Industrial Trends Orders Level | -25 | -35 | 02:00 |
| Wednesday (2026-09-23) | |||
| S&P Global Manufacturing PMI Flash | 51.70 | 52.70 | 00:30 |
| S&P Global Services PMI Flash | 52.50 | 52.10 | 00:30 |
| Thursday (2026-09-24) | |||
| BoE Bean Speech | - | - | 00:10 |
| Speech by BoE's Dhingra | - | - | 01:30 |
| CBI Distributive Trades Level | -48 | -50 | 02:00 |
| Speech by BoE's Breeden | - | - | 05:30 |
- UK CPI rose to 3.1% while BoE held Bank Rate at 3.73%, citing Middle East energy threats.
- FTSE 100 fell 1.45% to 10,659.10 and 10-year gilt yields eased 8 bp to 5.21% on risk-off flows.
- Sterling firmed modestly against major crosses despite softer equity and oil markets.
Yesterday's Recap
No UK data releases occurred on 20 September, leaving markets to focus on global risk sentiment and prior inflation prints. FTSE 100 declined 1.45% to 10,659.10 while the FTSE 250 slipped 0.60% to 24,205.40. Brent crude dropped 5.51% to 98.15 amid easing supply concerns, and UK natural gas fell 0.96% to 2.88.
The 10-year gilt yield declined 8 bp to 5.21% and the 2-year yield fell 1 bp to 4.54%, reflecting lower growth expectations. GBP/USD rose 0.12% to 1.34 and GBP/JPY gained 0.71% to 210.02. Unemployment stood at 4.9% with no fresh labour-market data to alter the picture.
Overall moves aligned with broader equity weakness rather than domestic policy shifts.
The Day Ahead
The CBI Industrial Trends Orders Level releases at 02:00 on 22 September with consensus at -35 versus the prior -25, offering an early read on manufacturing sentiment. Attention then shifts to 23 September when S&P Global Manufacturing and Services PMI flashes are due at 00:30, expected at 52.7 and 52.1 respectively. Four Bank of England speakers appear on 24 September, including Catherine Bremner, Swati Dhingra and Sarah Breeden, likely to reinforce the data-dependent stance.
The CBI Distributive Trades survey and GfK Consumer Confidence print round out the domestic calendar. Markets will watch for any deviation that could alter rate-hike probabilities priced for later meetings. Sterling and gilt curves are expected to react modestly to the PMI outcomes given their high-impact status.
Other Economic Notes
UK inflation at 3.1% has kept the BoE on hold while energy-price warnings from Middle East tensions add upside risks to the near-term path. Retail-sales strength in recent months has reinforced bets on possible later tightening, yet the committee continues to emphasise a gradual approach. Gilt yields have compressed across the curve even as the policy rate remains 3.73%, signalling investor caution on growth.
Broader fiscal concerns, including high taxes and immigration cited by some business leaders, weigh on domestic confidence indicators. The combination leaves markets focused on incoming PMI and survey data for clearer signals on consumer and business resilience.