UK Macro Daily(Beta Mode)
FTSE Climbs as Gilt Yields Jump
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| FTSE 100 | 10,739.00 | +0.75% |
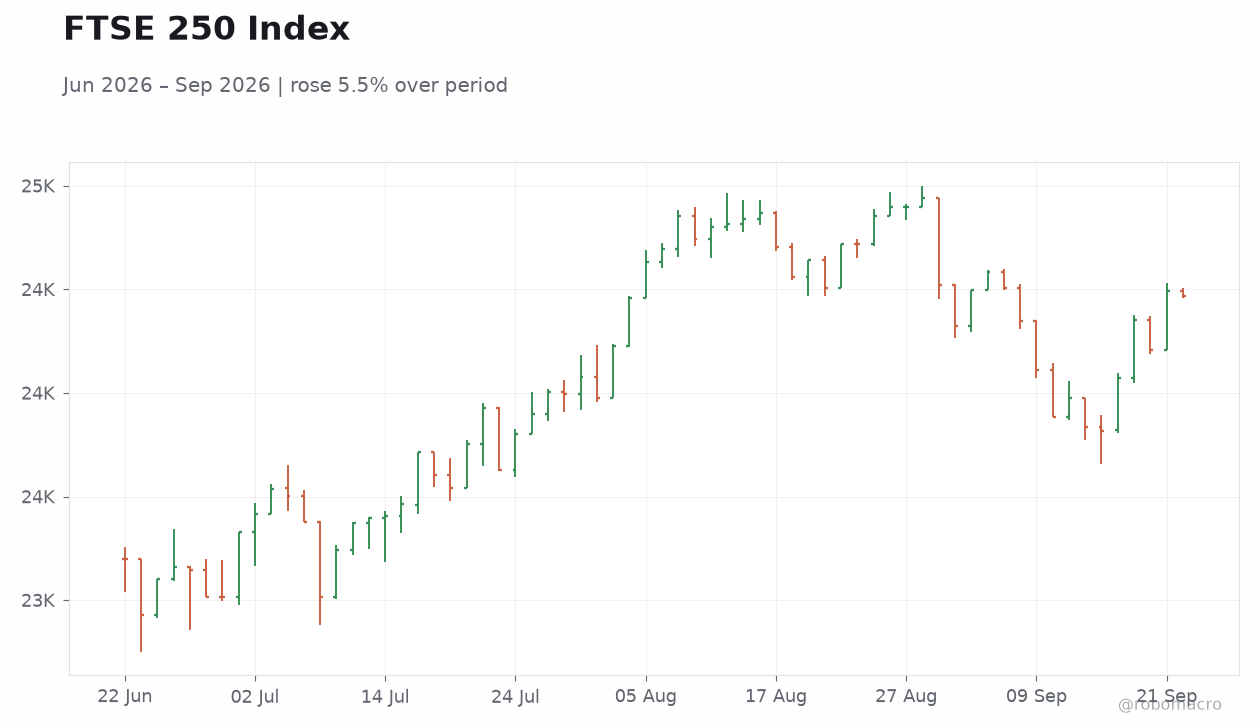
| FTSE 250 | 24,491.40 | +1.18% |
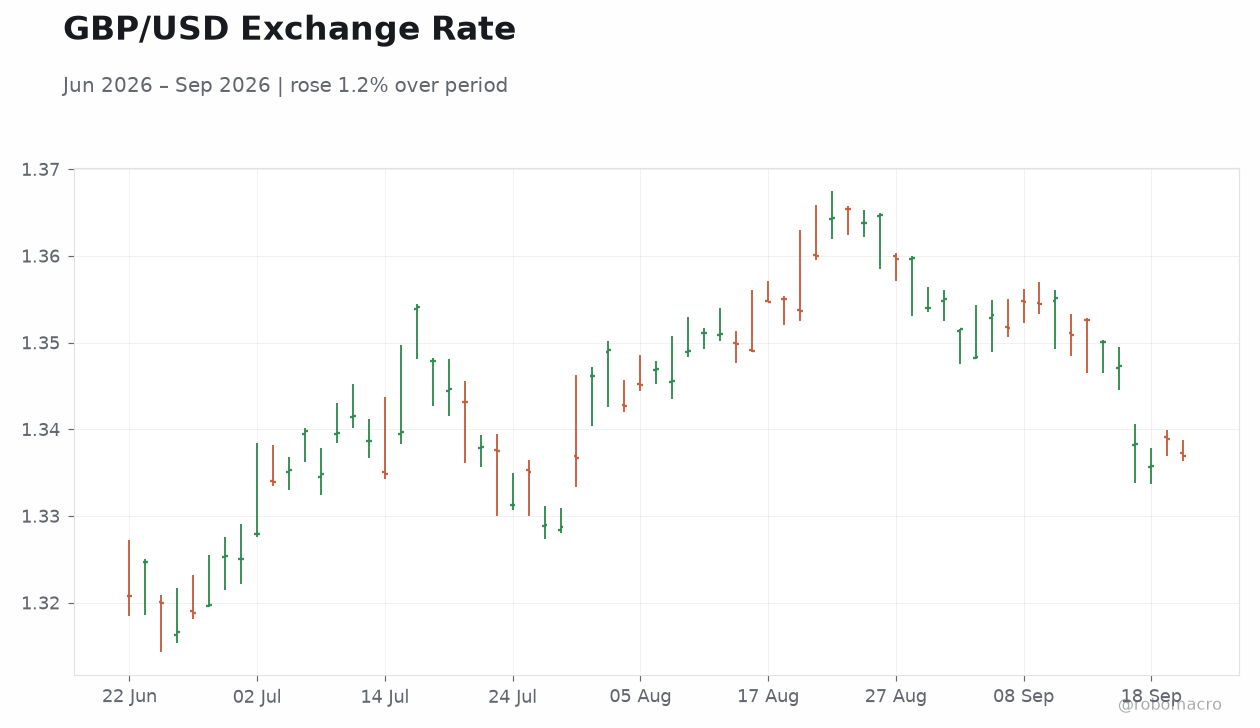
| GBP/USD | 1.34 | -0.16% |
| GBP/EUR | 1.17 | -0.03% |
| GBP/JPY | 210.27 | +0.83% |
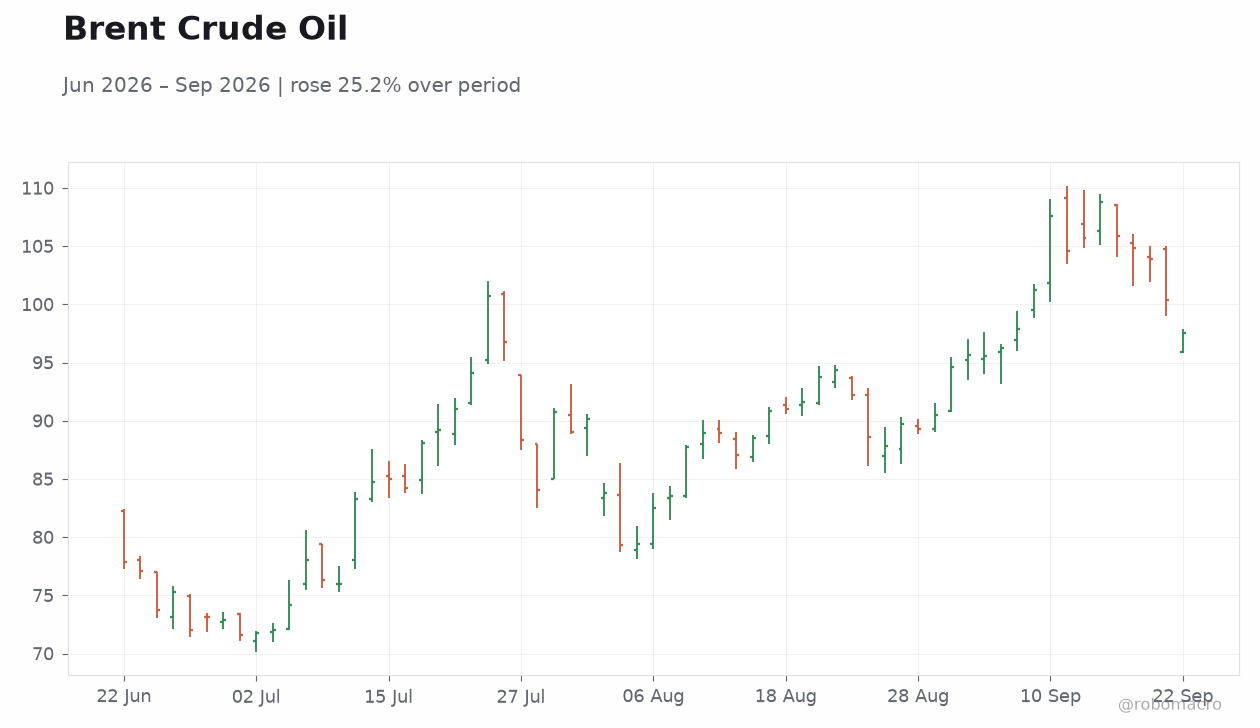
| Brent Crude | 97.76 | -2.57% |
| Gold | 4,356.20 | -0.63% |
| UK Nat Gas | 2.84 | +0.18% |
| Bitcoin | 85,430.51 | -1.35% |
| UK 2Y Gilt | 4.66% | +12 bp |
| UK 10Y Gilt | 5.29% | +8 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
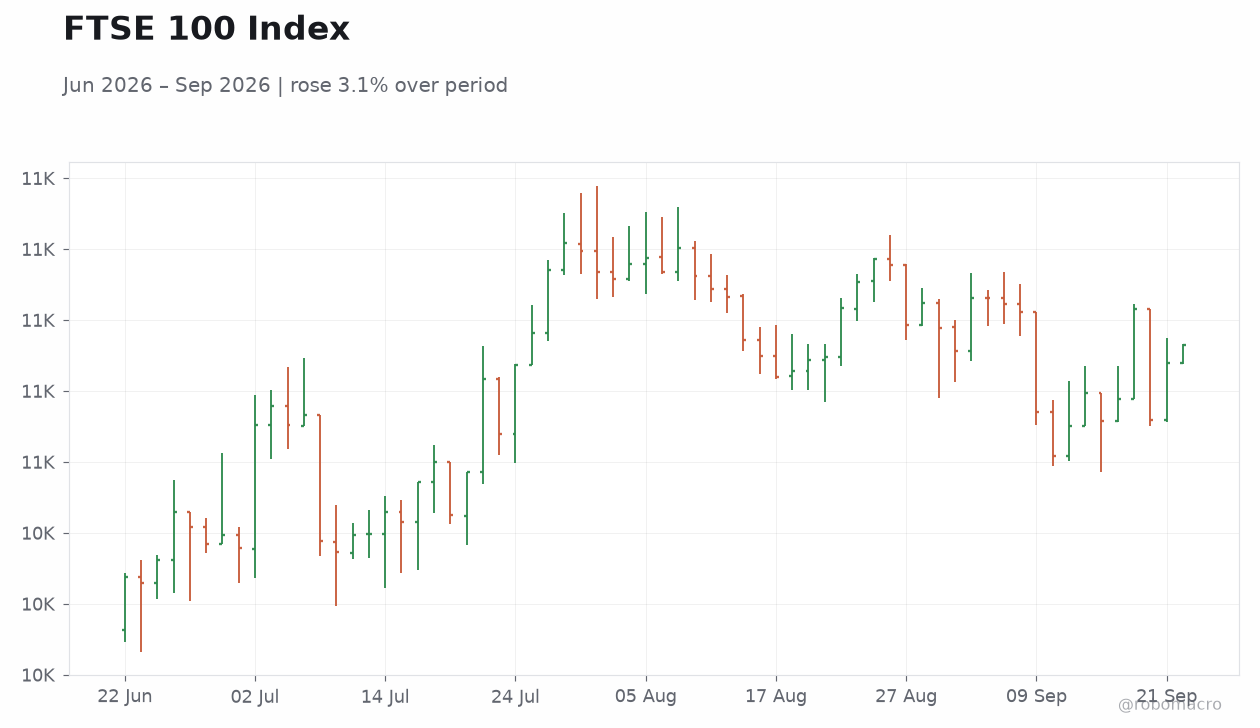 FTSE 100 Index | Type: market_hloc | FTSE 100: 1.076e+04 (2026-09-22) | Range: 1.043e+04–1.091e+04 | Trend(6pt): 1.044e+04,1.053e+04,1.089e+04,1.079e+04,1.074e+04,1.076e+04
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| CBI Industrial Trends Orders Level | -25 | -34 | 02:00 |
| Wednesday (2026-09-23) | |||
| S&P Global Manufacturing PMI Flash | 51.70 | 51.40 | 00:30 |
| S&P Global Services PMI Flash | 52.50 | 52 | 00:30 |
| Thursday (2026-09-24) | |||
| BoE Bean Speech | - | - | 00:10 |
| Speech by BoE's Dhingra | - | - | 01:30 |
| CBI Distributive Trades Level | -48 | -50 | 02:00 |
| Speech by BoE's Breeden | - | - | 05:30 |
| GfK Consumer Confidence | -14 | -16 | 15:01 |
- FTSE 100 rises 0.75% to 10,739 while 2-year gilt yield climbs 12 bp to 4.66%.
- CBI Industrial Trends Orders due today; S&P Global PMI flashes follow tomorrow.
- Bank Rate holds at 3.73% with CPI at 3.10% and unemployment at 4.90%.
Yesterday's Recap
UK equity markets advanced on 21 September with the FTSE 100 closing at 10,739.00, up 0.75%, and the FTSE 250 gaining 1.18% to 24,491.40. Sterling traded mixed against major currencies, with GBP/USD slipping 0.16% to 1.34 and GBP/JPY rising 0.83% to 210.27. Gilt yields increased sharply, the 2-year reaching 4.66% after a 12 bp rise and the 10-year climbing 8 bp to 5.29%.
Brent crude fell 2.57% to 97.76 while gold declined 0.63% to 4,356.20. UK natural gas edged up 0.18% to 2.84 and Bitcoin fell 1.35% to 85,430.51. No UK data releases or Bank of England speeches occurred, leaving market moves driven by global flows and positioning ahead of the week’s PMI prints.
The absence of domestic catalysts kept focus on technical levels in gilts and equities.
The Day Ahead
Attention turns to the CBI Industrial Trends Orders Level at 02:00, with consensus at -34 versus the prior -25. This medium-impact survey provides an early signal on manufacturing sentiment ahead of the higher-profile S&P Global Manufacturing and Services PMI flashes scheduled for 00:30 tomorrow. Those releases carry consensus readings of 51.4 and 52.0 respectively.
Later in the week, speeches from BoE officials Bean, Dhingra and Breeden plus the GfK Consumer Confidence print will offer further policy clues. Markets will parse the PMI details for any signs of softening momentum that could influence near-term rate expectations.
Other Economic Notes
Public sector finances data for August highlighted ongoing fiscal pressures, reinforcing warnings from former BoE economists that the UK remains on thin fiscal ice. Unions and think-tanks are urging an expanded National Wealth Fund to channel investment into growth areas amid subdued domestic demand. The Office for National Statistics continues work on a thematic account to measure artificial intelligence’s contribution to the economy, a longer-term initiative that may eventually inform productivity assessments.
These themes underscore structural challenges that sit alongside the near-term focus on inflation and labour-market data.