UK Macro Daily(Beta Mode)
Gilts Rally on UK Borrowing Surge
Market Snapshot
| Asset | Level | Change |
|---|---|---|
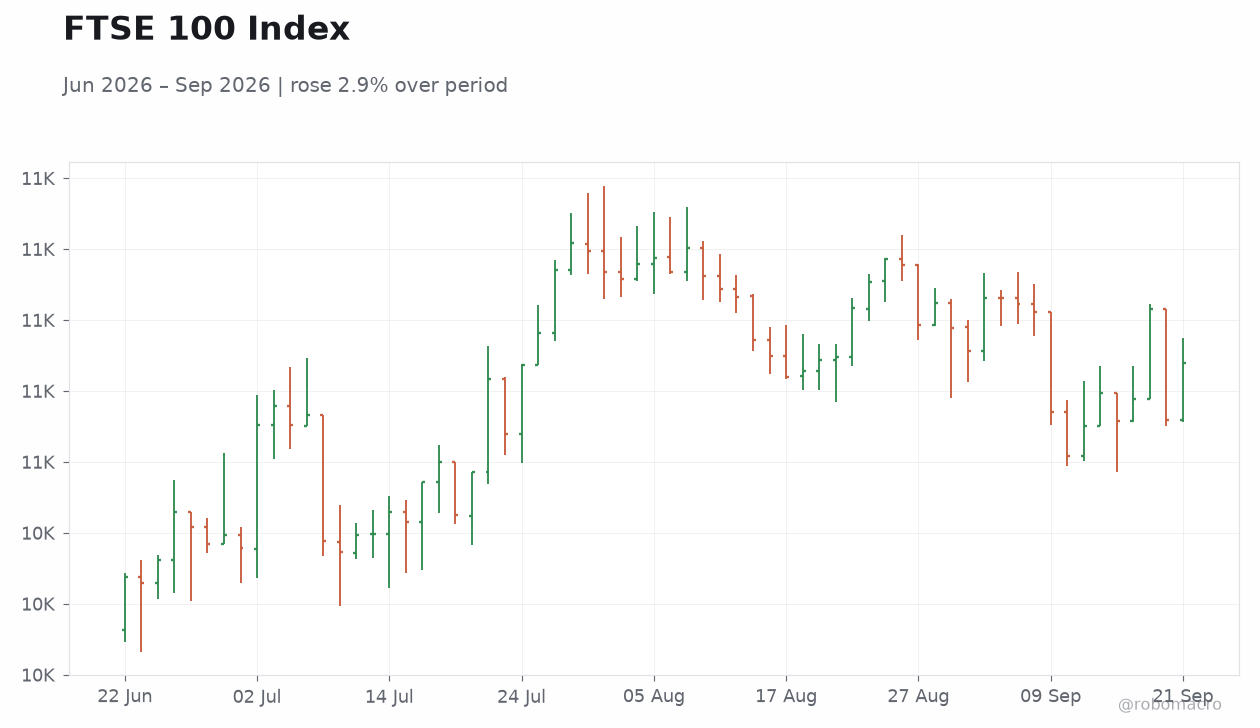
| FTSE 100 | 10,724.26 | -0.14% |
| FTSE 250 | 24,491.40 | +1.18% |
| GBP/USD | 1.33 | -0.43% |
| GBP/EUR | 1.16 | -0.09% |
| GBP/JPY | 209.84 | -0.26% |
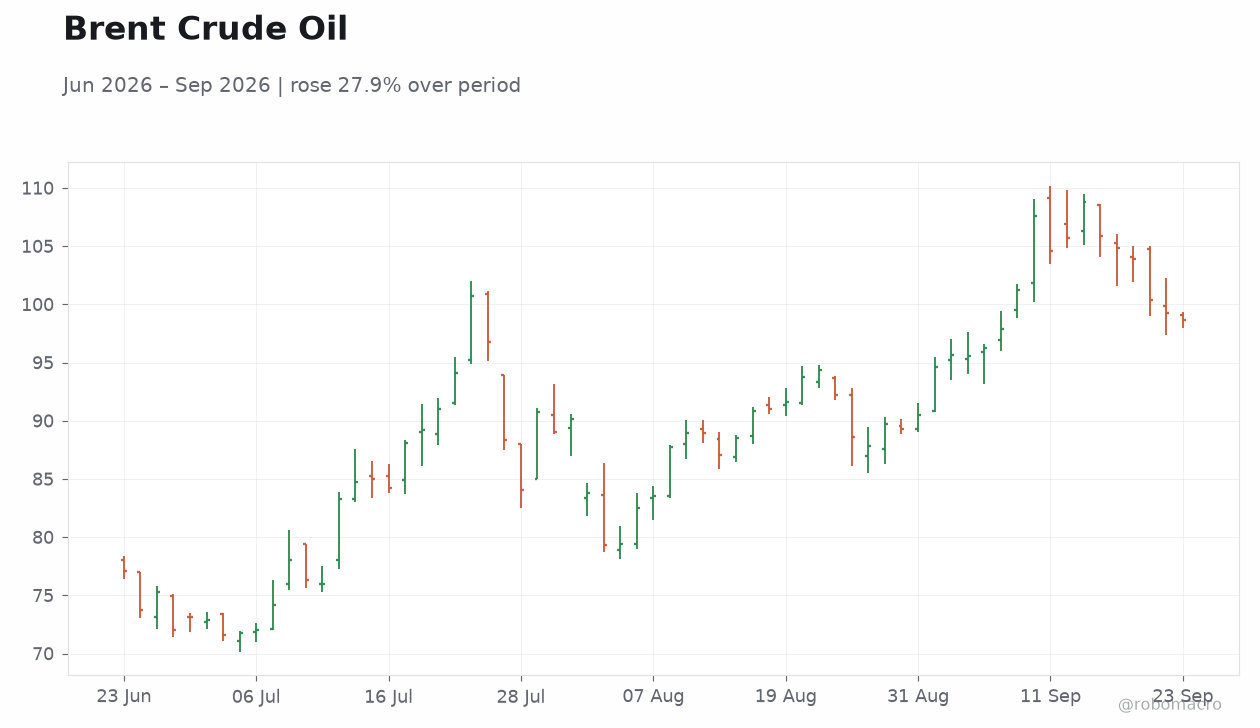
| Brent Crude | 98.61 | -0.64% |
| Gold | 4,367.90 | -0.19% |
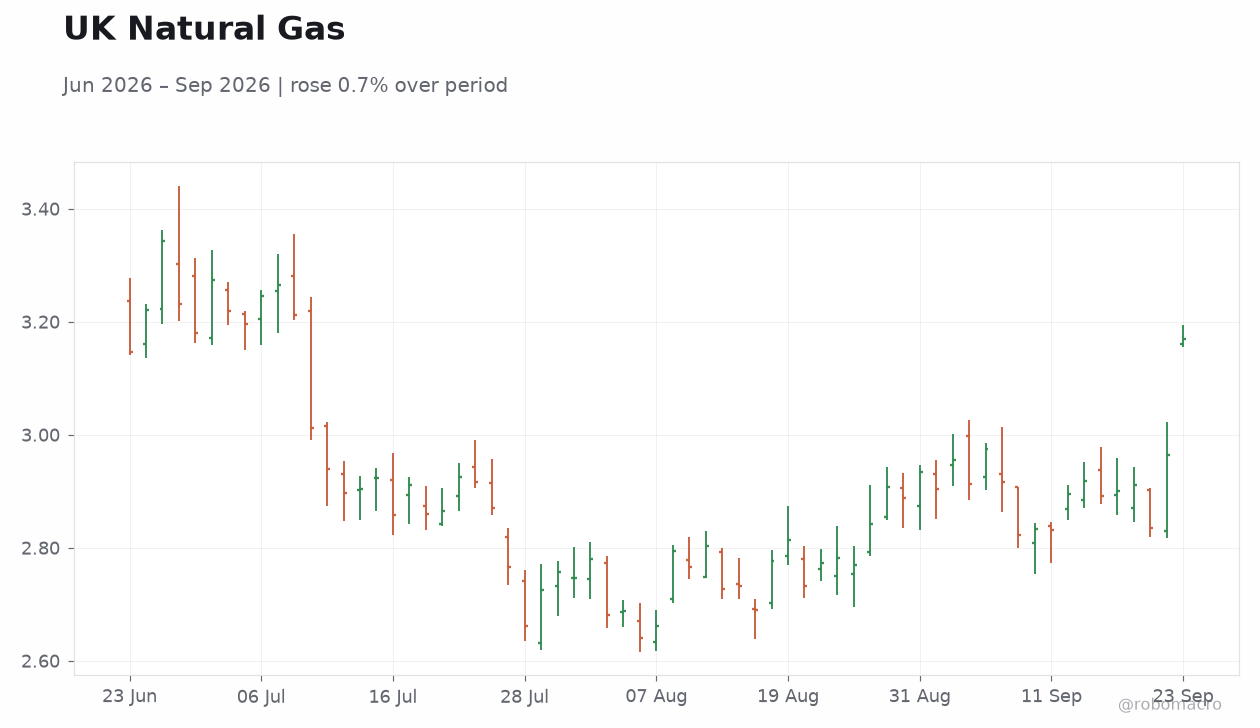
| UK Nat Gas | 3.17 | +6.88% |
| Bitcoin | 86,455.05 | -0.17% |
| UK 2Y Gilt | 4.56% | -10 bp |
| UK 10Y Gilt | 5.19% | -10 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
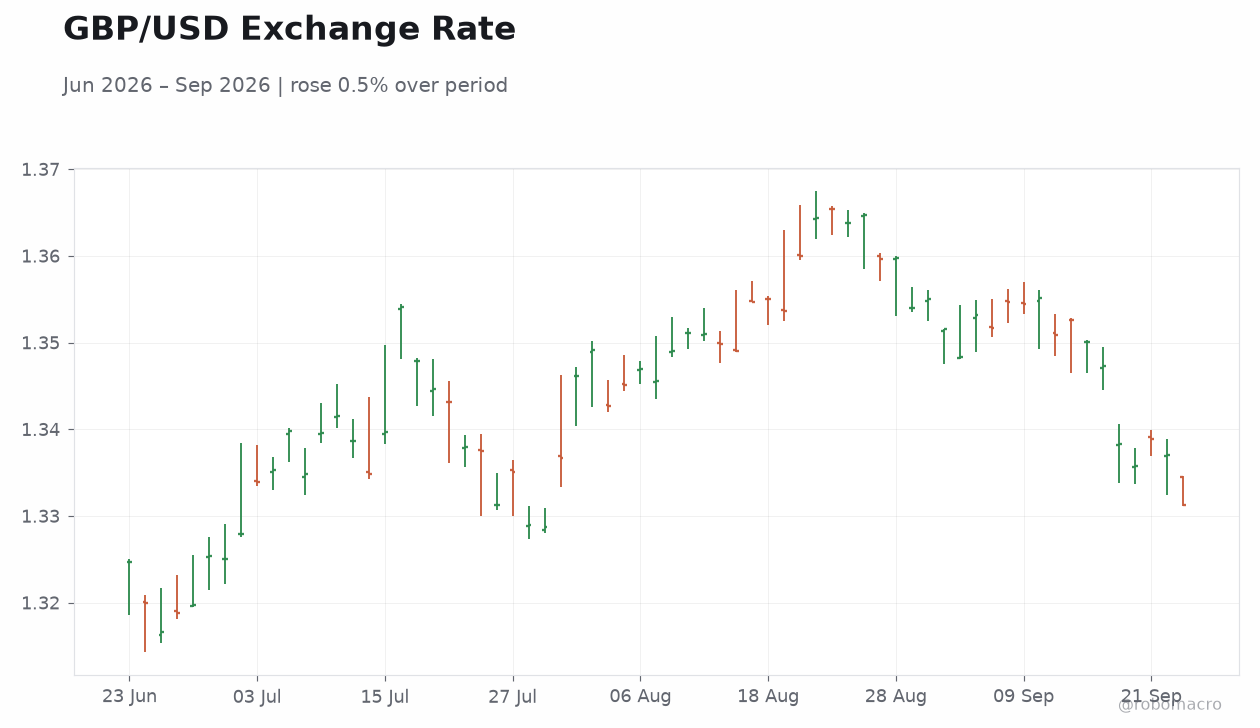 GBP/USD Exchange Rate | Type: market_hloc | Rate: 1.331 (2026-09-23) | Range: 1.317–1.365 | Trend(6pt): 1.325,1.34,1.347,1.36,1.339,1.331
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- UK 2-year and 10-year gilt yields fell 10 bp to 4.56% and 5.19% respectively on borrowing data
- Sterling weakened with GBP/USD down 0.43% to 1.33 amid quiet data calendar
- FTSE 250 rose 1.18% while FTSE 100 slipped 0.14% as mid-caps outperformed
Yesterday's Recap
No economic releases appeared in the FinanceFlow calendar for 22 September. Public sector borrowing data showed an unexpected surge that added pre-Budget pressure on the chancellor. The FTSE 100 closed at 10,724.26, down 0.14%, while the FTSE 250 advanced 1.18% to 24,491.40.
Sterling posted broad losses with GBP/USD at 1.33, GBP/EUR at 1.16 and GBP/JPY at 209.84. UK 2-year gilt yields eased 10 bp to 4.56% and 10-year yields fell 10 bp to 5.19%. UK natural gas surged 6.88% to 3.17 while Brent crude declined 0.64% to 98.61.
Gold edged 0.19% lower to 4,367.90. City A.M. highlighted JD Sports results and Manchester United earnings as focal points for the FTSE 100.
BBC Business reported that Prime Minister Burnham warned new EU industry rules would damage the UK during his UN General Assembly meetings with the European Commission President.
The Day Ahead
The FinanceFlow calendar lists zero scheduled UK releases or Bank of England events for 23 September. No MPC speeches, minutes or Inflation Report updates are due. Markets will therefore focus on any follow-through from yesterday’s borrowing figures and pre-Budget positioning.
Sterling and gilt curves are expected to remain sensitive to fiscal headlines. Equity trading may centre on company results from JD Sports and Manchester United. Global banks warned that the UK windfall tax could accelerate a shift of activity away from London.
Chancellor Healey faces tighter fiscal headroom ahead of next month’s Budget.
Other Economic Notes
Global banks warned that the UK windfall tax could accelerate a shift of activity away from London. Prime Minister Burnham told the European Commission President that new EU industry rules would damage UK competitiveness. Public sector finances data for August highlighted the scale of the borrowing overshoot.
Chancellor Healey faces tighter fiscal headroom ahead of next month’s Budget. ↓ p.2