UK Macro Daily(Beta Mode)
OECD Backs BoE Hold Amid Cooling Inflation
Market Snapshot
| Asset | Level | Change |
|---|---|---|
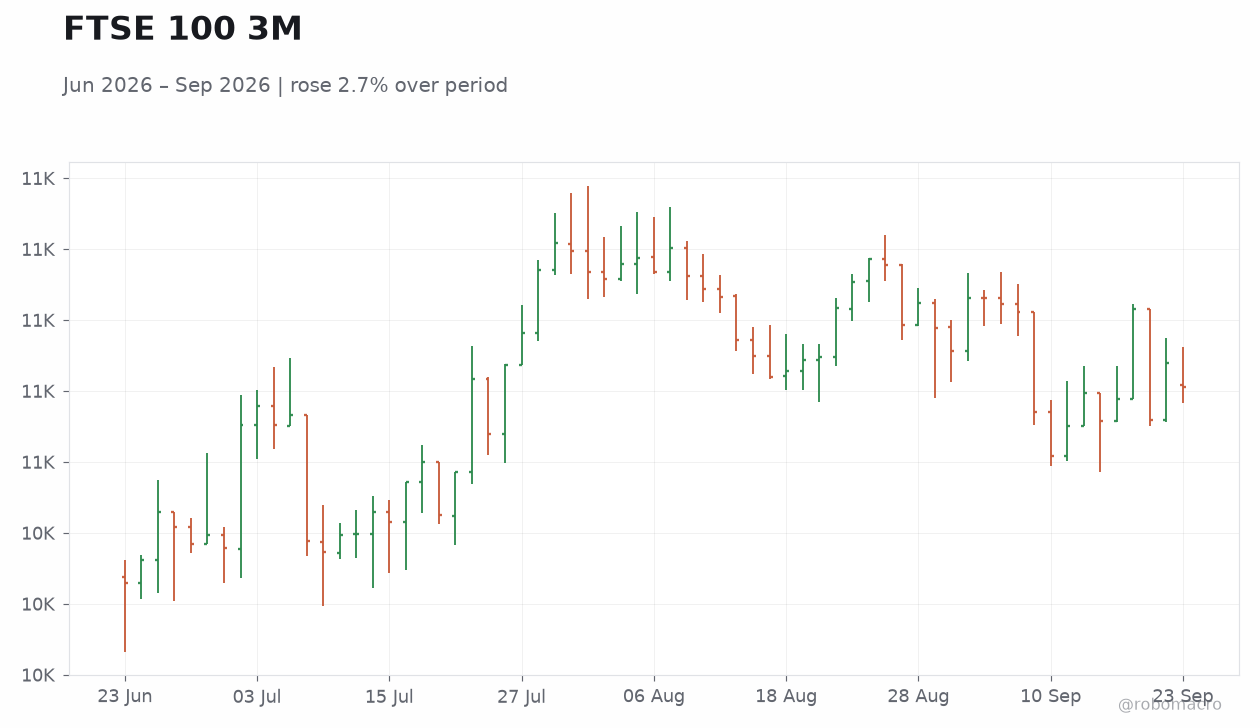
| FTSE 100 | 10,705.26 | -0.18% |
| FTSE 250 | 24,361.60 | -0.53% |
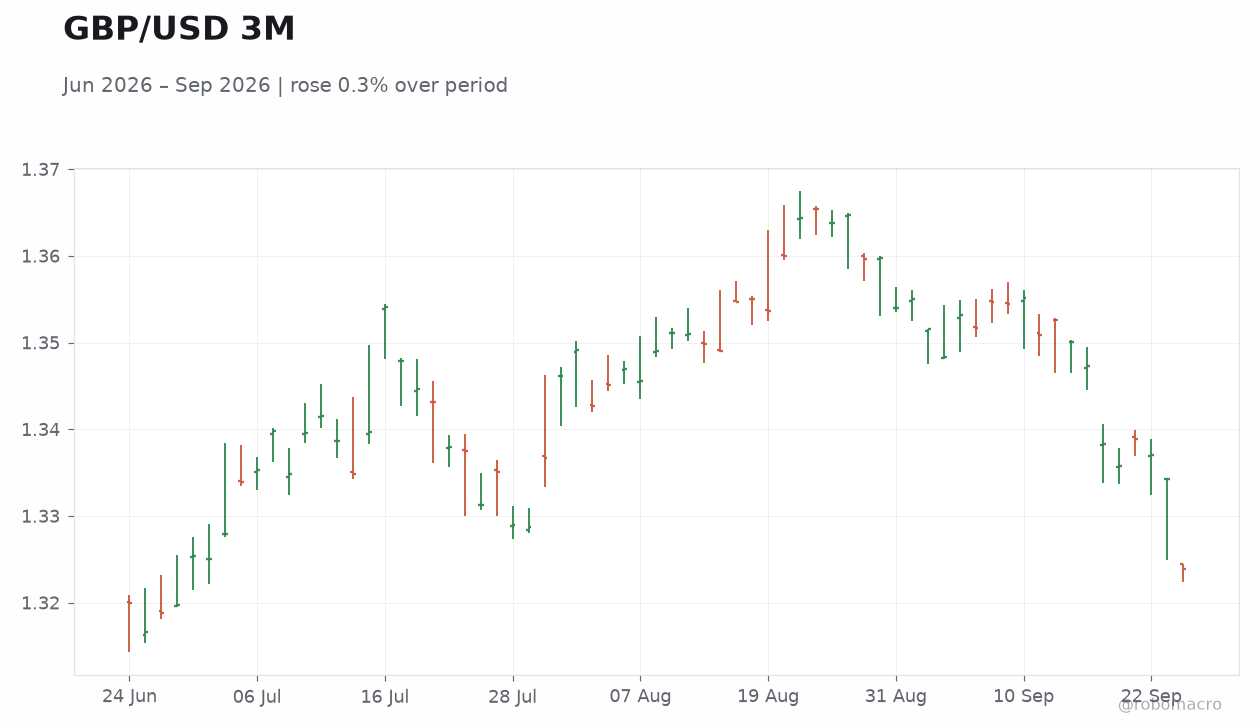
| GBP/USD | 1.32 | -0.80% |
| GBP/EUR | 1.16 | -0.22% |
| GBP/JPY | 210.10 | -0.13% |
| Brent Crude | 98.15 | -4.78% |
| Gold | 4,317.30 | -0.03% |
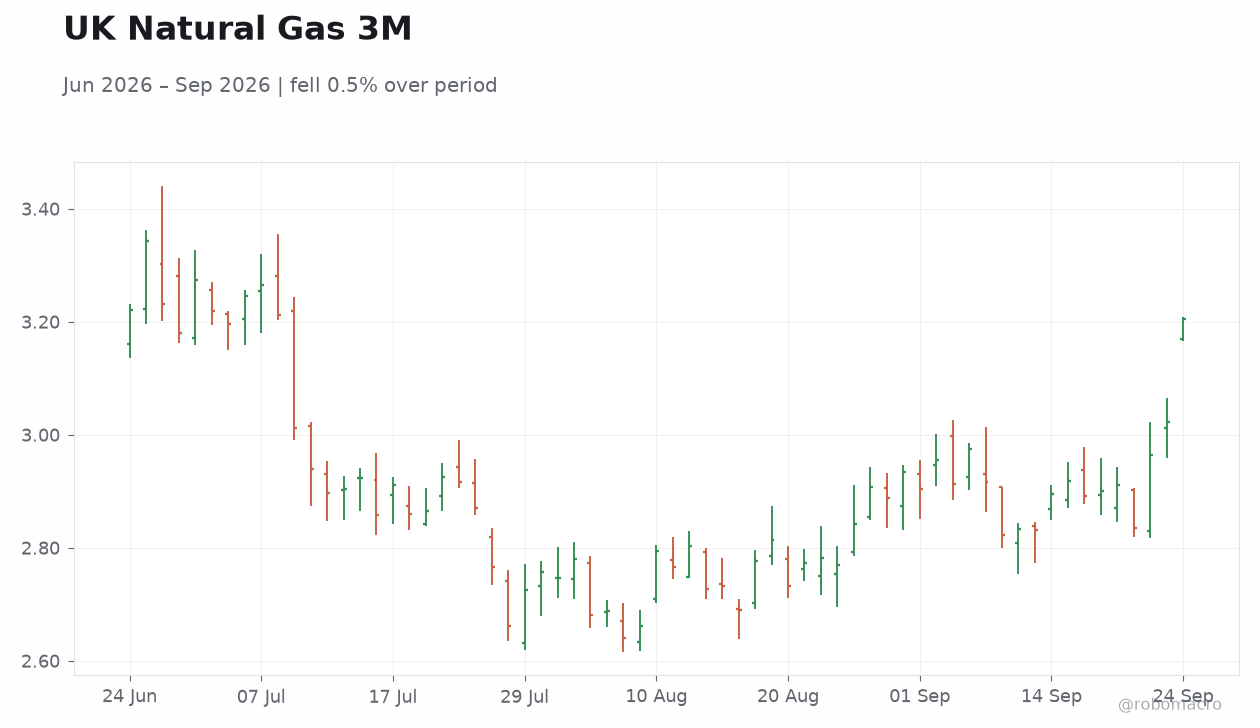
| UK Nat Gas | 3.21 | +6.05% |
| Bitcoin | 83,919.07 | -2.61% |
| UK 2Y Gilt | 4.57% | +1 bp |
| UK 10Y Gilt | 5.21% | +2 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
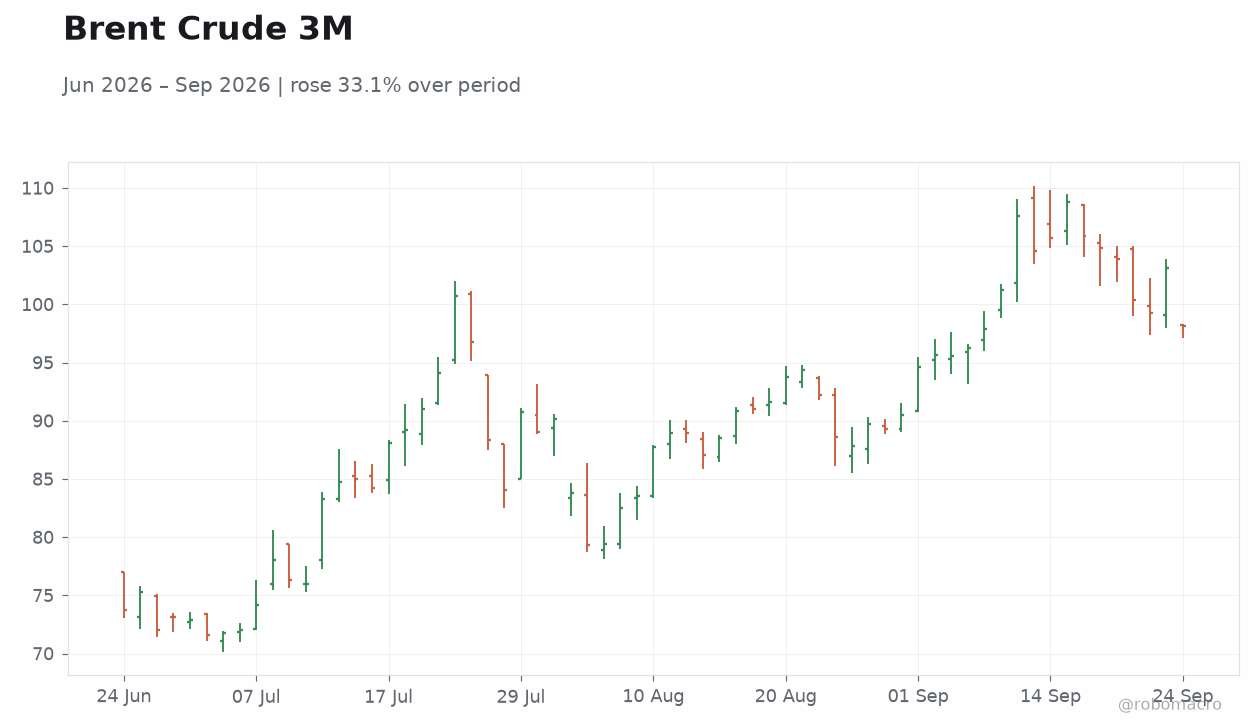 Brent Crude 3M | Type: market_hloc | USD/bbl: 98.14 (2026-09-24) | Range: 71.57–108.8 | Trend(5pt): 73.74,88.1,87.72,94.65,98.14
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- FTSE 100 fell 0.18% to 10,705.26 while sterling weakened sharply against the dollar.
- OECD advised the Bank of England to hold rates steady as UK inflation cools faster than expected.
- Brent crude dropped 4.78% to 98.15 on US-Iran diplomatic progress, lifting UK natural gas 6.05%.
Yesterday's Recap
UK markets recorded no data releases on 23 September. The FTSE 100 closed 0.18% lower at 10,705.26 and the FTSE 250 declined 0.53% to 24,361.60. Sterling fell 0.80% to 1.32 against the dollar and 0.22% to 1.16 versus the euro.
UK 2-year gilt yields rose 1 bp to 4.57% and 10-year yields added 2 bp to 5.21%. Brent crude fell sharply after reports of US-Iran talks, while UK natural gas rose 6.05% to 3.21. No MPC speeches or inflation prints occurred.
Manchester United posted record revenues of £677.6m for the year to June 2026 but recorded a seventh straight annual loss of £43m. The UK published its full list of occupations eligible for the Skilled Worker visa.
The Day Ahead
No UK economic releases or Bank of England events are scheduled for 24 September. Markets will monitor any follow-up comments on US-Iran diplomacy that could affect energy prices. Sterling and gilt yields are expected to trade in line with broader dollar moves.
OECD forecasts of faster 2026 growth followed by a 2027 slowdown will remain in focus. Traders await any updates on the upcoming Budget and potential bank tax proposals. UK Finance warned that a Budget bank tax could push mortgage rates higher.
Other Economic Notes
The OECD highlighted that UK inflation has cooled faster than expected, supporting a steady Bank Rate at 3.73%. UK CPI stood at 3.10% in August and unemployment at 4.90% in June. The Paris-based body noted the UK starts from a different monetary position than peers and sees no need for immediate rate hikes.
GDP growth is projected to exceed earlier forecasts this year before slowing in 2027. The Bank of England is expanding focus on central bank banking services and plans a new Leeds office, viewed as a domestic endorsement.
Global Macro News
Oil prices fell after President Trump described US-Iran talks as “very good,” pressuring Brent below 100. The Canadian dollar weakened on widening rate differentials with the US. ↓ p.2