UK Macro Daily(Beta Mode)
Mixed UK PMI Data Lifts Gilt Yields
Market Snapshot
| Asset | Level | Change |
|---|---|---|
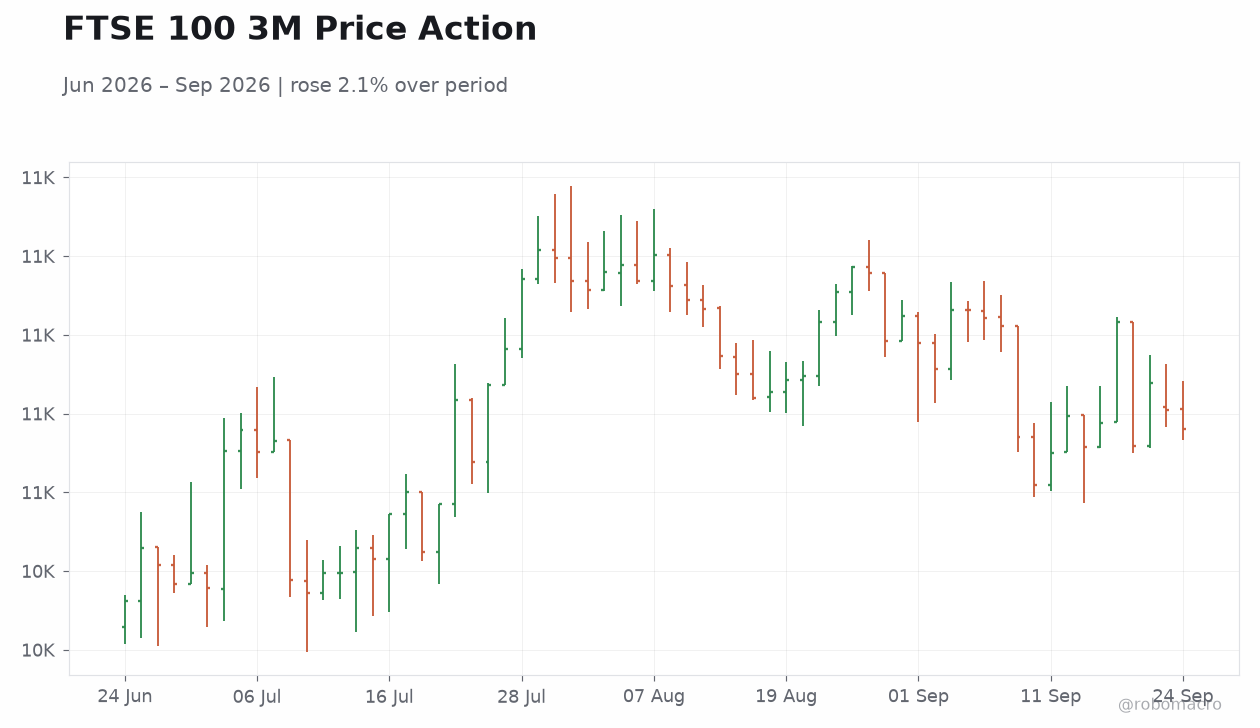
| FTSE 100 | 10,712.72 | +0.07% |
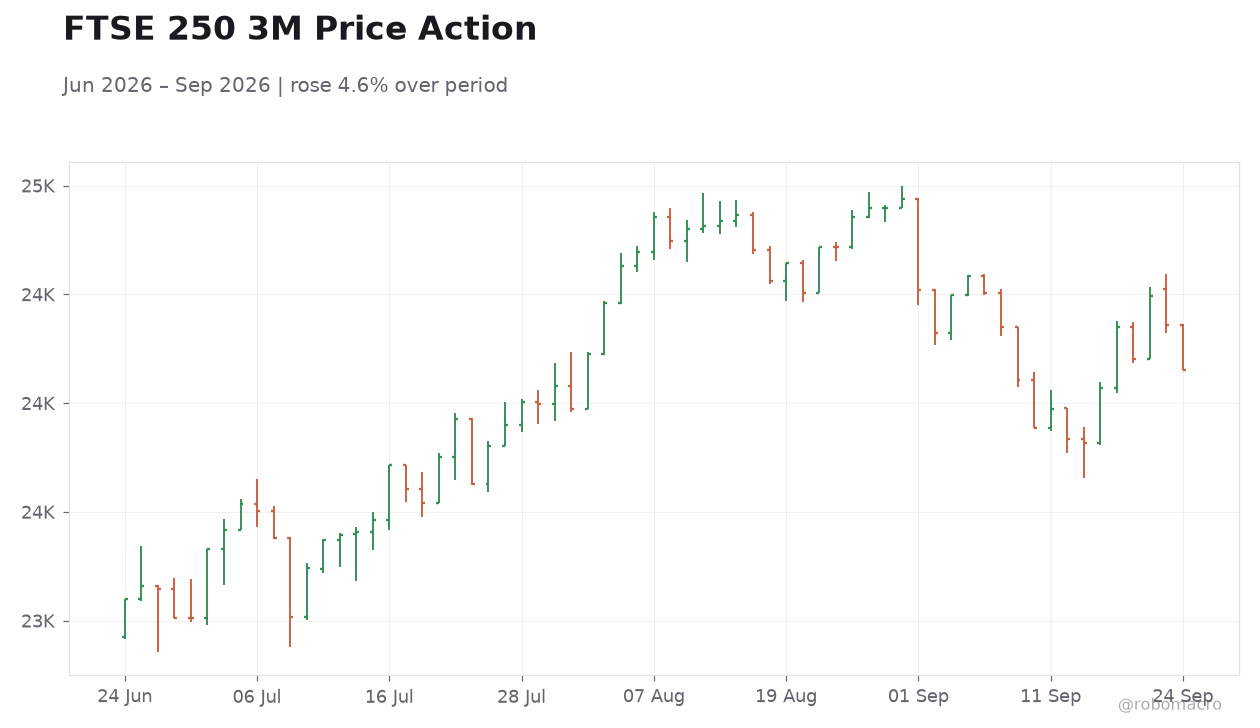
| FTSE 250 | 24,154.30 | -0.85% |
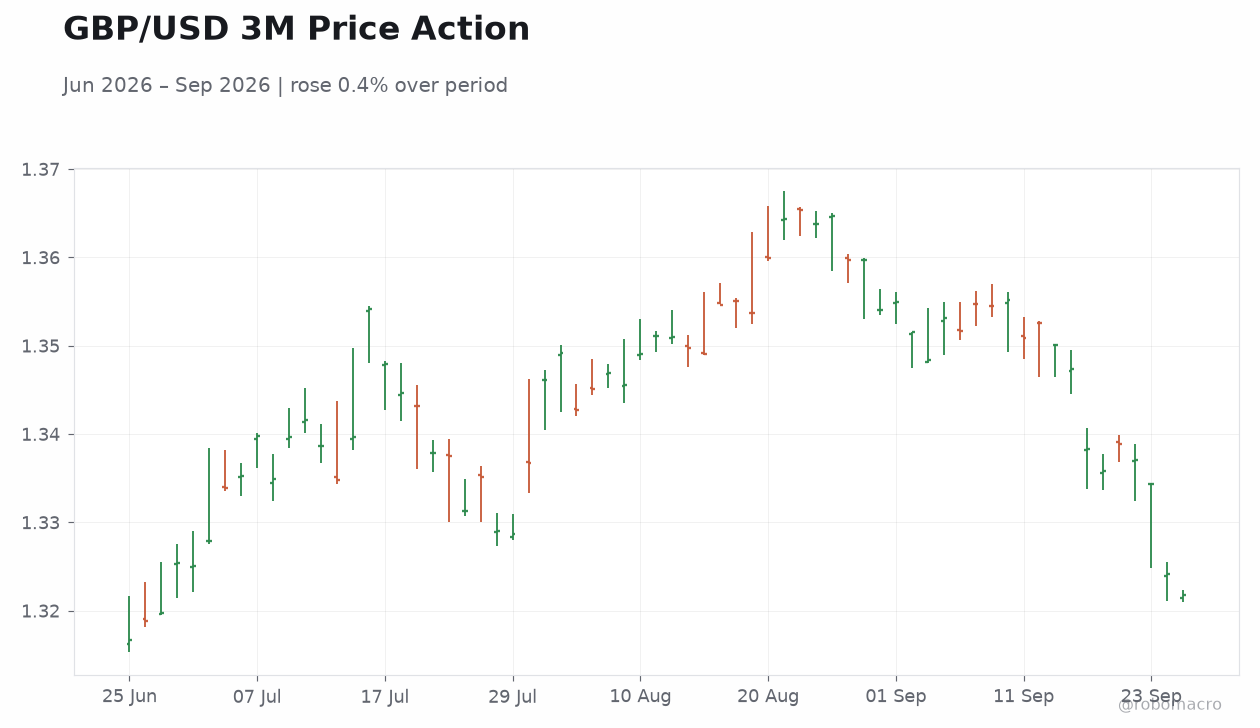
| GBP/USD | 1.32 | -0.17% |
| GBP/EUR | 1.16 | -0.15% |
| GBP/JPY | 209.12 | -0.19% |
| Brent Crude | 105.24 | -1.28% |
| Gold | 4,305.50 | +0.17% |
| UK Nat Gas | 3.29 | -0.24% |
| Bitcoin | 84,172.77 | -0.25% |
| UK 2Y Gilt | 4.67% | +10 bp |
| UK 10Y Gilt | 5.31% | +10 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| CBI Industrial Trends Orders | -25 | -34 | -9 |
| S&P Global Manufacturing PMI Flash | 51.70 | 51.50 | 52 |
| S&P Global Services PMI Flash | 52.50 | 52 | 51.70 |
| BoE Bean Speech | - | - | - |
| BoE Dhingra Speech | - | - | - |
| CBI Distributive Trades | -48 | -50 | -55 |
| BoE Breeden Speech | - | - | - |
| GFK Consumer Confidence Index | -14 | -16 | -13 |
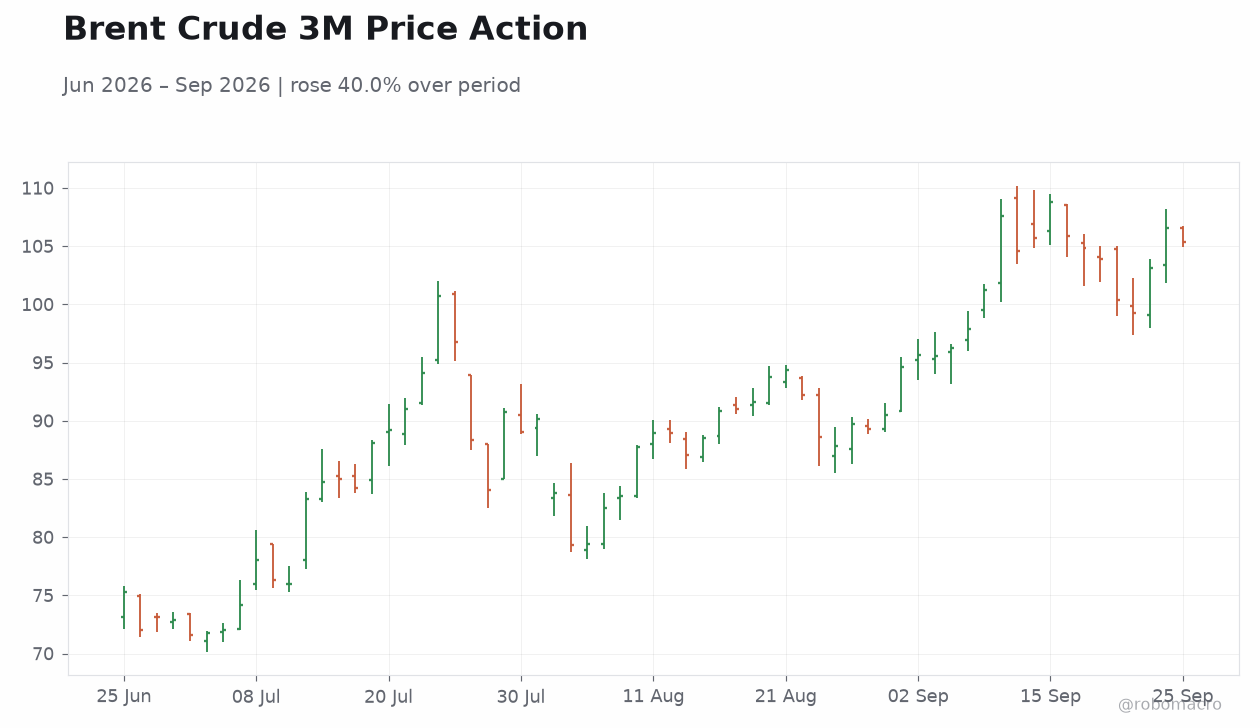 Brent Crude 3M Price Action | Type: market_hloc | USD/bbl: 105.4 (2026-09-25) | Range: 71.57–108.8 | Trend(5pt): 75.26,89.22,88.91,95.63,105.4
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- UK manufacturing PMI beat expectations at 52.0 while services slipped to 51.7.
- Gilt yields rose 10 bp across the curve as BoE speakers flagged energy risks.
- Sterling weakened modestly against major crosses amid mixed survey data.
Yesterday's Recap
UK data releases delivered a mixed picture. CBI Industrial Trends Orders improved sharply to -9 against a -34 consensus. S&P Global Manufacturing PMI Flash rose to 52.0, exceeding the 51.5 forecast, while Services PMI Flash fell to 51.7 versus 52.0 expected.
CBI Distributive Trades missed at -55 and GfK Consumer Confidence beat at -13. FTSE 100 edged up 0.07 percent to 10,712.72 but FTSE 250 fell 0.85 percent. GBP/USD declined 0.17 percent to 1.32 and gilt yields climbed 10 bp, with the 2-year at 4.67 percent and 10-year at 5.31 percent.
Brent crude dropped 1.28 percent to 105.24 amid shifting supply signals. BoE Bean, Dhingra and Breeden speeches took place without market-moving comments. The prints left rate expectations largely unchanged.
The Day Ahead
No UK economic releases or BoE events are scheduled for 25 September. Markets will monitor global oil developments and any follow-through from yesterday’s BoE speeches by Bean, Dhingra and Breeden. Sterling crosses and gilt yields are likely to remain sensitive to Middle East headlines.
Traders will also watch US data for indirect effects on UK rate expectations. Attention stays on whether the mixed PMI signals sustain the recent divergence between manufacturing and services sectors.
Other Economic Notes
UK CPI stands at 3.10 percent year-on-year and unemployment at 4.90 percent, keeping the policy backdrop steady at the 3.73 percent Bank Rate. Recent survey beats in manufacturing and consumer confidence contrast with services weakness, suggesting uneven domestic momentum. Gilt yield rises reflect both global rate pressures and domestic inflation vigilance.
Broader fiscal scrutiny, including parliamentary review of the BoE remit, adds another layer of uncertainty for fixed-income markets.
Global Macro News
Oil prices reacted to renewed Houthi attacks and Saudi interception of missiles, lifting supply concerns that feed directly into UK energy costs. ↓ p.2