UK Macro Daily(Beta Mode)
Ramsden Speech Tests BoE Rate Path
Market Snapshot
| Asset | Level | Change |
|---|---|---|
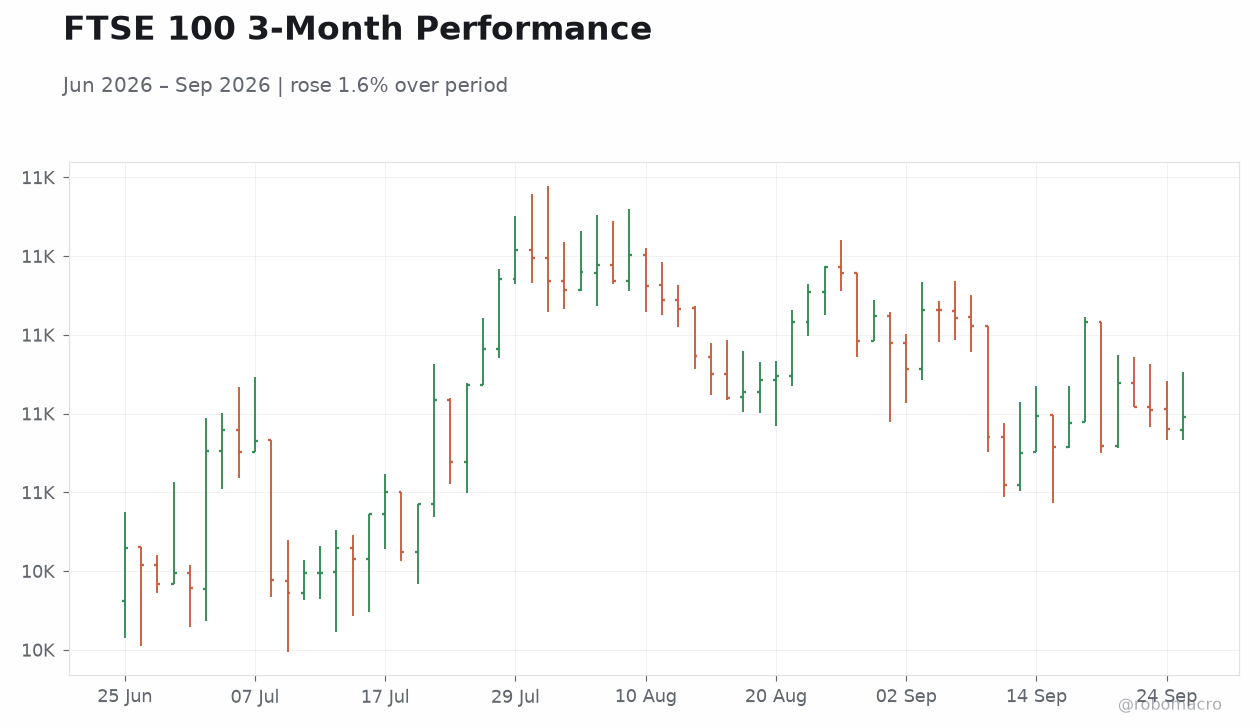
| FTSE 100 | 10,695.30 | +0.14% |
| FTSE 250 | 24,261.10 | +0.44% |
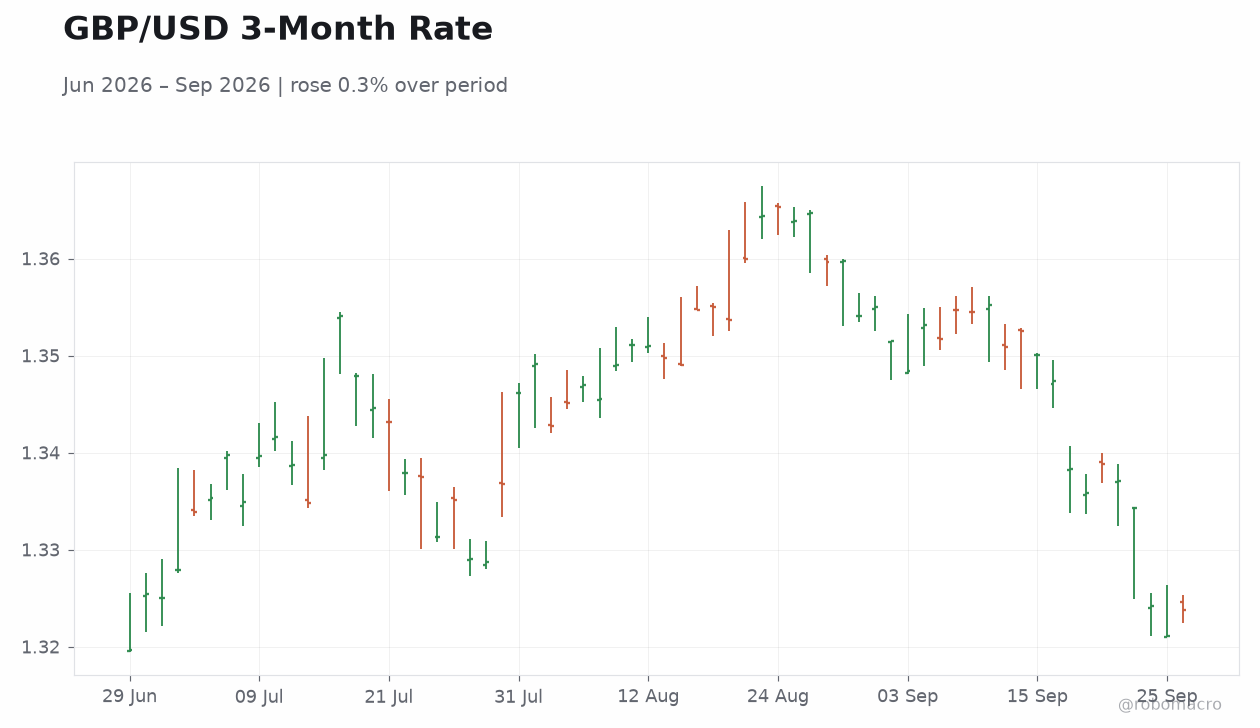
| GBP/USD | 1.32 | +0.19% |
| GBP/EUR | 1.16 | +0.12% |
| GBP/JPY | 208.81 | -0.47% |
| Brent Crude | 99.15 | -4.96% |
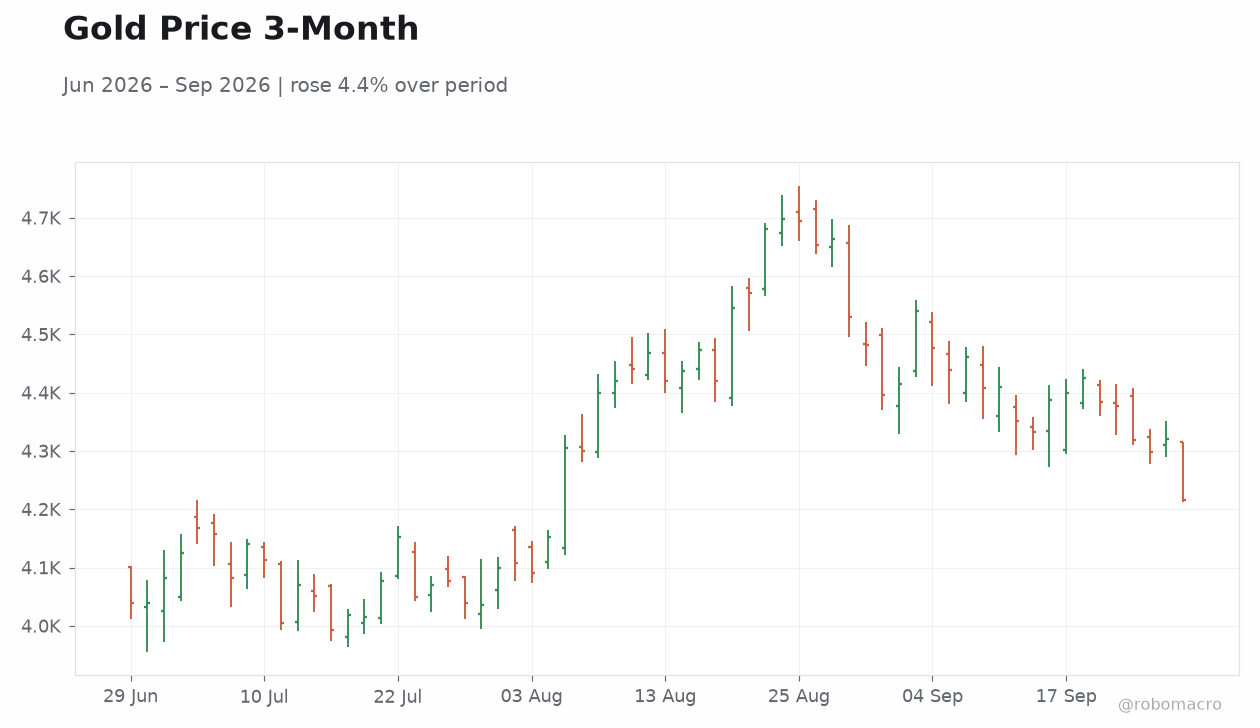
| Gold | 4,214.00 | -2.48% |
| UK Nat Gas | 3.12 | -2.22% |
| Bitcoin | 83,162.26 | -1.47% |
| UK 2Y Gilt | 4.69% | +2 bp |
| UK 10Y Gilt | 5.36% | +5 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| No events available | |||
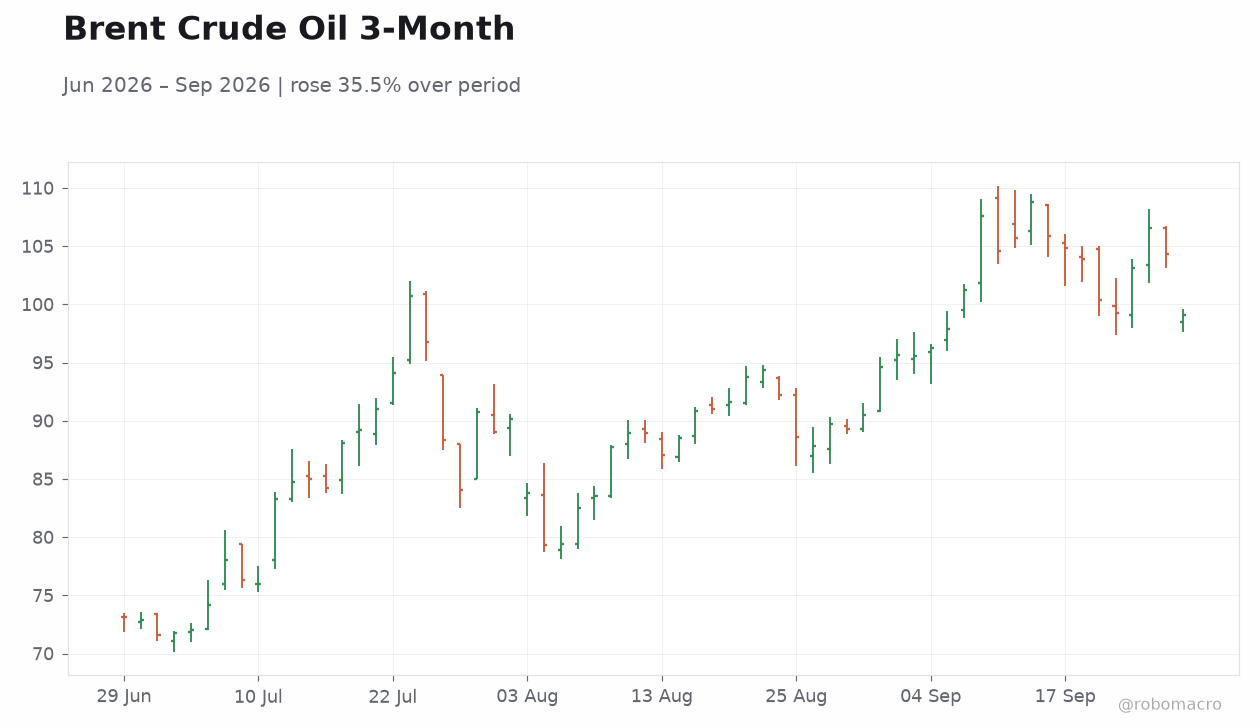 Brent Crude Oil 3-Month | Type: market_hloc | Brent Crude $/bbl: 99.11 (2026-09-28) | Range: 71.57–108.8 | Trend(5pt): 73.15,94.07,87.07,96.28,99.11
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| BoE Ramsden Speech | - | - | 02:00 |
| Tuesday (2026-09-29) | |||
| BoE Consumer Credit | 2,006m | - | 00:30 |
| Mortgage Approvals | 56,050 | 58,000 | 00:30 |
| Mortgage Lending Level | 4,290m | - | 00:30 |
| BoE Taylor Speech | - | - | 07:30 |
| Wednesday (2026-09-30) | |||
| Current Account Balance | -22,100m | -25,600m | 22:00 |
| Nationwide Housing Prices Month-over-Month | 0.20 | 0.20 | 22:00 |
| Nationwide Housing Prices Year-over-Year | 1.60 | - | 22:00 |
- BoE Ramsden speech at 02:00 draws focus after gilt yields rose
- FTSE 100 edged 0.14% higher to 10,695.30 as sterling mixed
- Brent crude fell 4.96% to 99.15 amid softer energy prices
Yesterday's Recap
UK markets recorded no data releases on 27 September. The FTSE 100 closed at 10,695.30, up 0.14%, while the FTSE 250 gained 0.44% to 24,261.10. Sterling showed mixed moves, with GBP/USD rising 0.19% to 1.32 and GBP/EUR advancing 0.12% to 1.16, though GBP/JPY slipped 0.47% to 208.81.
Gilt yields increased, lifting the 2-year yield 2 bp to 4.69% and the 10-year yield 5 bp to 5.36%. Commodities declined sharply, with Brent crude dropping 4.96% to 99.15, gold falling 2.48% to 4,214.00 and UK natural gas easing 2.22% to 3.12. No MPC members spoke, leaving policy expectations anchored around the 3.73% Bank Rate.
The Day Ahead
Deputy Governor Ramsden delivers a high-impact speech at 02:00 that could shape near-term rate expectations. Tomorrow brings medium-impact UK releases including BoE Consumer Credit, Mortgage Approvals and Mortgage Lending Level at 00:30, followed by the Current Account Balance and Nationwide House Prices at 22:00. Three further BoE speeches follow on 30 September and 1 October from Taylor, Mann and Mills.
Markets will parse these comments for signals on how persistent energy prices affect the inflation outlook and the 3.10% CPI reading. Mortgage Approvals consensus sits at 58,000 versus the prior 56,050.
Other Economic Notes
Soaring shipping rates add cost pressures to UK supply chains and imported goods. Energy price spikes continue to complicate the BoE’s task of holding the 3.73% Bank Rate. Unemployment at 4.90% signals a still-tight labour market that could sustain wage pressures.
Broader fiscal calls for VAT and fuel duty cuts highlight political tension around household costs. Tokenised sterling deposit trials by UK banks mark early steps toward digital payment infrastructure. MPs have opened an inquiry into whether Bank of England independence remains fit for purpose amid these pressures.
Global Macro News
Brent crude’s 4.96% drop eases imported inflation risks for the UK but leaves volatility from Middle East tensions. US sanctions support from Turkey, Oman and UAE may sustain energy market uncertainty. Nigeria-US mining investment deals signal wider emerging-market capital flows that could affect sterling sentiment.
↓ p.2