UK Macro Daily(Beta Mode)
Ramsden Flags Rate-Hike Risk, Lifting Sterling
Market Snapshot
| Asset | Level | Change |
|---|---|---|
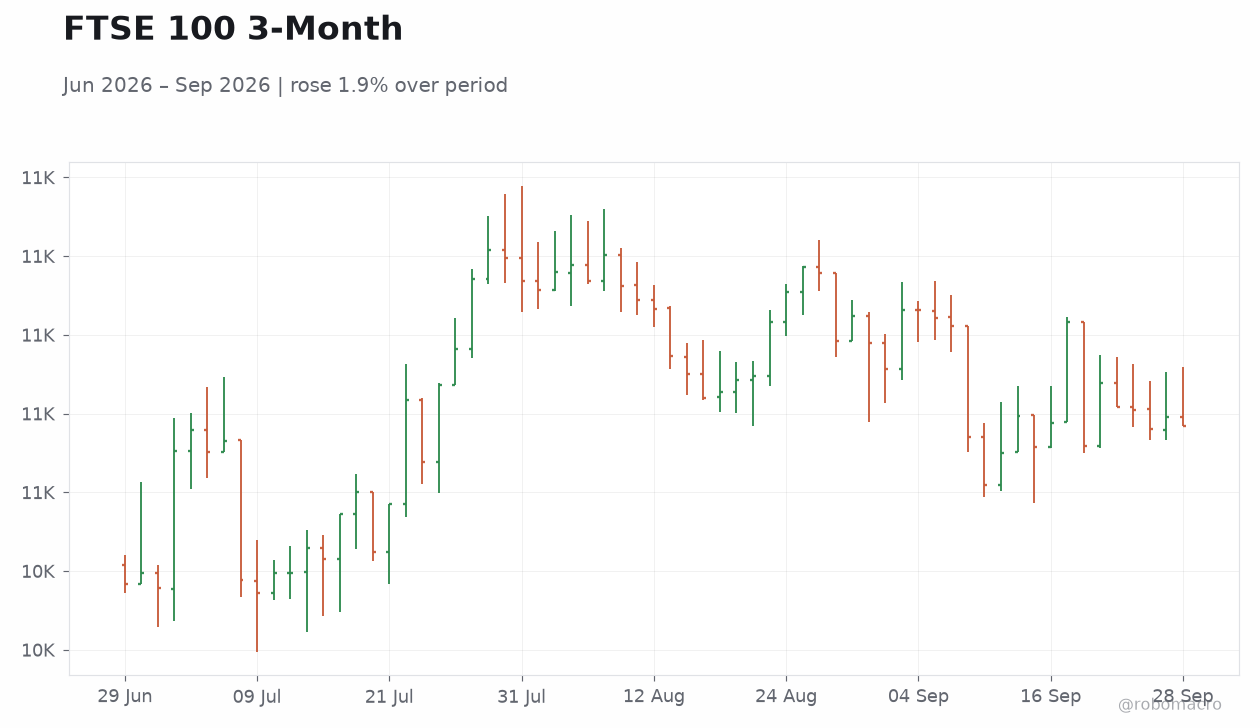
| FTSE 100 | 10,695.30 | +0.14% |
| FTSE 250 | 24,335.30 | +0.31% |
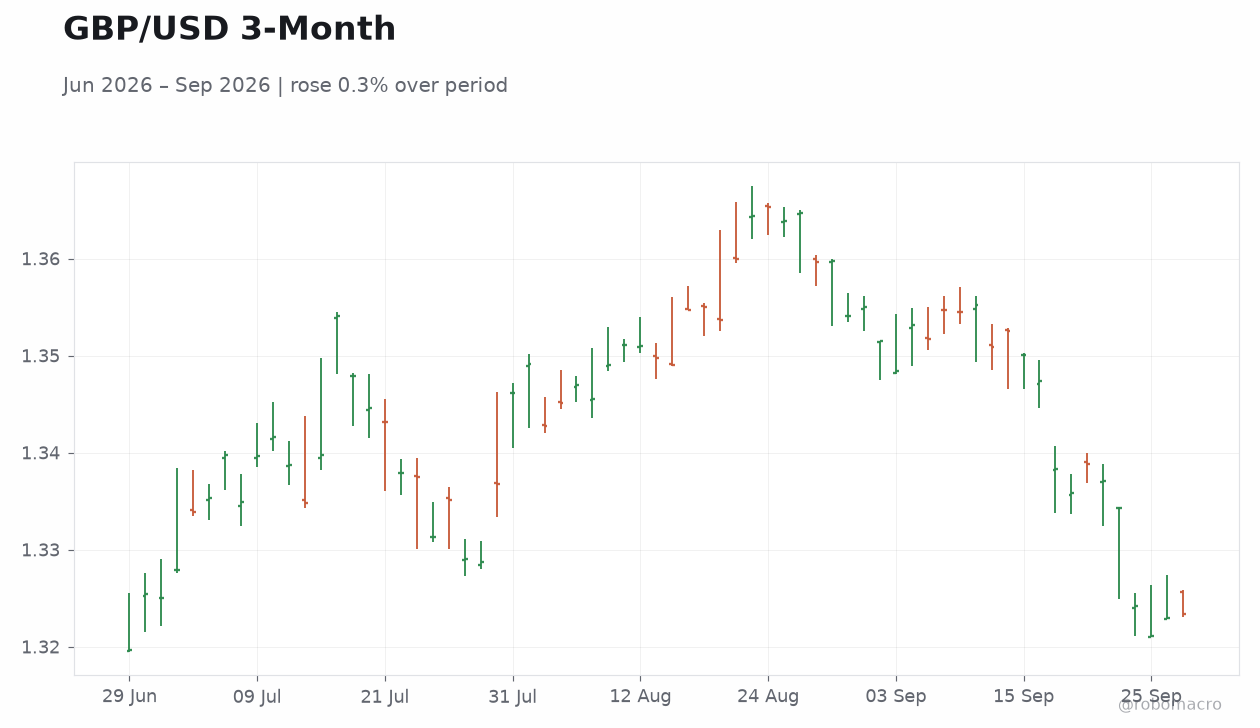
| GBP/USD | 1.32 | +0.05% |
| GBP/EUR | 1.16 | +0.22% |
| GBP/JPY | 208.23 | -0.03% |
| Brent Crude | 99.68 | -5.32% |
| Gold | 4,169.70 | +0.03% |
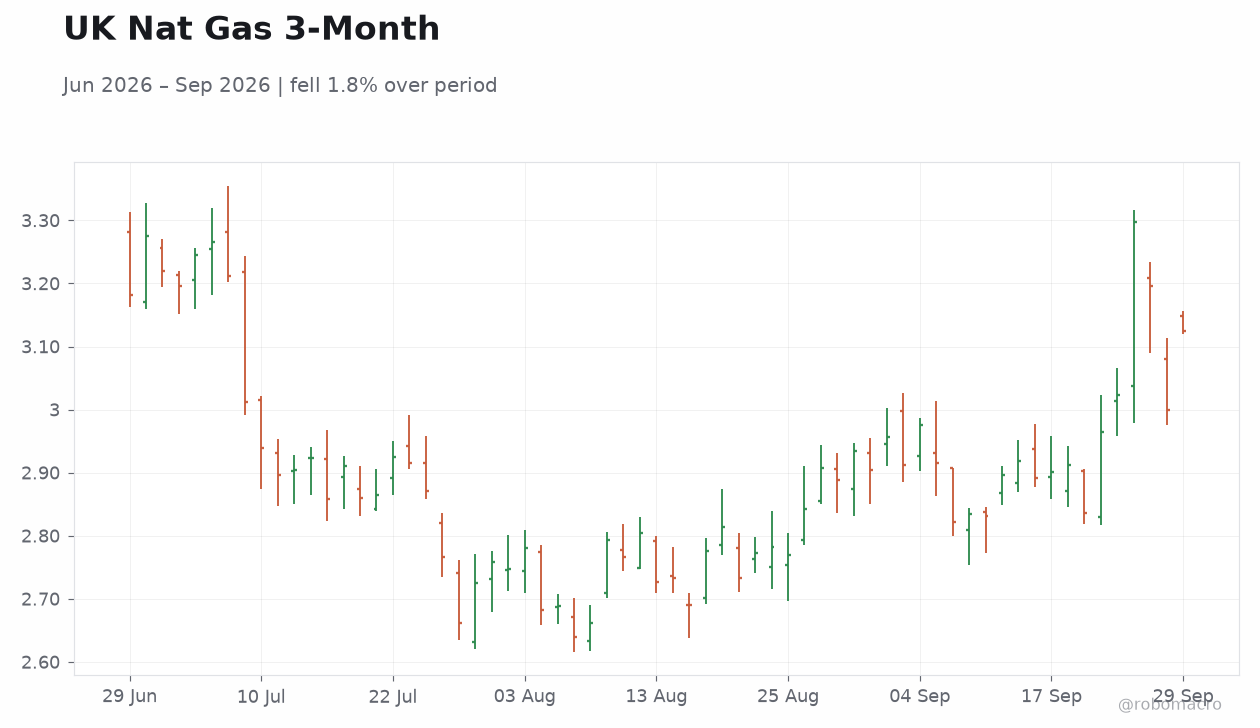
| UK Nat Gas | 3.12 | +4.17% |
| Bitcoin | 83,393.79 | -1.26% |
| UK 2Y Gilt | 4.64% | -5 bp |
| UK 10Y Gilt | 5.36% | +5 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| BoE Ramsden Speech | - | - | - |
| Chancellor John Healey Speech | - | - | - |
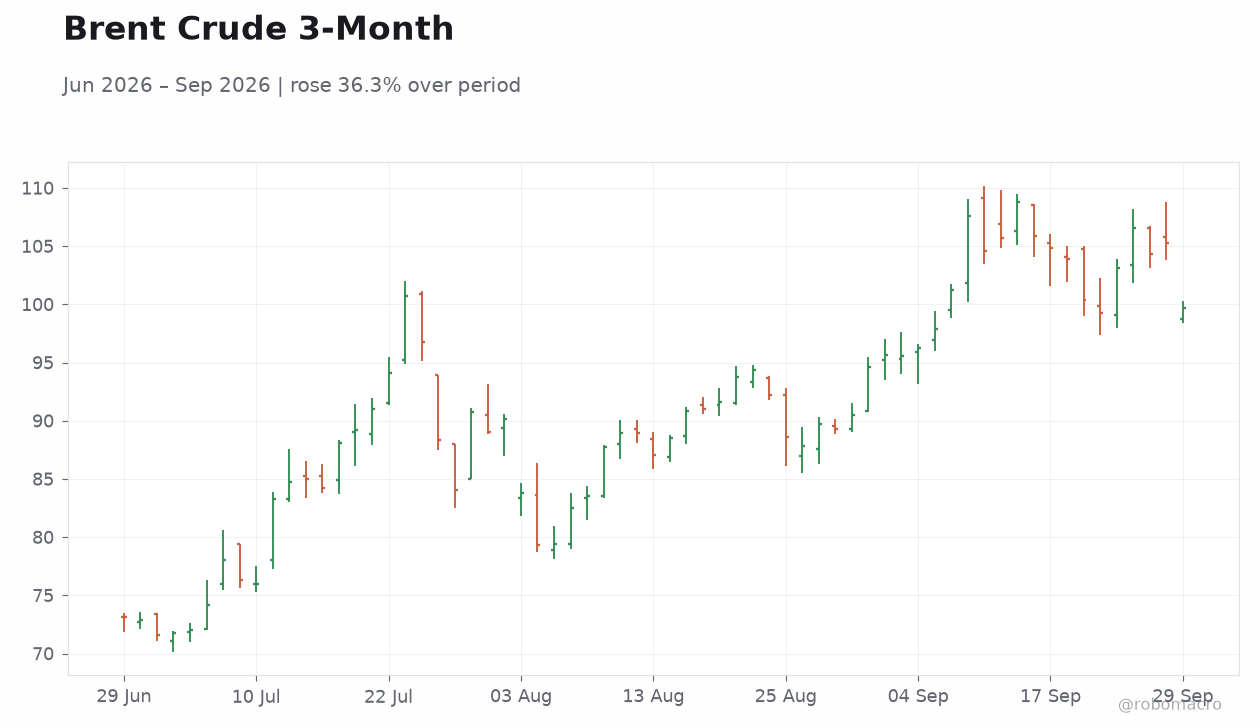 Brent Crude 3-Month | Type: market_hloc | Price USD: 99.68 (2026-09-29) | Range: 71.57–108.8 | Trend(5pt): 73.15,94.07,87.07,96.28,99.68
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| BoE Consumer Credit | 2,006m | 1,900m | 00:30 |
| Mortgage Approvals | 56,050 | 57,000 | 00:30 |
| Mortgage Lending Level | 4,290m | - | 00:30 |
| BoE Taylor Speech | - | - | 07:30 |
| Wednesday (2026-09-30) | |||
| Current Account Balance | -22,100m | -25,600m | 22:00 |
| Nationwide Housing Prices Month-over-Month | 0.20 | 0.20 | 22:00 |
| Nationwide Housing Prices Year-over-Year | 1.60 | - | 22:00 |
| Thursday (2026-10-01) | |||
| BoE Mann Speech | - | - | 04:00 |
- BoE’s Ramsden warned rates may need to rise if inflation pressures persist, lifting sterling.
- FTSE 100 rose 0.14% to 10,695.30 while 10-year gilt yields climbed 5 bp to 5.36%.
- Brent crude fell 5.32% to 99.68 amid global supply signals, adding to UK energy cost volatility.
Yesterday's Recap
No UK data prints were released on 28 September. Deputy Governor Ramsden stated that interest rates will need to rise if inflationary pressures persist, reinforcing market bets on tighter policy. Chancellor John Healey’s speech focused on fiscal discipline without altering rate expectations.
The FTSE 100 advanced 0.14% to close at 10,695.30 and the FTSE 250 gained 0.31% to 24,335.30. Sterling posted modest gains, with GBP/EUR up 0.22% to 1.16. The UK 2-year gilt yield eased 5 bp to 4.64% while the 10-year yield rose 5 bp to 5.36%.
Brent crude’s sharp 5.32% drop to 99.68 added downside pressure to energy-related inflation forecasts. UK CPI stood at 3.10% year-on-year in August while unemployment reached 4.90% in June, leaving the Bank Rate at 3.73%.
The Day Ahead
Markets will focus on 00:30 UK time releases of BoE Consumer Credit, Mortgage Approvals and Mortgage Lending Level, all expected near recent levels. BoE’s Taylor is scheduled to speak at 07:30, offering potential fresh policy signals. Later in the session, the Current Account Balance and Nationwide house price data are due at 22:00.
Any surprise in mortgage approvals or consumer credit could shift near-term sterling and gilt pricing. Traders will also monitor whether Taylor echoes Ramsden’s recent hawkish tone on persistent price pressures. Housing indicators remain central to consumption and inflation outlooks.
Other Economic Notes
UK CPI stood at 3.10% year-on-year in August while unemployment reached 4.90% in June, leaving the Bank Rate at 3.73%. Housing indicators remain central to consumption and inflation outlooks, with mortgage approvals and Nationwide prices due today. Fiscal restraint emphasised by the Chancellor continues to anchor gilt supply expectations.
Energy price swings, highlighted by Brent’s decline and UK natural gas gains, add volatility to household bills and CPI components. These factors keep the BoE’s reaction function sensitive to both demand and supply-side developments. Record diesel costs add fresh pressure on the UK economy.