UK Macro Daily(Beta Mode)
Borrowing Beats as Taylor Sees No Need to Hike
Market Snapshot
| Asset | Level | Change |
|---|---|---|
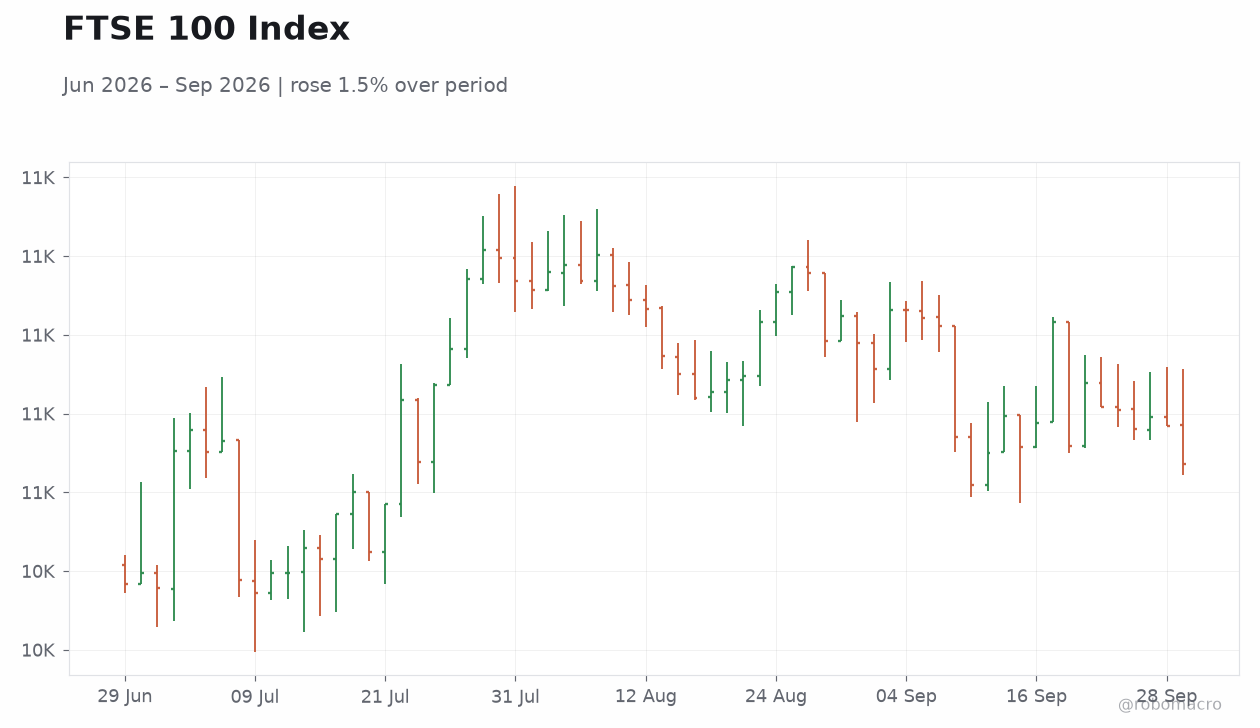
| FTSE 100 | 10,662.17 | -0.21% |
| FTSE 250 | 24,374.80 | +0.16% |
| GBP/USD | 1.33 | -0.01% |
| GBP/EUR | 1.17 | +0.13% |
| GBP/JPY | 207.90 | -0.31% |
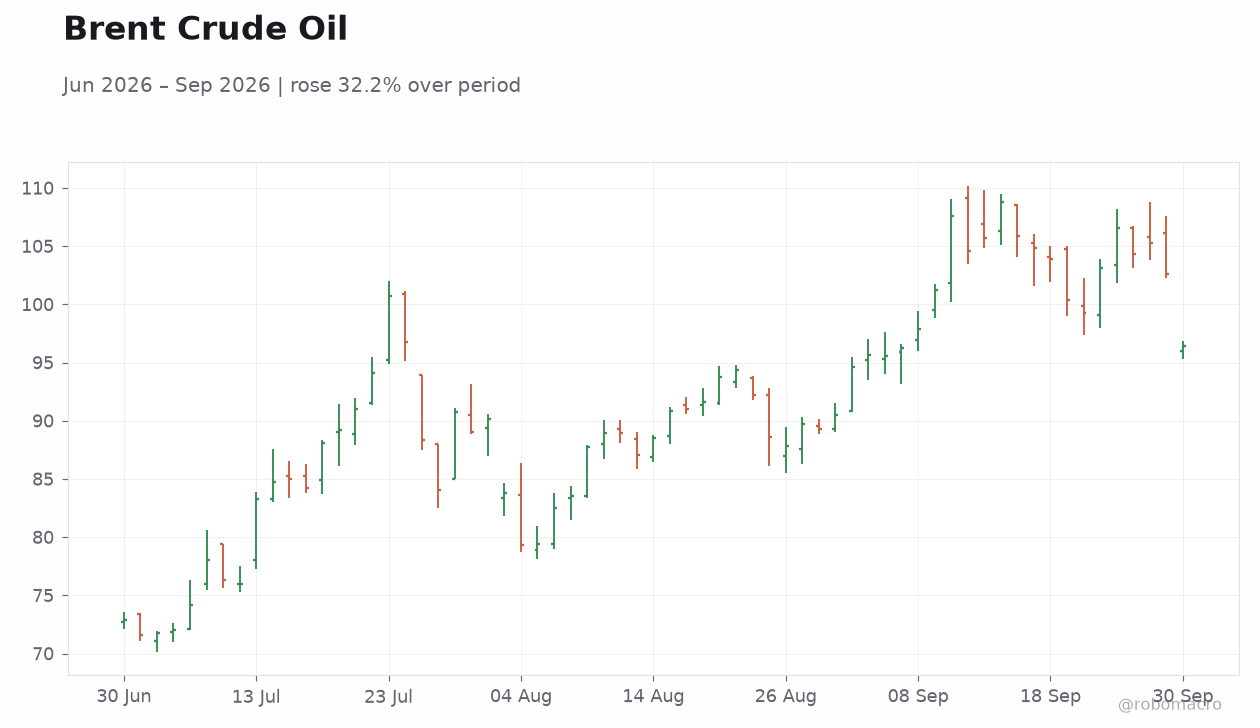
| Brent Crude | 96.39 | -6.04% |
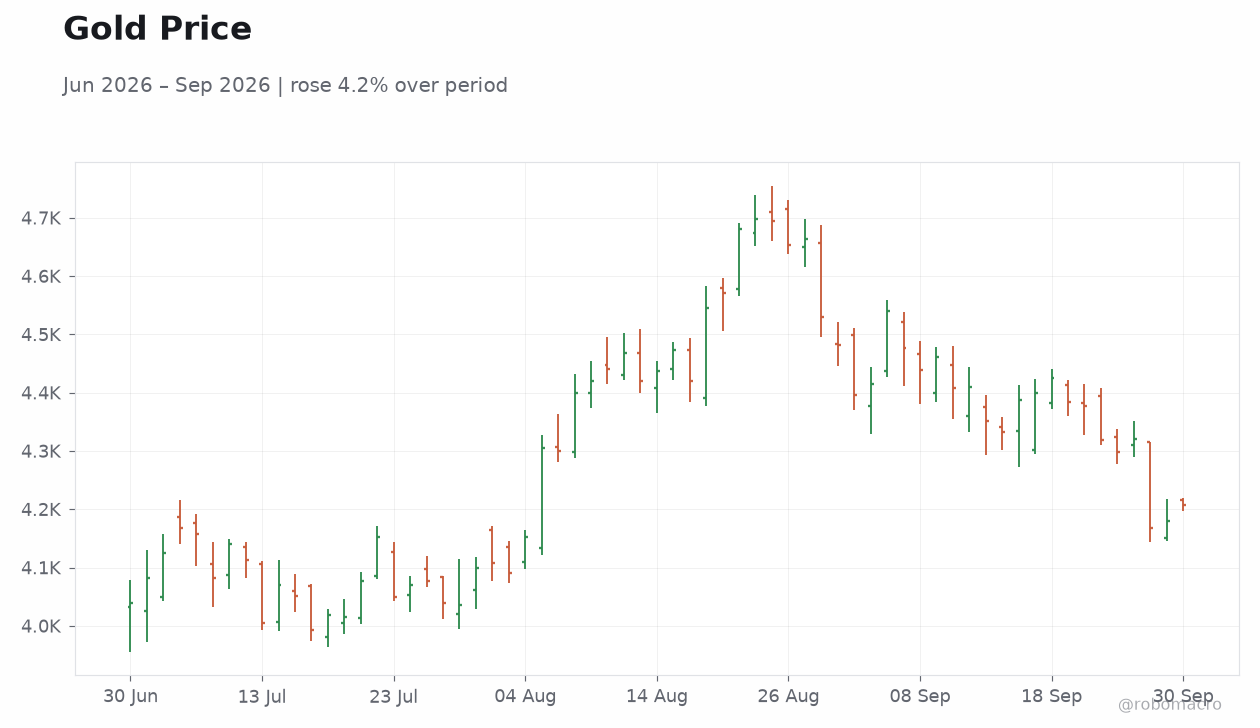
| Gold | 4,208.20 | +0.68% |
| UK Nat Gas | 3.03 | +0.50% |
| Bitcoin | 83,371.67 | -0.16% |
| UK 2Y Gilt | 4.71% | +7 bp |
| UK 10Y Gilt | 5.38% | +2 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| BoE Ramsden Speech | - | - | - |
| Chancellor John Healey Speech | - | - | - |
| Chancellor John Healey Speech | - | - | - |
| BoE Consumer Credit | 2,097m | 1,900m | 2,464m |
| Mortgage Approvals | 55,930 | 56,100 | 54,920 |
| Mortgage Lending Level | 4,080m | 4,400m | 4,410m |
| BoE Taylor Speech | - | - | - |
| Current Account Balance | -22,100m | -25,600m | - |
| Nationwide Housing Prices Month-over-Month | 0.20 | 0.20 | - |
| Nationwide Housing Prices Year-over-Year | 1.60 | - | - |
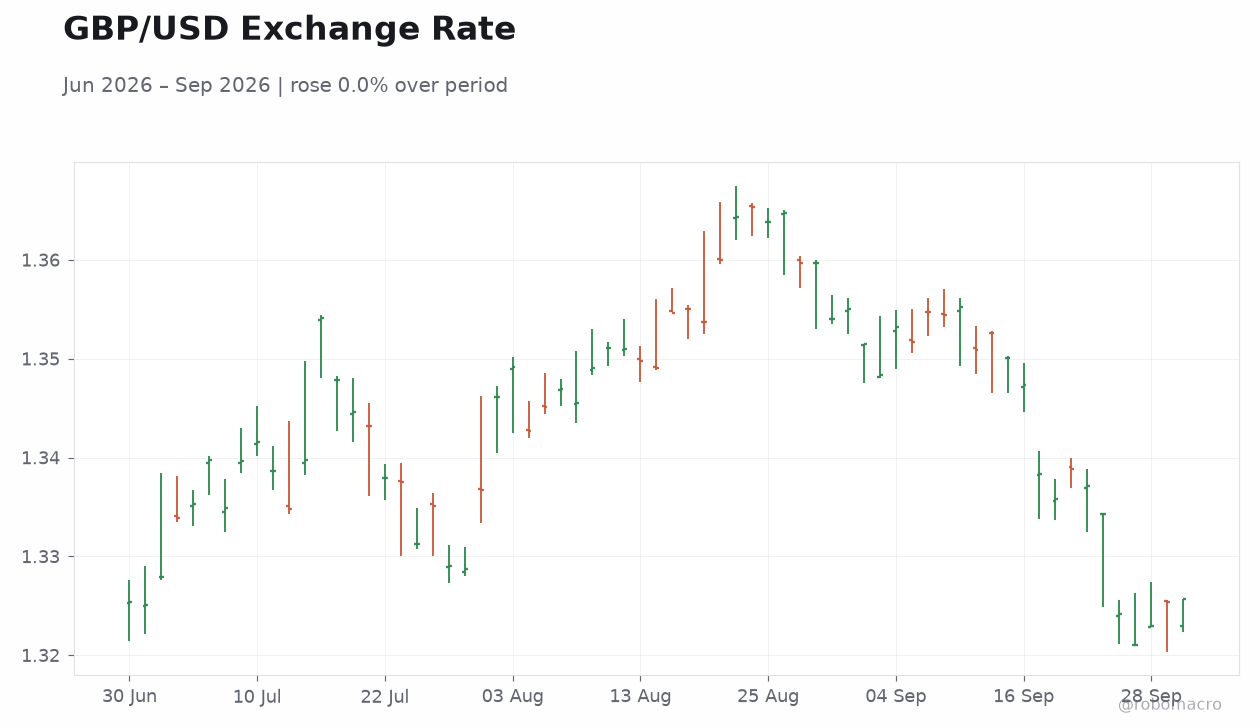 GBP/USD Exchange Rate | Type: market_hloc | GBP/USD: 1.326 (2026-09-30) | Range: 1.321–1.365 | Trend(6pt): 1.325,1.338,1.35,1.353,1.323,1.326
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| Thursday (2026-10-01) | |||
| BoE Mann Speech | - | - | 04:00 |
| BoE Mills Speech | - | - | 05:10 |
- UK consumer credit surged to £2.464bn in August, exceeding the £1.9bn consensus and prior £2.097bn.
- Mortgage approvals fell to 54,920 versus 56,100 expected, while mortgage lending rose to £4.41bn.
- UK 2-year gilt yields climbed 7 bp to 4.71% and 10-year yields added 2 bp to 5.38% as sterling traded mixed.
Yesterday's Recap
UK data releases showed mixed housing signals alongside stronger credit growth. Consumer credit expanded £2.464bn, outpacing forecasts and lifting household borrowing. Mortgage approvals slipped to 54,920 from 55,930 prior, missing the 56,100 consensus.
Mortgage lending reached £4.41bn, slightly above the £4.4bn expectation. FTSE 100 declined 0.21% to 10,662.17 while FTSE 250 gained 0.16%. GBP/USD eased 0.01% to 1.33 and GBP/JPY fell 0.31% to 207.90.
Gilt yields rose across the curve with the 2-year adding 7 bp and the 10-year rising 2 bp. High-impact speeches from BoE’s Ramsden and Taylor plus two addresses by Chancellor Healey kept markets focused on policy signals. Brent crude fell 6.04% to 96.39 while gold rose 0.68% to 4,208.20, reflecting shifting external pressures on UK inflation and energy costs.
The Day Ahead
Two high-impact BoE speeches headline the calendar on 1 October. Catherine Mann speaks at 04:00 ET followed by Andrew Mills at 05:10 ET. Markets will parse any fresh comments on inflation persistence and the energy price outlook.
No major data prints are scheduled. Sterling volatility is likely to rise around the remarks. Traders will watch for hints on the timing of further rate cuts given the 3.73% Bank Rate level.
UK natural gas edged 0.50% higher to 3.03, keeping domestic energy cost vigilance elevated ahead of the remarks.
Other Economic Notes
UK CPI stood at 3.10% year-over-year in August while unemployment reached 4.90% in June. These readings keep the Bank of England on a gradual easing path. Stronger consumer credit supports household spending but weaker mortgage approvals signal caution in the housing market.
Gilt yields remain elevated, with the 2-year at 4.71% and 10-year at 5.38%, reflecting persistent inflation concerns. Broader fiscal commentary from the Chancellor added to market focus on debt dynamics. Current Account Balance and Nationwide House Prices prints were not released, leaving the mixed borrowing data as the main domestic signal.