UK Macro Daily(Beta Mode)
Consumer Credit Beats, BoE Flags AI Risks
Market Snapshot
| Asset | Level | Change |
|---|---|---|
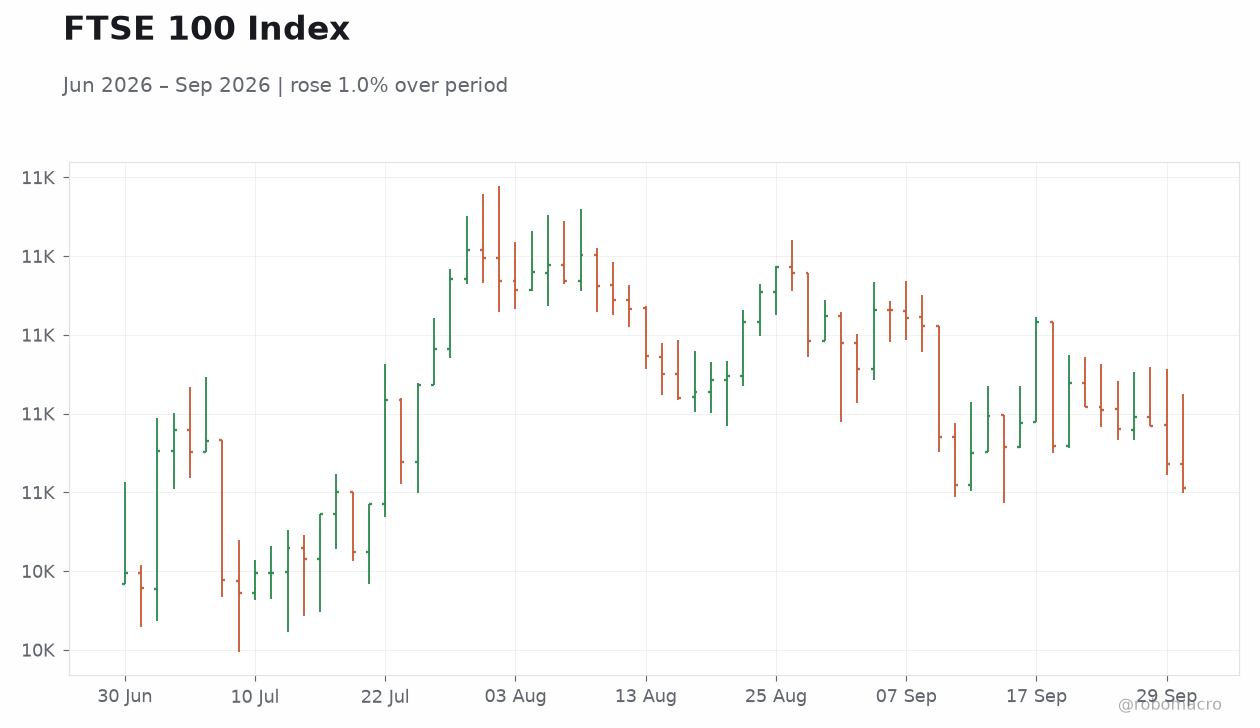
| FTSE 100 | 10,617.11 | -0.18% |
| FTSE 250 | 24,540.00 | +0.68% |
| GBP/USD | 1.33 | +0.14% |
| GBP/EUR | 1.17 | +0.28% |
| GBP/JPY | 208.25 | -0.15% |
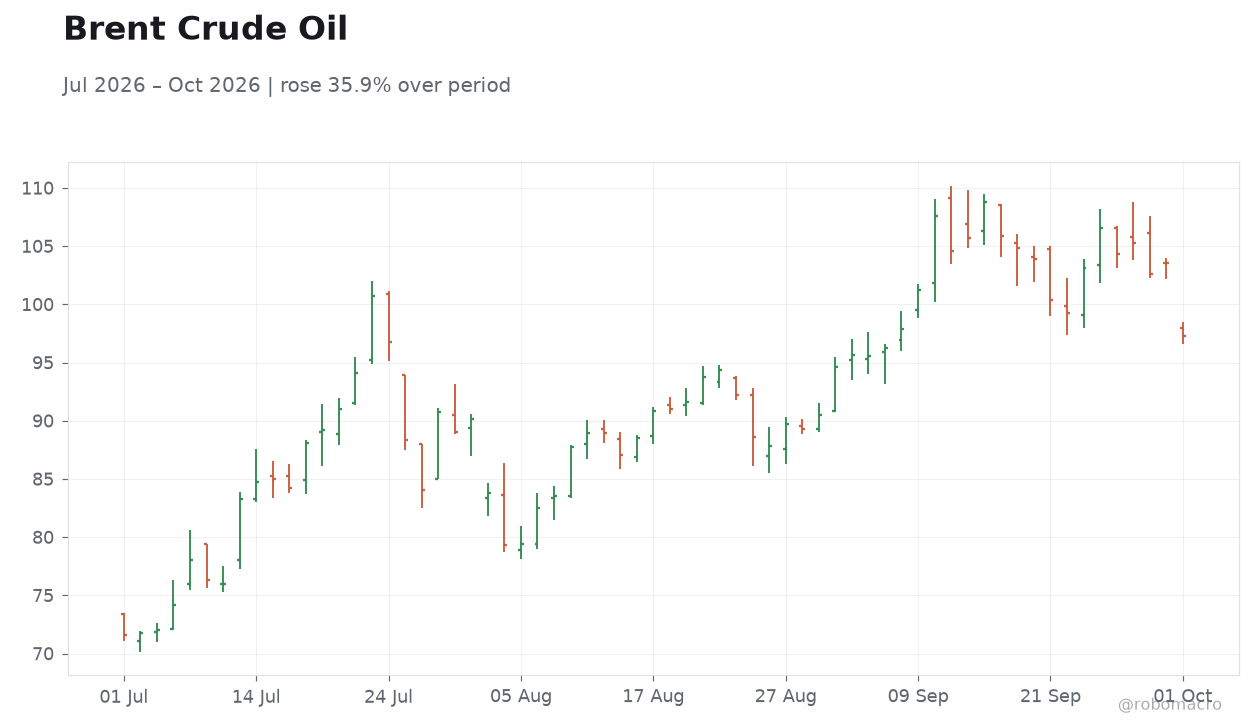
| Brent Crude | 97.25 | -6.07% |
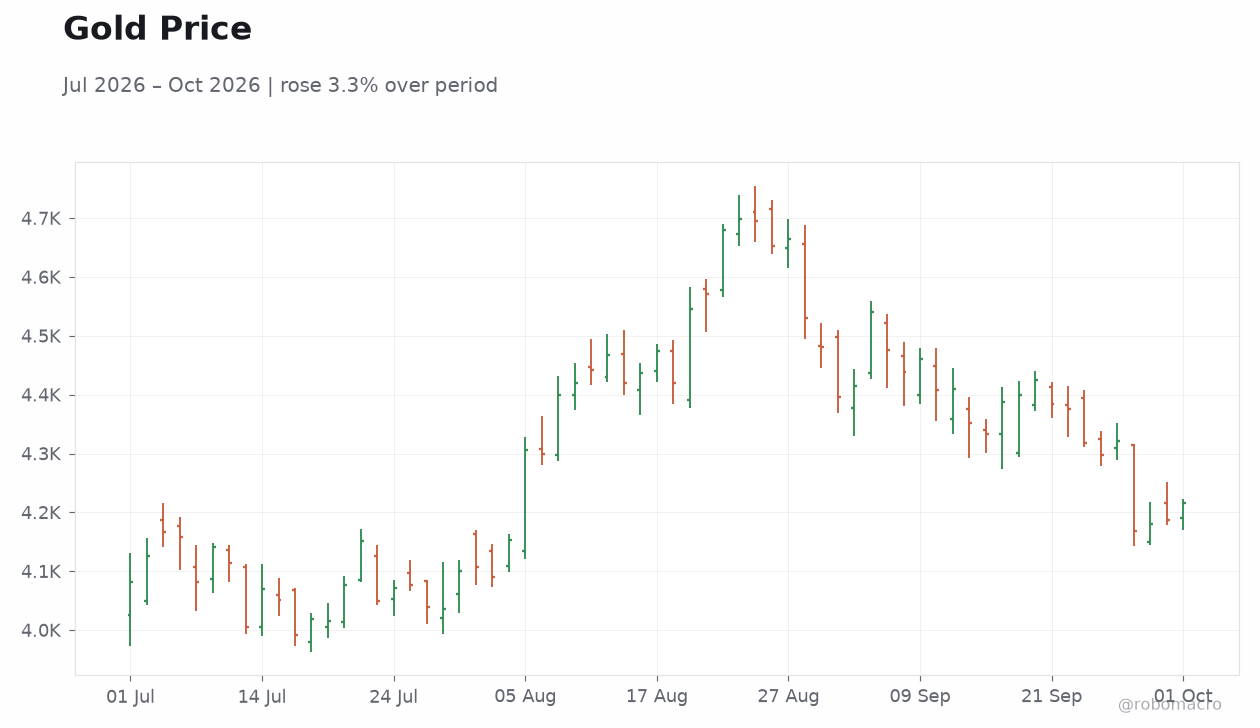
| Gold | 4,217.30 | +0.73% |
| UK Nat Gas | 2.98 | -1.65% |
| Bitcoin | 84,253.13 | +0.75% |
| UK 2Y Gilt | 4.68% | -3 bp |
| UK 10Y Gilt | 5.41% | +3 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| BoE Ramsden Speech | - | - | - |
| Chancellor John Healey Speech | - | - | - |
| Chancellor John Healey Speech | - | - | - |
| BoE Consumer Credit | 2,097m | 1,900m | 2,464m |
| Mortgage Approvals | 55,930 | 56,100 | 54,920 |
| Mortgage Lending Level | 4,080m | 4,400m | 4,410m |
| BoE Taylor Speech | - | - | - |
| Current Account Balance | -21,100m | -24,700m | -19,900m |
| Nationwide Housing Prices Month-over-Month | 0.20 | 0 | - |
| Nationwide Housing Prices Year-over-Year | 1.60 | 1.30 | - |
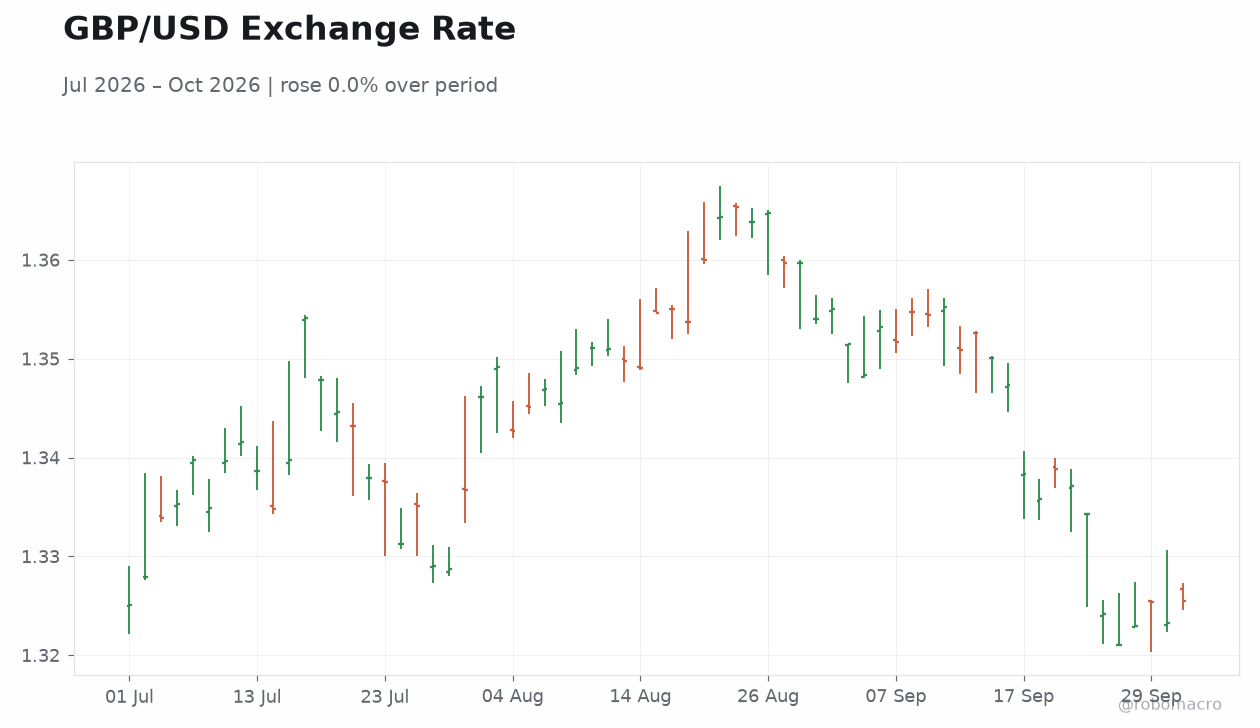 GBP/USD Exchange Rate | Type: market_hloc | Rate: 1.325 (2026-10-01) | Range: 1.321–1.365 | Trend(6pt): 1.325,1.338,1.349,1.352,1.325,1.325
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| BoE Mann Speech | - | - | 04:00 |
| BoE Mills Speech | - | - | 05:10 |
- UK consumer credit rose to £2.464bn in August, beating consensus, while mortgage approvals fell to 54,920.
- Current account deficit narrowed to £19.9bn versus £24.7bn expected, supporting sterling.
- BoE Governor Bailey warned of potential market shocks from AI investment boom and cyber risks.
Yesterday's Recap
UK data releases on 29 September showed resilient household borrowing, with consumer credit expanding £2.464bn against a £1.9bn consensus. Mortgage approvals slipped to 54,920 from 55,930 previously, while net mortgage lending reached £4.41bn, close to expectations. The current account deficit narrowed sharply to £19.9bn, better than the £24.7bn forecast.
High-impact speeches from BoE’s Ramsden and Taylor drew limited immediate market reaction. The FTSE 100 eased 0.18% to 10,617.11 while the FTSE 250 gained 0.68%. Sterling firmed, with GBP/USD rising 0.14% to 1.33 and GBP/EUR up 0.28% to 1.17.
The 2-year gilt yield fell 3bp to 4.68% and the 10-year yield rose 3bp to 5.41%. Nationwide house-price figures due on 30 September remained unreleased.
The Day Ahead
Two high-impact BoE speeches headline the calendar today, with Catherine Mann scheduled at 04:00 ET and Andrew Mills at 05:10 ET. Markets will scrutinise any fresh signals on the policy path given the 3.73% Bank Rate. No major data releases are listed for the UK.
Traders will also monitor any follow-through from yesterday’s stronger credit and narrower external deficit figures. Sterling crosses and gilt yields are expected to remain sensitive to tone from the MPC members.
Other Economic Notes
UK GDP for the second quarter was revised higher to a 0.5% gain, reinforcing the economy’s G7-leading position and supporting household income growth. Unemployment stood at 4.9% in June while CPI inflation printed 3.1% year-on-year in August, leaving the real policy rate comfortably positive. Stronger external balances and credit data suggest domestic demand remains resilient ahead of the November Budget.
Housing market indicators, including Nationwide prices due later, will be watched for signs of cooling.