UK Macro Daily(Beta Mode)
BoE Warns on AI Risks Amid Weak Housing Data
Market Snapshot
| Asset | Level | Change |
|---|---|---|
| FTSE 100 | 10,424.99 | -1.71% |
| FTSE 250 | 24,143.20 | -1.62% |
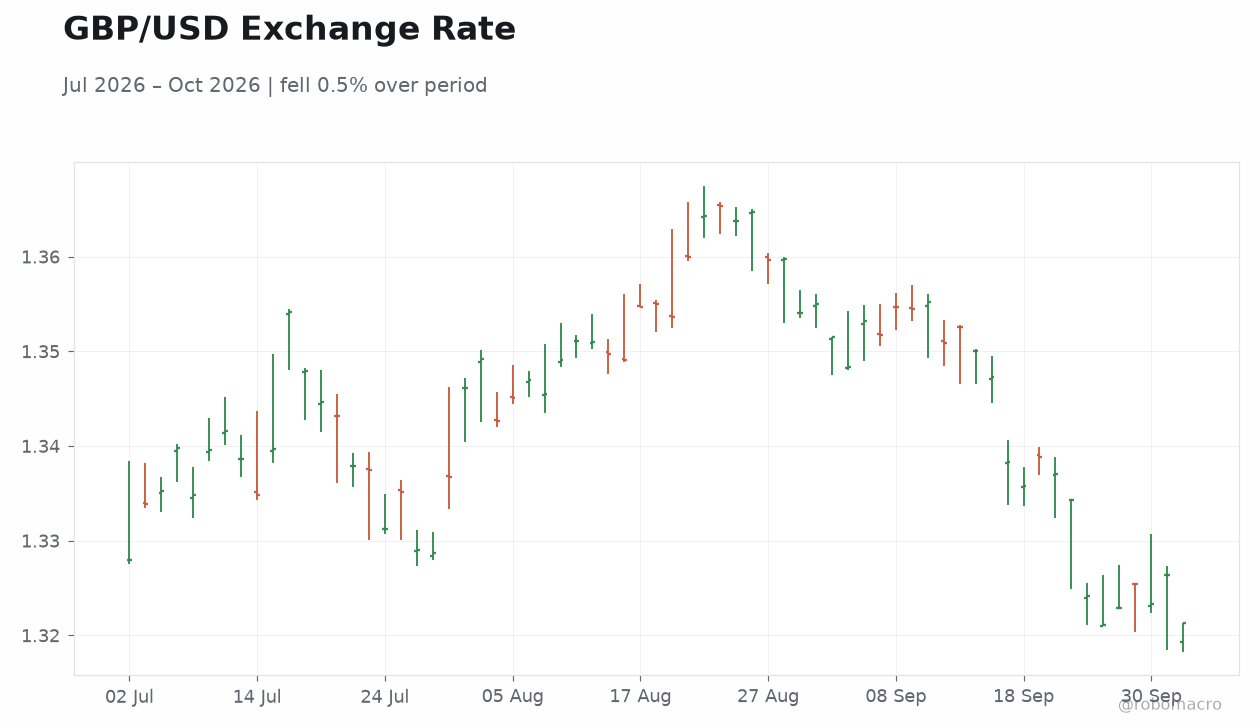
| GBP/USD | 1.32 | -0.43% |
| GBP/EUR | 1.17 | +0.24% |
| GBP/JPY | 208.40 | -0.28% |
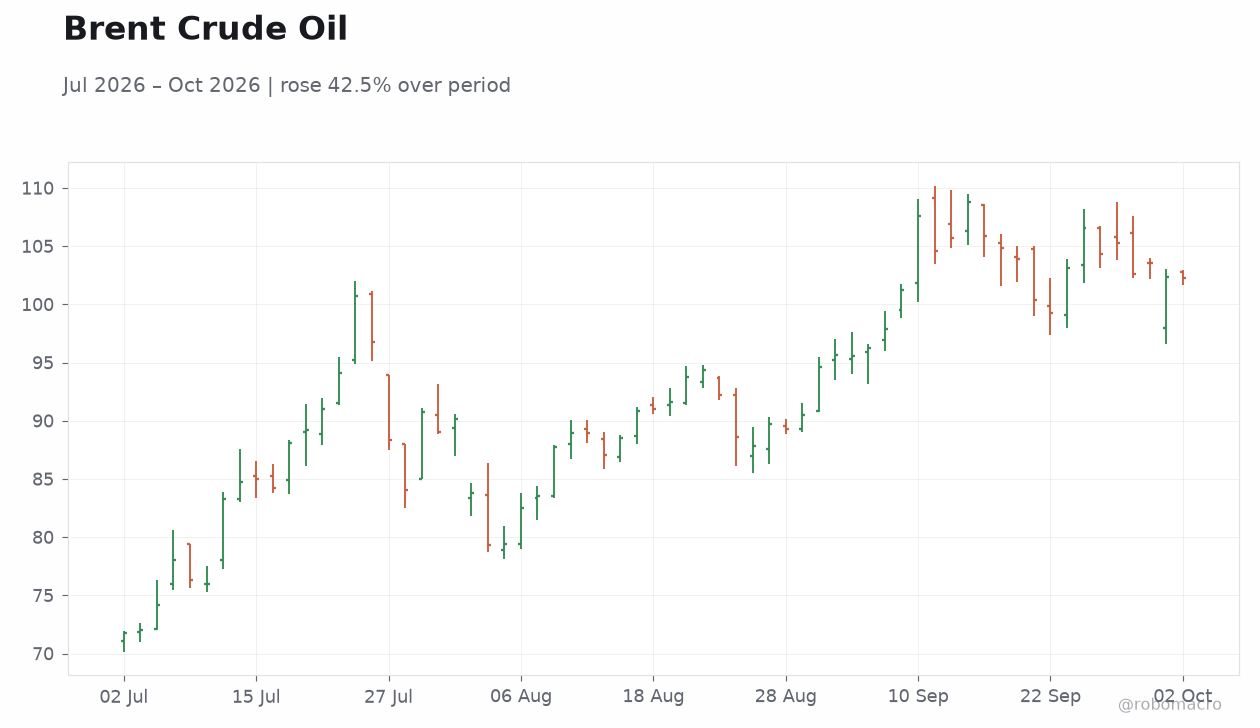
| Brent Crude | 102.10 | -0.21% |
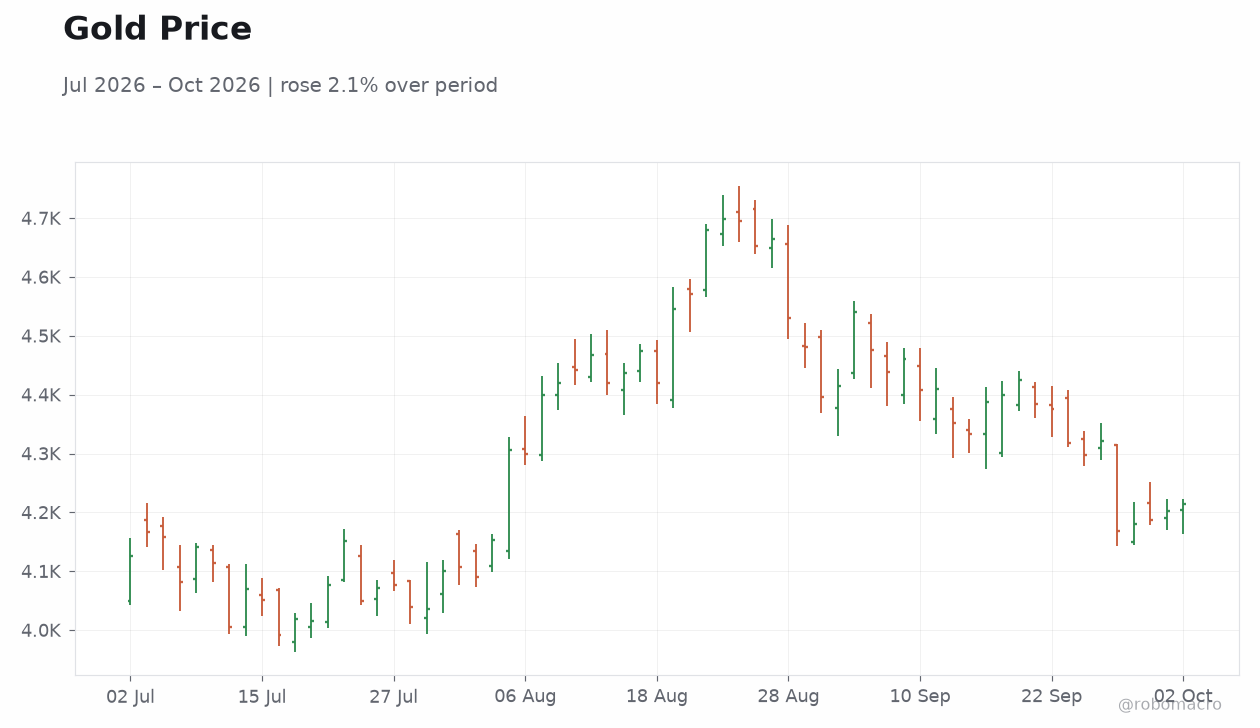
| Gold | 4,214.10 | +0.28% |
| UK Nat Gas | 2.92 | -1.58% |
| Bitcoin | 85,979.95 | +2.90% |
| UK 2Y Gilt | 4.66% | -2 bp |
| UK 10Y Gilt | 5.41% | +3 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| BoE Ramsden Speech | - | - | - |
| Chancellor John Healey Speech | - | - | - |
| Chancellor John Healey Speech | - | - | - |
| BoE Consumer Credit | 2,097m | 1,900m | 2,464m |
| Mortgage Approvals | 55,930 | 56,100 | 54,920 |
| Mortgage Lending Level | 4,080m | 4,400m | 4,410m |
| BoE Taylor Speech | - | - | - |
| Current Account Balance | -21,100m | -24,700m | -19,900m |
| Nationwide Housing Prices Month-over-Month | 0.20 | 0 | -0.20 |
| Nationwide Housing Prices Year-over-Year | 1.60 | 1.30 | 0.80 |
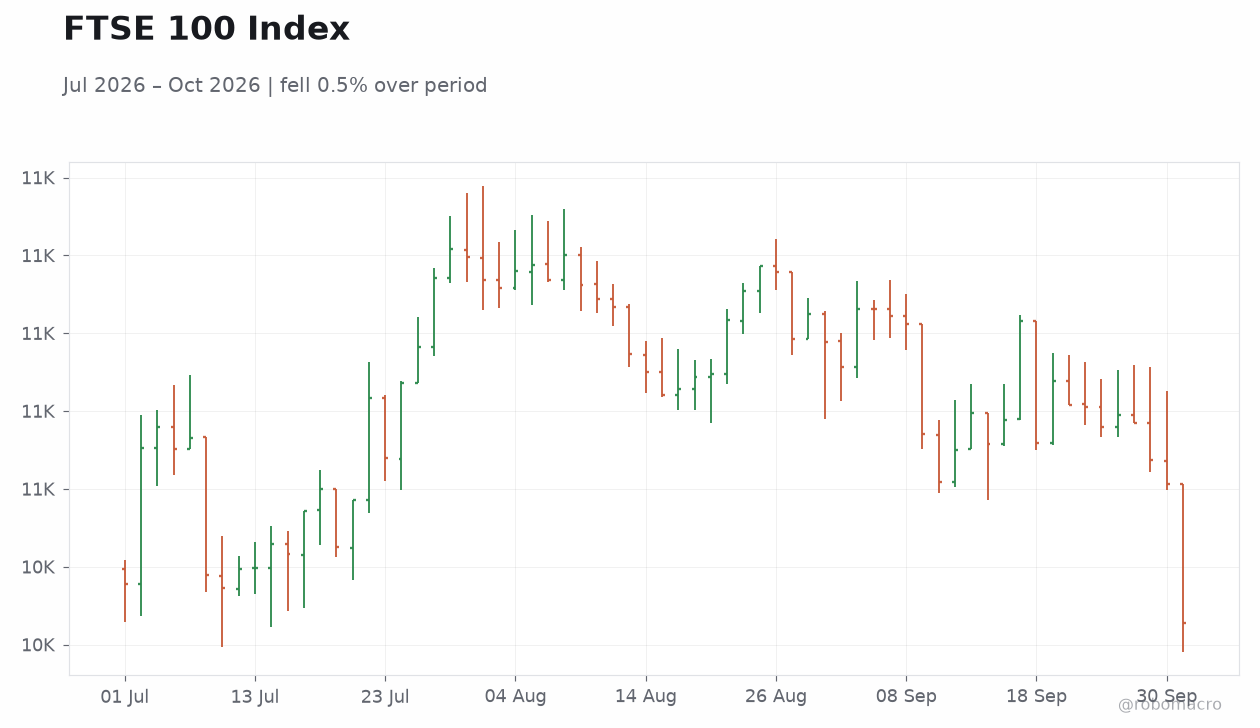 FTSE 100 Index | Type: market_hloc | Price: 1.043e+04 (2026-10-01) | Range: 1.043e+04–1.091e+04 | Trend(6pt): 1.048e+04,1.064e+04,1.075e+04,1.081e+04,1.061e+04,1.043e+04
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| No events available | |||
- Consumer credit beat expectations while mortgage approvals and house prices fell short
- Multiple BoE speakers flag AI threats and call for rate hikes to preserve credibility
- FTSE 100 drops 1.71% as gilt curve steepens and sterling trades mixed
Yesterday's Recap
UK data released on 29-30 September showed resilient borrowing but softening housing demand. BoE consumer credit rose £2.464 billion against a £1.9 billion consensus, while mortgage approvals slipped to 54,920 from 55,930. Mortgage lending reached £4.41 billion, close to forecasts, and the current account deficit narrowed to £19.9 billion versus an expected £24.7 billion.
Nationwide house prices fell 0.2% month-over-month and rose just 0.8% year-over-year, both below consensus. Four BoE MPC members spoke, including Mann and Mills on 1 October. Equities sold off sharply with the FTSE 100 closing at 10,424.99, down 1.71%, and the FTSE 250 off 1.62%.
The 2-year gilt yield eased 2 basis points to 4.66% while the 10-year yield rose 3 basis points to 5.41%, steepening the curve. Sterling weakened 0.43% versus the dollar to 1.32 but gained 0.24% against the euro. UK inflation stands at 3.10% while unemployment has reached 4.90%, leaving the 3.73% Bank Rate well above neutral.
Cooling housing indicators contrast with stronger consumer credit, suggesting uneven domestic demand.
The Day Ahead
No UK economic releases, BoE speeches or MPC events are scheduled for 2 October. Markets will therefore focus on overnight global developments and any follow-through from yesterday’s BoE commentary. Traders will monitor gilt auctions and sterling positioning ahead of next week’s data calendar.
Attention is likely to remain on inflation persistence at 3.10% and the 3.73% Bank Rate level. Positioning in UK assets may stay cautious until fresh guidance emerges from Threadneedle Street.
Other Economic Notes
The current account improvement offers some support to sterling but does little to offset equity weakness. Broader fiscal pressures from elevated energy costs continue to weigh on household finances and gilt supply dynamics. UK natural gas fell 1.58% to 2.92, providing limited relief to household bills.
Central banks worldwide are reassessing responses to supply shocks, with the BoE explicitly criticised for its initial handling of the Iran-related spike. These external factors reinforce the case for vigilance on imported inflation and financial-stability risks.