UK Macro Daily(Beta Mode)
Mann Flags Embedded Inflation as Gilts Steady
Market Snapshot
| Asset | Level | Change |
|---|---|---|
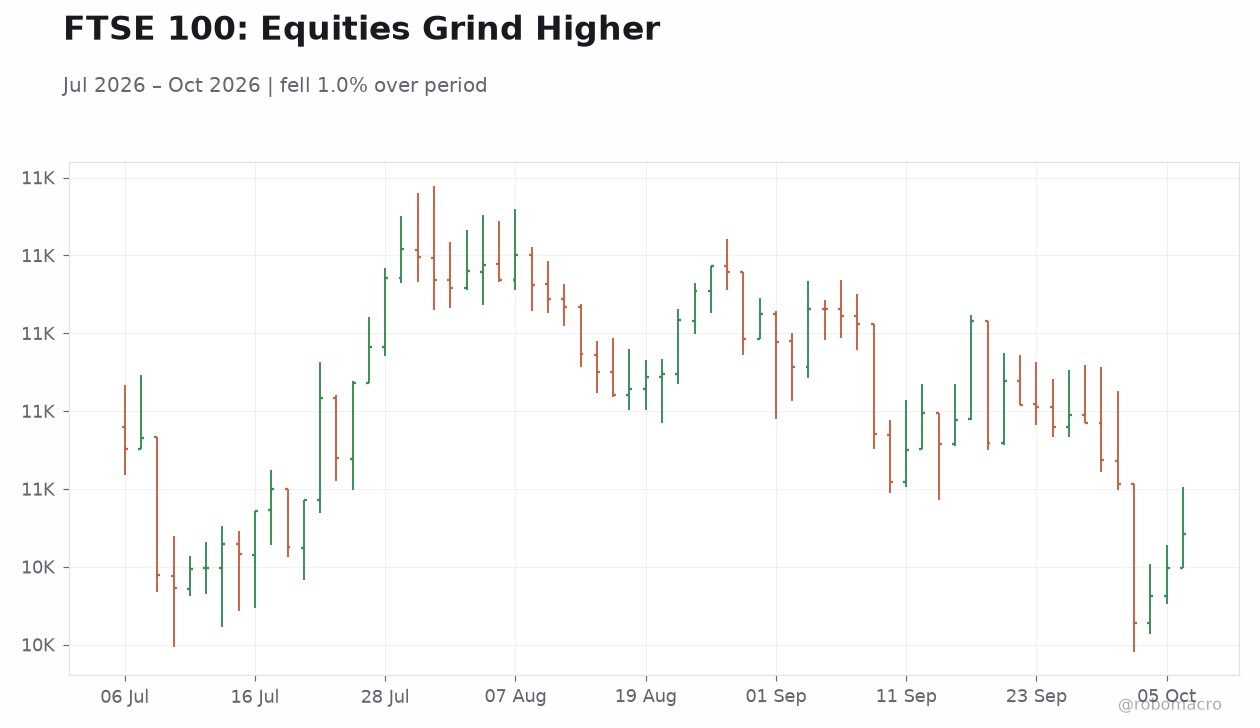
| FTSE 100 | 10,535.68 | +0.36% |
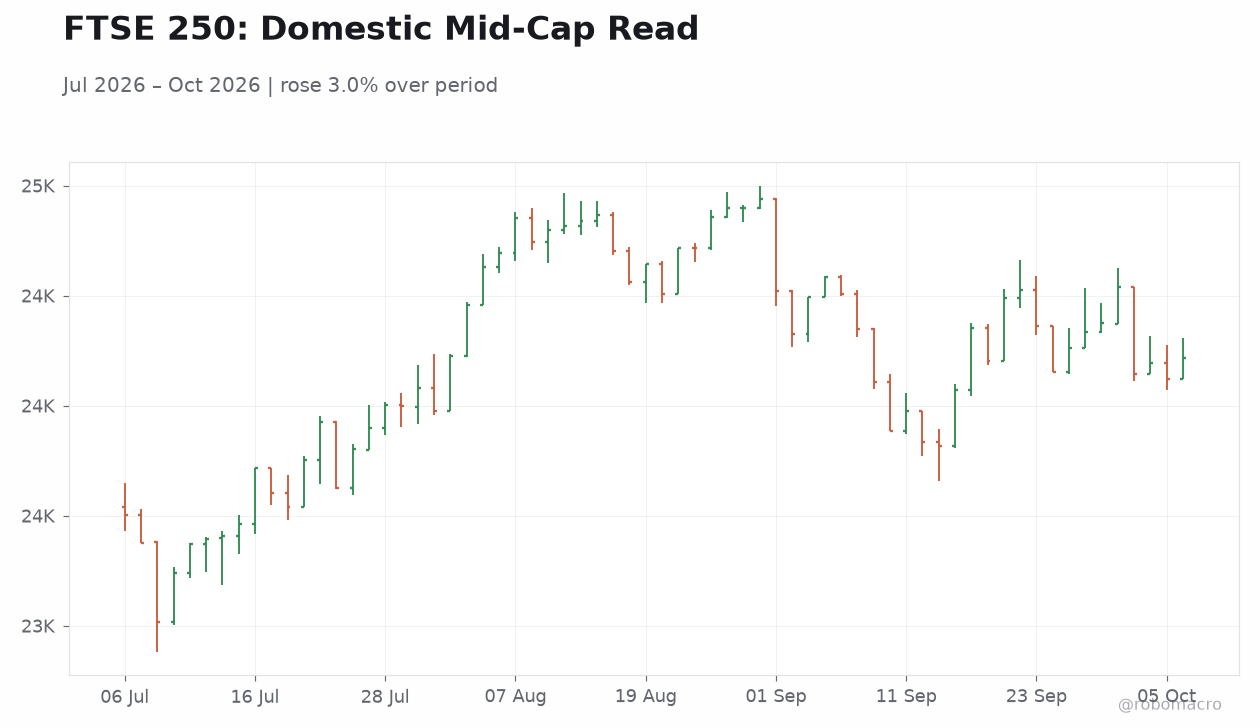
| FTSE 250 | 24,215.30 | +0.38% |
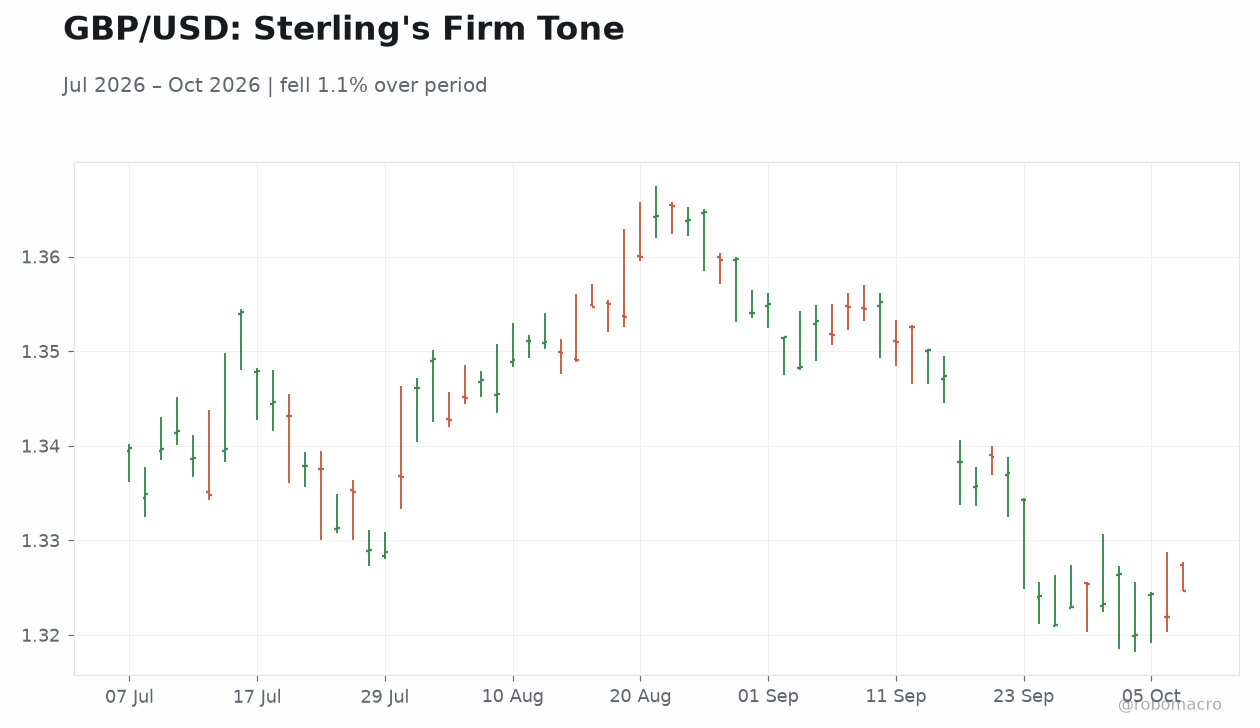
| GBP/USD | 1.32 | +0.23% |
| GBP/EUR | 1.18 | +0.09% |
| GBP/JPY | 209.78 | +0.47% |
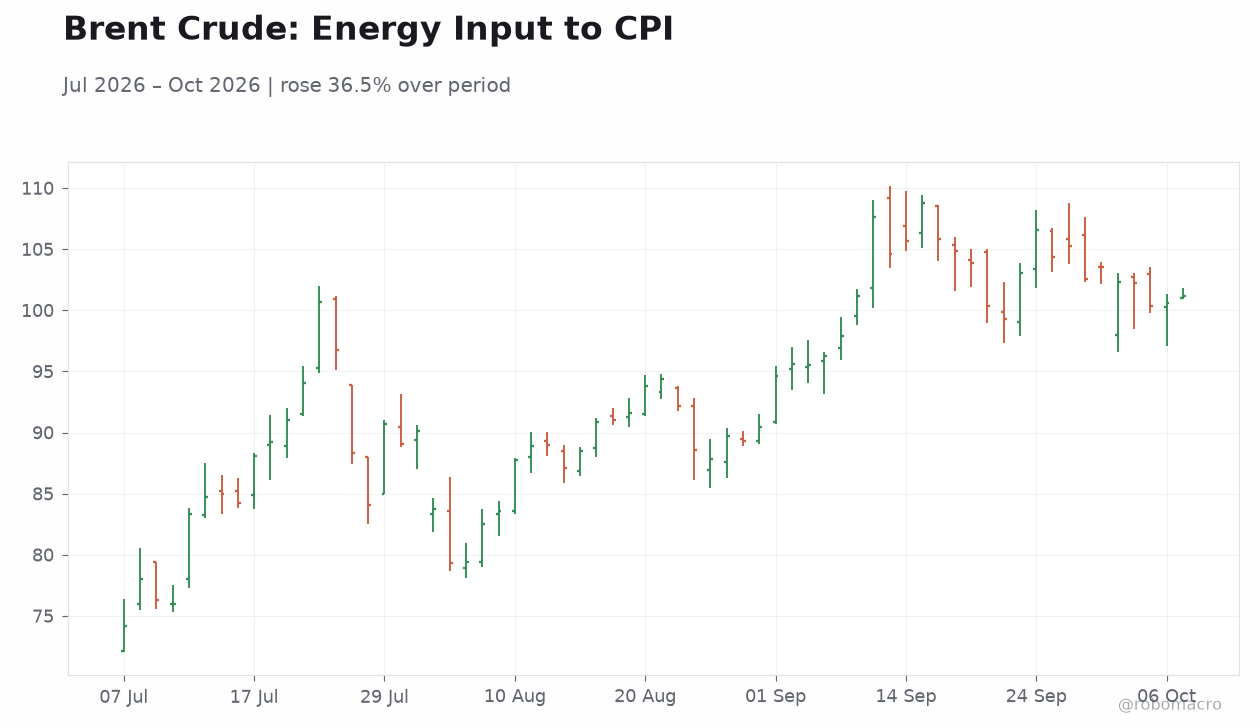
| Brent Crude | 101.25 | +0.67% |
| Gold | 4,162.80 | -0.58% |
| UK Nat Gas | 3.14 | +0.71% |
| Bitcoin | 84,301.66 | -1.73% |
| UK 2Y Gilt | 4.64% | +4 bp |
| UK 10Y Gilt | 5.35% | -7 bp |
Prior Economic Events
| Data | Prior | Cons | Actual |
|---|---|---|---|
| S&P Global Construction PMI | 44.30 | 45.20 | 46.10 |
| Lloyds House Price Index Month-over-Month | -0.20 | 0.20 | - |
| Lloyds House Price Index Year-over-Year | -0.40 | - | - |
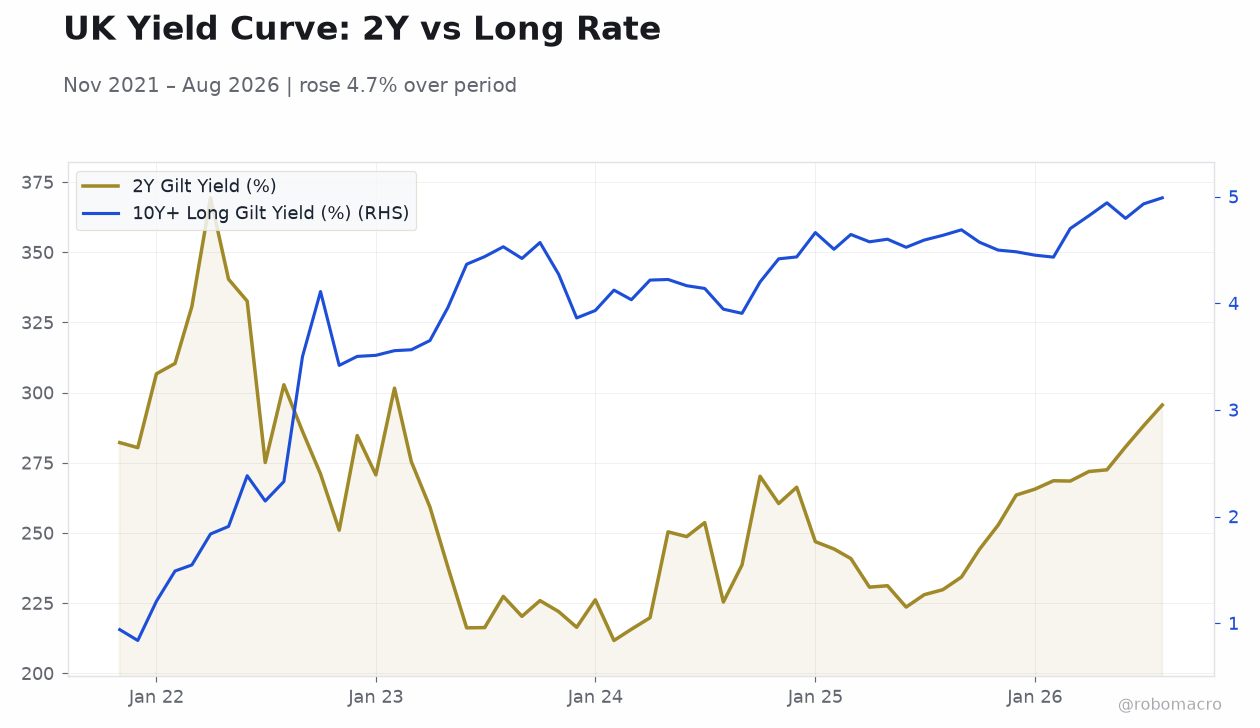 UK Yield Curve: 2Y vs Long Rate | Type: macro_line | 2Y Gilt Yield (%): 295.6 (2026-08-01) | Range: 211.7–369.4 | Trend(6pt): 282.2,270.7,215.7,231.2,288.2,295.6 | 10Y+ Long Gilt Yield (%): 4.989 (2026-08-01) | Range: 0.8375–4.989 | Trend(6pt): 0.9394,3.511,4.033,4.6,4.932,4.989
Today's Economic Events
| Data | Prior | Cons | Time |
|---|---|---|---|
| RICS House Price Balance | -28 | -30 | 19:01 |
- Construction PMI beat at 46.1 but stays contractionary; RICS balance due tonight
- 10-year gilt yield eased 7 bp to 5.35%; 2-year rose 4 bp to 4.64%, steepening curve
- Mann says inflation now embedded; Bank Rate holds at 3.73% with hawkish tilt
Yesterday's Recap
UK equities closed higher on Tuesday despite a soft start, with the FTSE 100 gaining 0.36% to 10,535.68 and the FTSE 250 adding 0.38% to 24,215.30. The S&P Global Construction PMI printed at 46.1, beating the 45.2 consensus and up from 44.3 previously, though the sector remains in contraction. Sterling strengthened broadly: GBP/USD rose 0.23% to 1.32, GBP/EUR added 0.09% to 1.18, and GBP/JPY climbed 0.47% to 209.78.
In fixed income, the 10-year gilt yield eased 7 bp to 5.35% while the 2-year rose 4 bp to 4.64%, steepening the curve as short-end pricing absorbed the Bank of England's hawkish rhetoric. Commodities were mixed: Brent crude climbed 0.67% to $101.25 and UK natural gas gained 0.71% to 3.14, but gold slipped 0.58% to $4,162.80. Bitcoin fell 1.73% to $84,301.66, reflecting weaker sentiment in digital assets.
The Lloyds house price index for September is due this morning; the prior monthly reading was -0.2%.
The Day Ahead
Today's calendar is light, with the RICS House Price Balance at 19:01 UK time the sole UK release. The consensus expects -30, though the prior was -28, so a marginally weaker print is possible; survey momentum has been fragile. Tomorrow's calendar is empty, leaving the market to digest recent BoE commentary and position ahead of the fiscal event.
Attention will then shift to Thursday's US CPI and Friday's UK GDP estimates for Q3. With no domestic data catalysts, gilt yields will likely track global rates and fiscal headlines. Sterling may take direction from risk sentiment and the dollar's trajectory rather than domestic fundamentals.
Other Economic Notes
The UK labour market remains soft, with unemployment at 4.90% as of June, giving the Bank of England some comfort on wage pressures. However, CPI inflation at 3.10% in August remains well above the 2% target, complicating the policy outlook. Construction's continued contraction, despite the PMI beat, underscores the drag from higher borrowing costs on residential and commercial projects.
Housing indicators have been mixed, with the Lloyds index showing monthly declines and survey data pointing to falling prices. ↓ p.2