Gilt Curve Steepens as Bailey, Greene Speak
46.10 S&P Global Construction0 Lloyds House Price Index0 Lloyds House Price Index-32 RICS House Price Balance
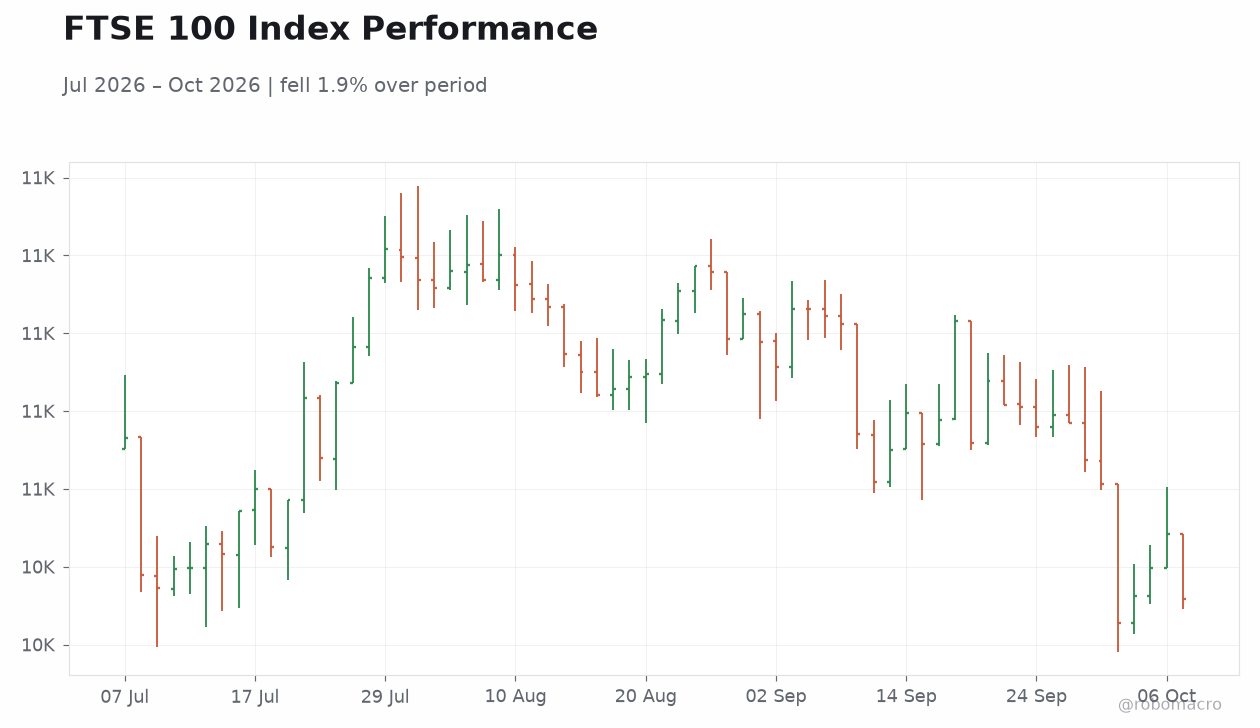
FTSE 10010,456.96-0.80%
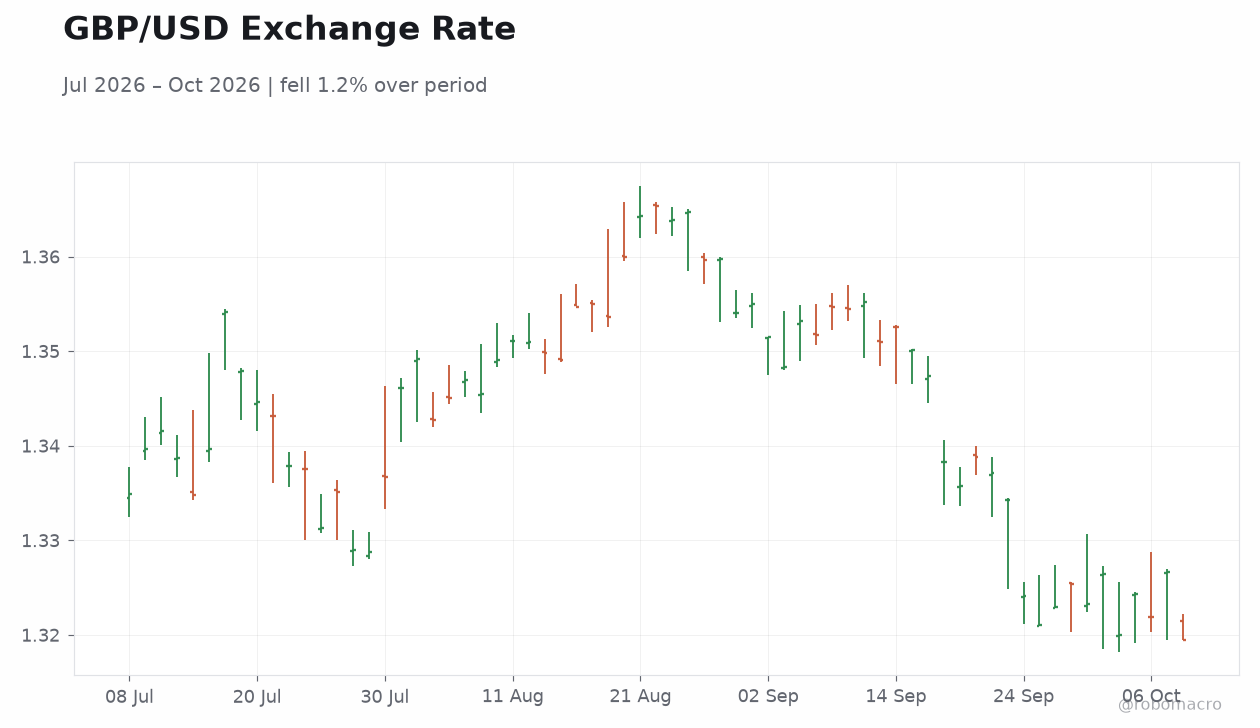
GBP/USD1.32-0.51%
UK 10Y Gilt5.42%+7 bp
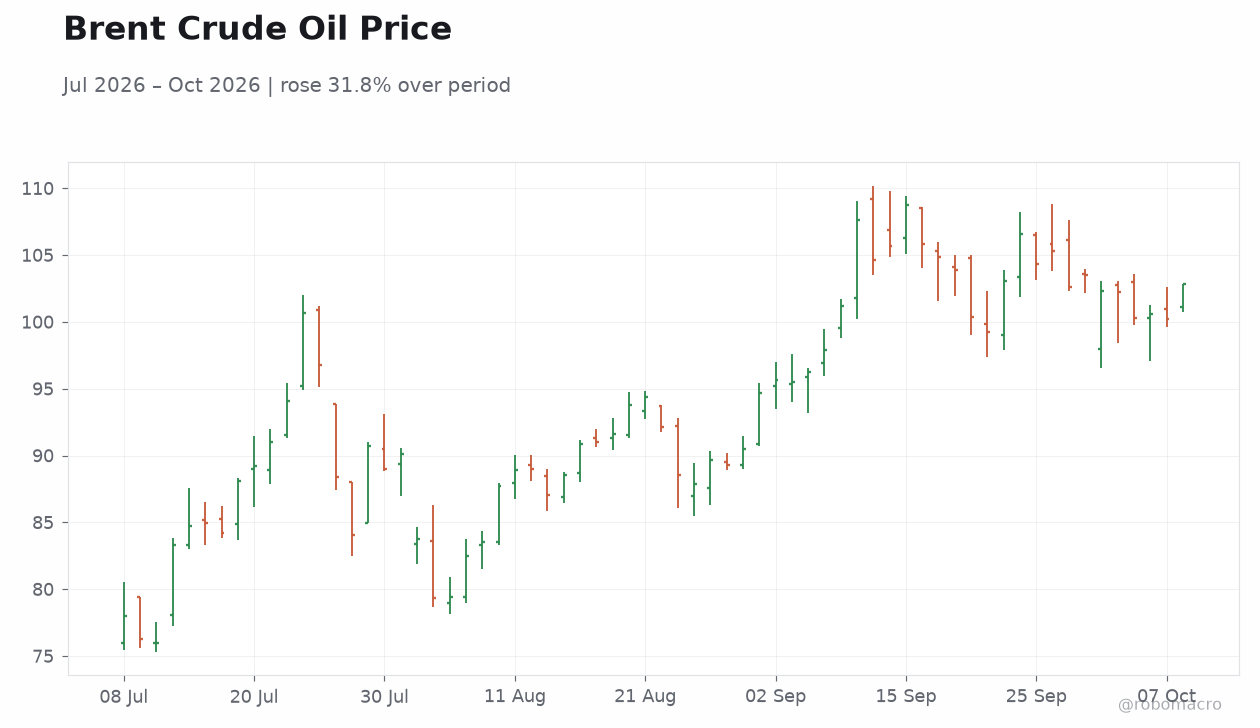
Brent Crude102.76+2.55%
Market Snapshot
| Asset | Level | Change |
|---|
| FTSE 100 | 10,456.96 | -0.80% |
| FTSE 250 | 24,036.80 | -0.74% |
| GBP/USD | 1.32 | -0.51% |
| GBP/EUR | 1.18 | -0.02% |
| GBP/JPY | 208.75 | -0.60% |
| Brent Crude | 102.76 | +2.55% |
| Gold | 4,147.70 | +0.17% |
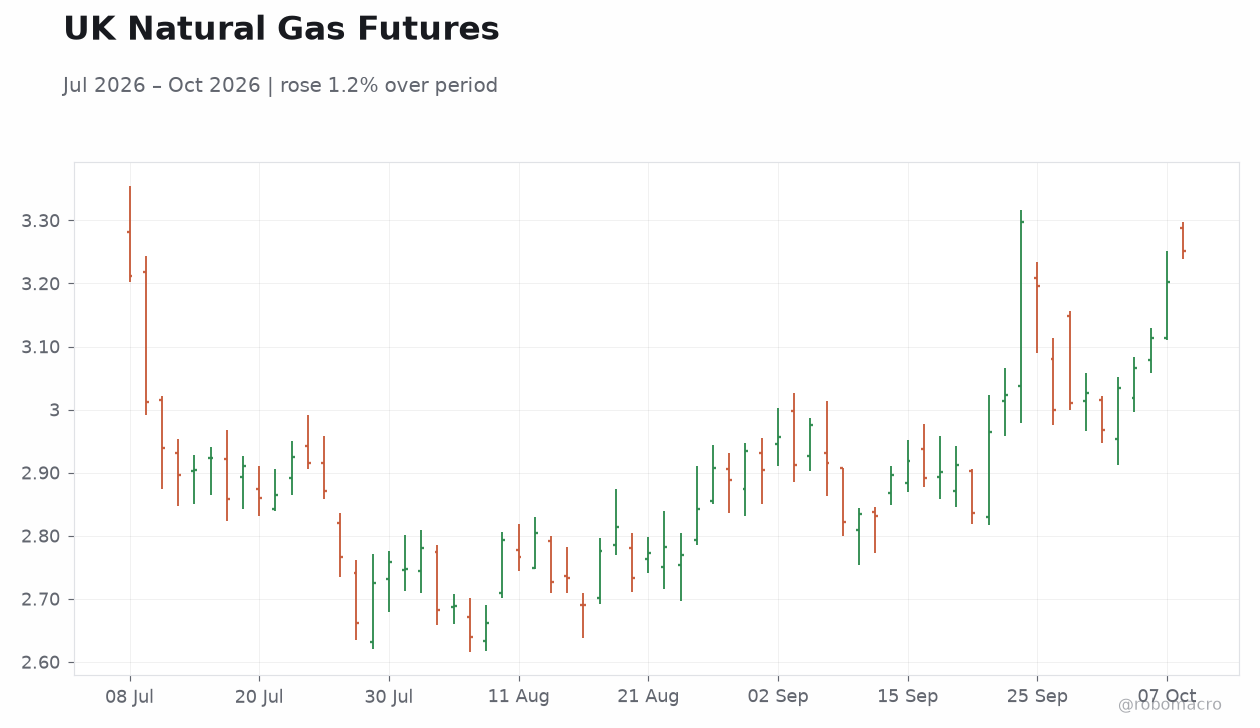
| UK Nat Gas | 3.25 | +1.56% |
| Bitcoin | 82,647.06 | -3.40% |
| UK 2Y Gilt | 4.61% | -3 bp |
| UK 10Y Gilt | 5.42% | +7 bp |
Prior Economic Events
| Data |
Prior |
Cons |
Actual |
| BoE Mann Speech | - | - | - |
| S&P Global Construction PMI | 44.30 | 45.20 | 46.10 |
| Lloyds House Price Index Month-over-Month | -0.30 | 0.20 | 0 |
| Lloyds House Price Index Year-over-Year | -0.40 | - | 0 |
| RICS House Price Balance | -28 | -30 | -32 |
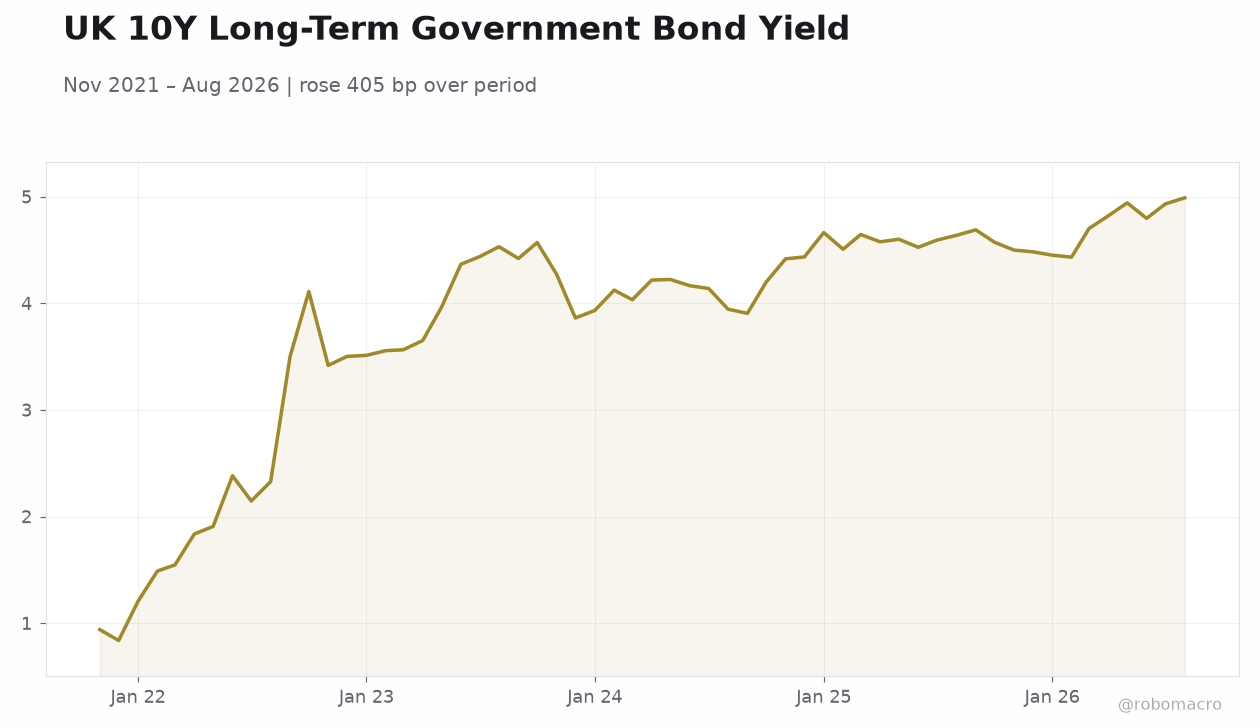 UK 10Y Long-Term Government Bond Yield | Type: macro_line | 10Y Yield (%): 4.989 (2026-08-01) | Range: 0.8375–4.989 | Trend(6pt): 0.9394,3.511,4.033,4.6,4.932,4.989
Today's Economic Events
| Data |
Prior |
Cons |
Time |
| BoE Credit Conditions Survey | - | - | 04:30 |
| BoE Greene Speech | - | - | 05:15 |
| BoE Gov Bailey Speech | - | - | 08:15 |
- UK 10-year gilt yield rose 7 bp to 5.42% while the 2-year eased 3 bp to 4.61%, steepening the curve ahead of a heavy BoE speaker day.
- Construction PMI improved to 46.1 from 44.3, beating the 45.2 consensus, though the sector remains in contraction.
- Housing data softened: RICS balance fell to -32 and Lloyds house prices were flat on the month, underscoring property fragility.
Yesterday's Recap
UK equity markets closed lower, with the FTSE 100 down 0.80% at 10,456.96 and the FTSE 250 off 0.74% at 24,036.80. Sterling weakened against the dollar, with GBP/USD slipping 0.51% to 1.32, while GBP/JPY fell 0.60% to 208.75 and GBP/EUR was broadly flat at 1.18. The gilt curve steepened as the 10-year yield climbed 7 bp to 5.42% while the 2-year eased 3 bp to 4.61%.
On the data front, the S&P Global Construction PMI printed 46.1, up from 44.3 previously and ahead of the 45.2 consensus, though still below the 50 expansion threshold. Housing indicators disappointed: the RICS House Price Balance deteriorated to -32 from -28, missing expectations of -30, while Lloyds house prices were flat month-over-month and year-over-year, defying forecasts of a 0.2% monthly gain. Brent crude surged 2.55% to $102.76, offering a tailwind to the FTSE's energy heavyweights, and UK natural gas rose 1.56%.
Gold edged up 0.17% to $4,147.70 while Bitcoin dropped 3.40% to $82,647.06.
The Day Ahead
Today's calendar is dominated by Bank of England communications. The October Credit Conditions Survey at 04:30 ET will offer a read on lending standards and credit demand across households and corporates, a key input for the MPC's assessment of transmission. MPC member Greene speaks at 05:15 ET, followed by Governor Andrew Bailey at 08:15 ET, giving markets two high-impact opportunities to parse the policy outlook.
With Bank Rate at 3.73% and CPI at 3.1%, attention will focus on how far the committee leans toward further easing versus holding through the autumn Budget period. Any commentary on the pace of quantitative tightening or the balance sheet runoff will be scrutinised given the 10-year yield's climb back above 5.40%. Tomorrow's calendar is currently empty, leaving today's speeches to set the tone into the weekend.
The absence of tier-one data shifts focus to the fiscal pre-Budget narrative, where reports of mounting pressure on the UK economy continue to accumulate.
Page 1
Never miss an issue
Subscribe to UK Macro Daily and get each new issue delivered to your inbox.
Already a member? Visit robomacro.com
to log in and manage subscriptions, or use Forgot Password to set a password.